About Author
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


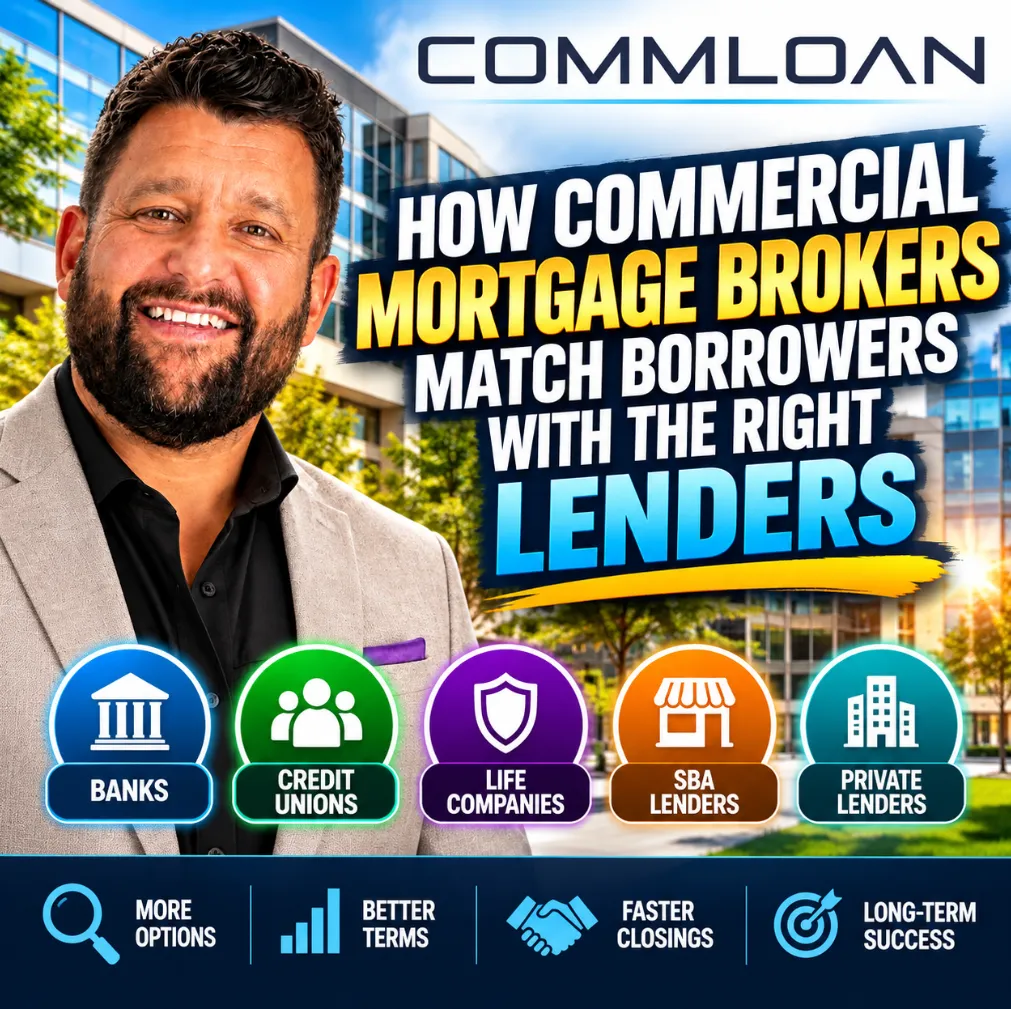
🏦 How Commercial Mortgage Brokers Match Borrowers With the Right Lenders 🔑
🏦 How Commercial Mortgage Brokers Match Borrowers With the Right Lenders 🔑
💰 Find the Right Commercial Real Estate Lender: Why Working With a Mortgage Broker Matters 🏢
________________________________________________________________________________
How Commercial Mortgage Brokers Match Borrowers With the Right Lenders
The right commercial real estate loan isn't always the one with the lowest interest rate. It's the one that fits your property, financial position, investment strategy, and long-term objectives.
Whether you're purchasing an apartment building, refinancing an office property, financing a hotel, or acquiring real estate for your business, finding the right lender can make the difference between a successful closing and a financing disappointment.
Commercial mortgage brokers help bridge the gap between borrowers and lenders by evaluating financing requirements, analyzing the transaction, and identifying lending sources whose programs align with the deal.
I'm Bill Rapp with the CommLoan Empower Program, and here's how that process works.
Why Finding the Right Commercial Mortgage Lender Matters
Commercial real estate financing is not a one-size-fits-all business.
Different lenders have different appetites for property types, geographic markets, loan amounts, borrower profiles, and risk.
For example:
·A community bank may prefer stabilized, owner-occupied commercial properties within its lending footprint.
·A life insurance company may favor larger, stabilized investments with predictable income.
·A private lender may consider transitional properties requiring renovations or lease-up.
·An SBA lender may offer financing options for eligible owner-occupied business properties.
·An agency lender may specialize in qualifying multifamily housing transactions.
A commercial mortgage broker's job is to understand these differences and help position your financing request with lenders that are more likely to consider it.
Step 1: Understanding the Borrower's Financial Goals
Before approaching lenders, an experienced commercial mortgage broker begins by asking questions.
What are you trying to accomplish?
Are you purchasing, refinancing, constructing, renovating, or extracting equity from a property?
Are you looking for maximum loan proceeds, lower monthly payments, a longer fixed-rate period, or greater flexibility?
Other important questions include:
·How much equity or down payment is available?
·How long do you intend to hold the property?
·Is the property stabilized or undergoing a transition?
·What is your experience with similar investments?
·How important is nonrecourse financing?
·Do you anticipate selling or refinancing before maturity?
These answers establish the framework for the financing strategy.
A loan that works for a long-term apartment investor may be completely inappropriate for a developer planning to sell within 18 months.
Step 2: Analyzing the Property and Its Cash Flow
Commercial real estate lenders evaluate more than the borrower's credit score.
They also evaluate the property and its ability to support the proposed debt.
Three common underwriting metrics are particularly important.
Loan-to-Value Ratio (LTV)
LTV measures the loan amount relative to the property's value.
Formula:
LTV = Loan Amount ÷ Property Value
For example, a $1.5 million loan against a $2 million property represents 75% LTV.
Lenders establish different maximum LTV requirements depending on the asset, transaction, and risk profile.
Debt Service Coverage Ratio (DSCR)
DSCR measures how effectively the property's net operating income supports its debt payments.
Formula:
DSCR = Net Operating Income ÷ Annual Debt Service
For example, if a property generates $150,000 in annual NOI and requires $120,000 in annual debt service, the DSCR is 1.25x.
That means the property generates $1.25 in NOI for every $1 of required annual debt service.
Debt Yield
Debt yield measures a property's NOI relative to the proposed loan amount.
Formula:
Debt Yield = Net Operating Income ÷ Loan Amount
If a property produces $150,000 in NOI and the proposed loan is $1.5 million, the debt yield is 10%.
Debt yield provides another perspective on credit risk without relying directly on the property's appraised value or the loan's interest rate.
Important: The maximum available loan is often constrained by whichever underwriting requirement produces the lowest permissible loan amount.
Step 3: Identifying the Right Type of Commercial Lender
Commercial mortgage brokers evaluate multiple lender categories rather than assuming one financing source is appropriate for every borrower.
Banks and Credit Unions
Banks and credit unions may be strong candidates for stabilized investment properties and owner-occupied commercial real estate.
They may offer competitive pricing and established banking relationships, but underwriting requirements, recourse provisions, geographic restrictions, and deposit expectations can vary.
Life Insurance Companies
Life insurance lenders often focus on stabilized, income-producing commercial real estate with experienced sponsorship.
Certain programs may offer long-term fixed-rate structures and nonrecourse financing, subject to customary carveouts.
Agency Multifamily Lenders
Fannie Mae and Freddie Mac multifamily programs may be appropriate for eligible apartment properties.
These programs can provide competitive financing structures for qualifying transactions, although eligibility, affordability requirements, property condition, and borrower qualifications matter.
SBA Lenders
SBA 7(a) and 504 programs can help eligible small businesses finance owner-occupied commercial real estate.
These programs are not generally intended for passive real estate investment.
Bridge and Private Lenders
Bridge lenders and private capital sources can be valuable for properties that are not yet suitable for permanent financing.
Examples include properties undergoing renovation, lease-up, repositioning, or other transitional business plans.
However, borrowers must carefully evaluate financing costs, maturity dates, extension options, and exit strategies.
CMBS and Other Capital Markets Lenders
Commercial mortgage-backed securities financing may provide another option for qualifying income-producing properties.
These loans can have distinctive requirements regarding servicing, reserves, cash management, defeasance, and prepayment.
Understanding those provisions before closing is essential.
Step 4: Matching the Financing Strategy to the Property
Consider three different borrowing situations.
Scenario A: Stabilized Apartment Building
An investor is acquiring a 60-unit apartment property with consistent occupancy and predictable operating income.
Potential lender categories could include agency multifamily lenders, banks, and life insurance companies.
The best choice depends on proceeds, interest rate, amortization, recourse, reserves, and the investor's anticipated hold period.
Scenario B: Vacant Retail Property Requiring Renovations
An investor is acquiring a partially vacant retail center and plans to renovate the property, attract tenants, and refinance after stabilization.
A bridge lender may be more appropriate than a permanent lender because the property's current cash flow may not support conventional financing.
The financing should be structured around the renovation budget, lease-up assumptions, carrying costs, and realistic exit strategy.
Scenario C: Business Owner Purchasing an Office Building
A growing professional services company wants to purchase the building it will occupy.
A conventional bank loan or qualifying SBA program may be worth evaluating.
Owner-occupancy, operating business cash flow, eligibility, equity requirements, and loan structure will influence the decision.
These examples demonstrate why identifying the right lender requires more than comparing advertised interest rates.
Step 5: Comparing Commercial Mortgage Loan Offers
Once potential lenders are identified, the next step is comparing the actual financing structures.
At a minimum, borrowers should evaluate five factors:
1.Interest Rate: What is the actual borrowing cost, and is the rate fixed or floating?
2.Loan Proceeds: How much financing is available after applying LTV, DSCR, debt yield, and other constraints?
3.Loan Term: When does the loan mature, and does the amortization extend beyond the maturity date?
4.Recourse: Is the borrower personally liable, or is the loan nonrecourse subject to carveouts?
5.Prepayment: What happens financially if the property is sold or refinanced before maturity?
Borrowers should also compare lender fees, reserves, covenants, closing requirements, and extension options.
A lower interest rate does not necessarily create the lowest total financing cost.
For example, a loan with attractive pricing but expensive yield maintenance or defeasance provisions may be a poor fit for an investor planning an early sale.
Step 6: Preparing the Loan Package
A commercial mortgage broker helps assemble a financing package that allows lenders to evaluate the opportunity efficiently.
Common documentation includes:
·Current rent roll
·Trailing 12-month operating statement
·Historical property financial statements
·Borrower financial statement and liquidity verification
·Sponsor real estate experience
·Purchase contract, when applicable
·Property description and capital improvement budget
·Existing loan information for refinances
·Business financial statements for owner-occupied properties
A well-organized submission helps lenders understand the transaction and can reduce unnecessary underwriting questions.
It does not eliminate due diligence or guarantee approval.
Step 7: Navigating Underwriting and Closing
Identifying a lender is only part of the financing process.
Once a financing proposal is accepted, the transaction typically proceeds through underwriting, appraisal, environmental review, title work, legal documentation, and final credit approval.
A commercial mortgage broker helps coordinate communications, address outstanding conditions, and identify potential issues before they jeopardize the closing timeline.
Experienced financing guidance becomes particularly valuable when unexpected challenges arise.
Examples include a lower-than-expected appraisal, insufficient DSCR, changes in tenant occupancy, or newly identified property repairs.
How the CommLoan Empower Program Helps Borrowers
Through the CommLoan Empower Program, I help commercial real estate investors and business owners evaluate financing alternatives using a marketplace-oriented approach.
CommLoan's CUPID™ platform provides access to a network of 700+ lending sources, creating opportunities to identify financing programs across multiple lender categories.
Rather than starting with one lender's product menu, the process begins with the borrower's transaction and financial objectives.
The goal is to help borrowers:
·Identify lenders that fit their property and financing requirements.
·Understand how lenders evaluate cash flow and risk.
·Compare financing structures beyond the quoted interest rate.
·Prepare stronger loan submissions.
·Make more informed capital decisions.
Access to a broad lender network does not mean every lender will finance every transaction, and all financing remains subject to eligibility, underwriting, and lender approval.
Frequently Asked Questions
Is a commercial mortgage broker better than going directly to a bank?
It depends on the transaction. A bank relationship may be an excellent financing source, but a commercial mortgage broker can help compare alternative lender programs and structures that may not be available through a single institution.
Can commercial mortgage brokers finance properties nationwide?
Many commercial mortgage brokerage platforms work with lenders across the United States. Availability depends on the property's location, lender licensing and geographic requirements, loan size, and asset type.
What credit score is required for a commercial real estate loan?
Requirements vary significantly. Lenders may consider personal credit, sponsor experience, liquidity, net worth, property cash flow, collateral, and guarantor strength.
Can a commercial mortgage broker help with refinancing?
Yes. Brokers can assist with rate-and-term refinancing, qualifying cash-out transactions, maturity refinancing, and financing for repositioned properties.
How are commercial mortgage brokers compensated?
Compensation structures vary. Fees may be paid by borrowers, lenders, or through other disclosed arrangements, depending on the program and applicable requirements. Borrowers should request a clear explanation of all compensation and financing costs.
Final Thoughts: The Right Lender Can Change the Outcome
Successful commercial real estate financing begins with understanding the deal.
A property may be attractive, but the wrong financing structure can create unnecessary risk, restrict future options, or undermine an investment strategy.
The right commercial mortgage broker helps evaluate the property, understand the borrower's objectives, identify suitable lending sources, and compare loan structures before important decisions are made.
The objective isn't simply to get a loan. It's to secure financing that supports the investment strategy.
Let's Discuss Your Commercial Real Estate Financing
I'm Bill Rapp, CCIM, with the CommLoan Empower Program.
Whether you're acquiring, refinancing, developing, or repositioning commercial real estate, let's evaluate the transaction and explore available financing options.
Website: https://billrapp.commloan.com/
Schedule a Consultation: https://calendly.com/vikingenterprise
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Our Journey Towards Storytelling Excellence
As an author, I aim to create stories that captivate and inspire. My passion for storytelling drives me to craft unique characters and worlds that leave a lasting impact on readers.

Our Story
Founded with a passion for storytelling, we’ve been empowering aspiring authors to bring their ideas to life and share them with the world.

Our Growth
Since our inception, we’ve helped countless authors find their voice and publish successful books, growing our reach and impact in the literary world.

Our Approach
We focus on personalized coaching, guiding authors through every stage of writing, editing, and publishing, ensuring their creative vision shines.

Our Mission
Our mission is to inspire, educate, and support authors in creating stories that resonate, fostering a community of successful, confident writers.
- LATEST BOOKS -
All Latest Books
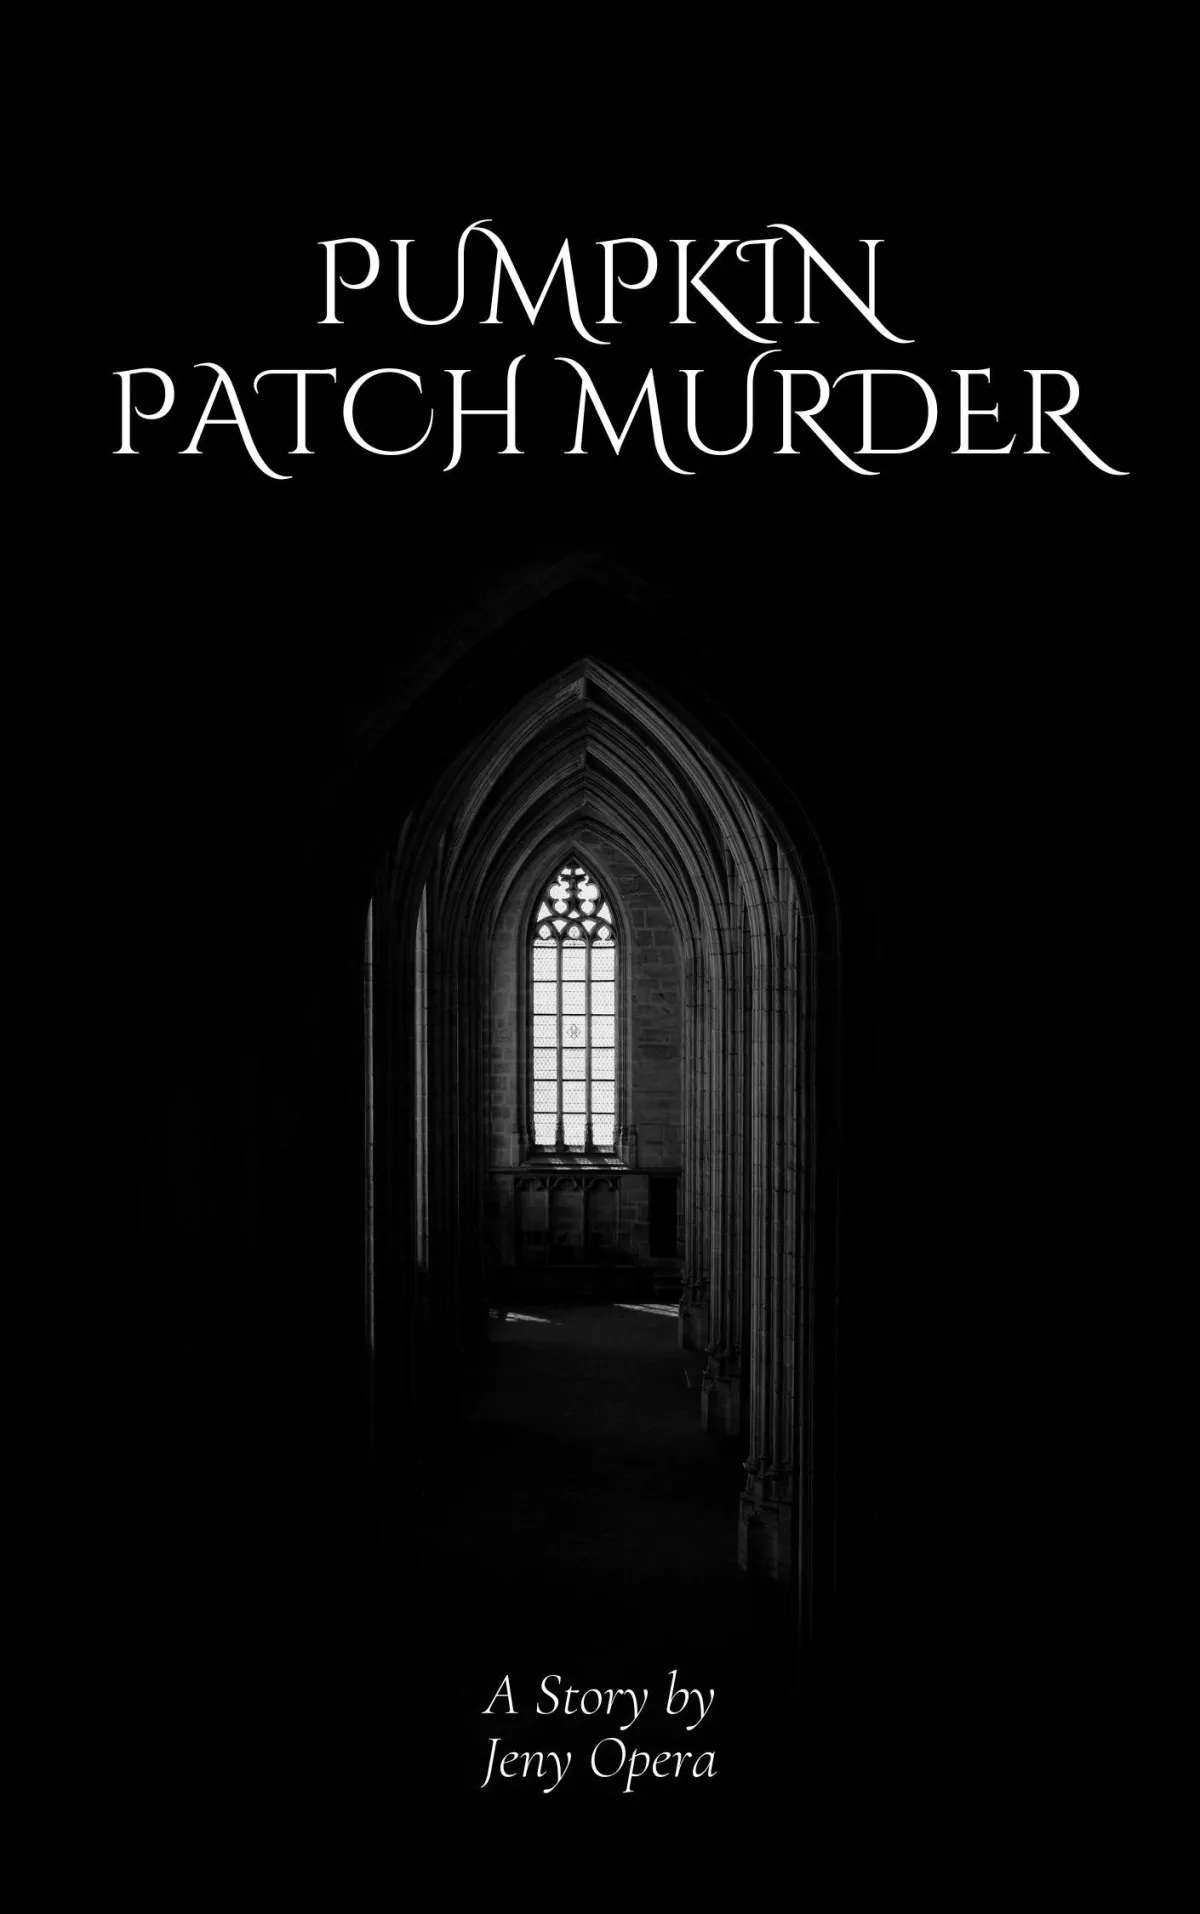
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
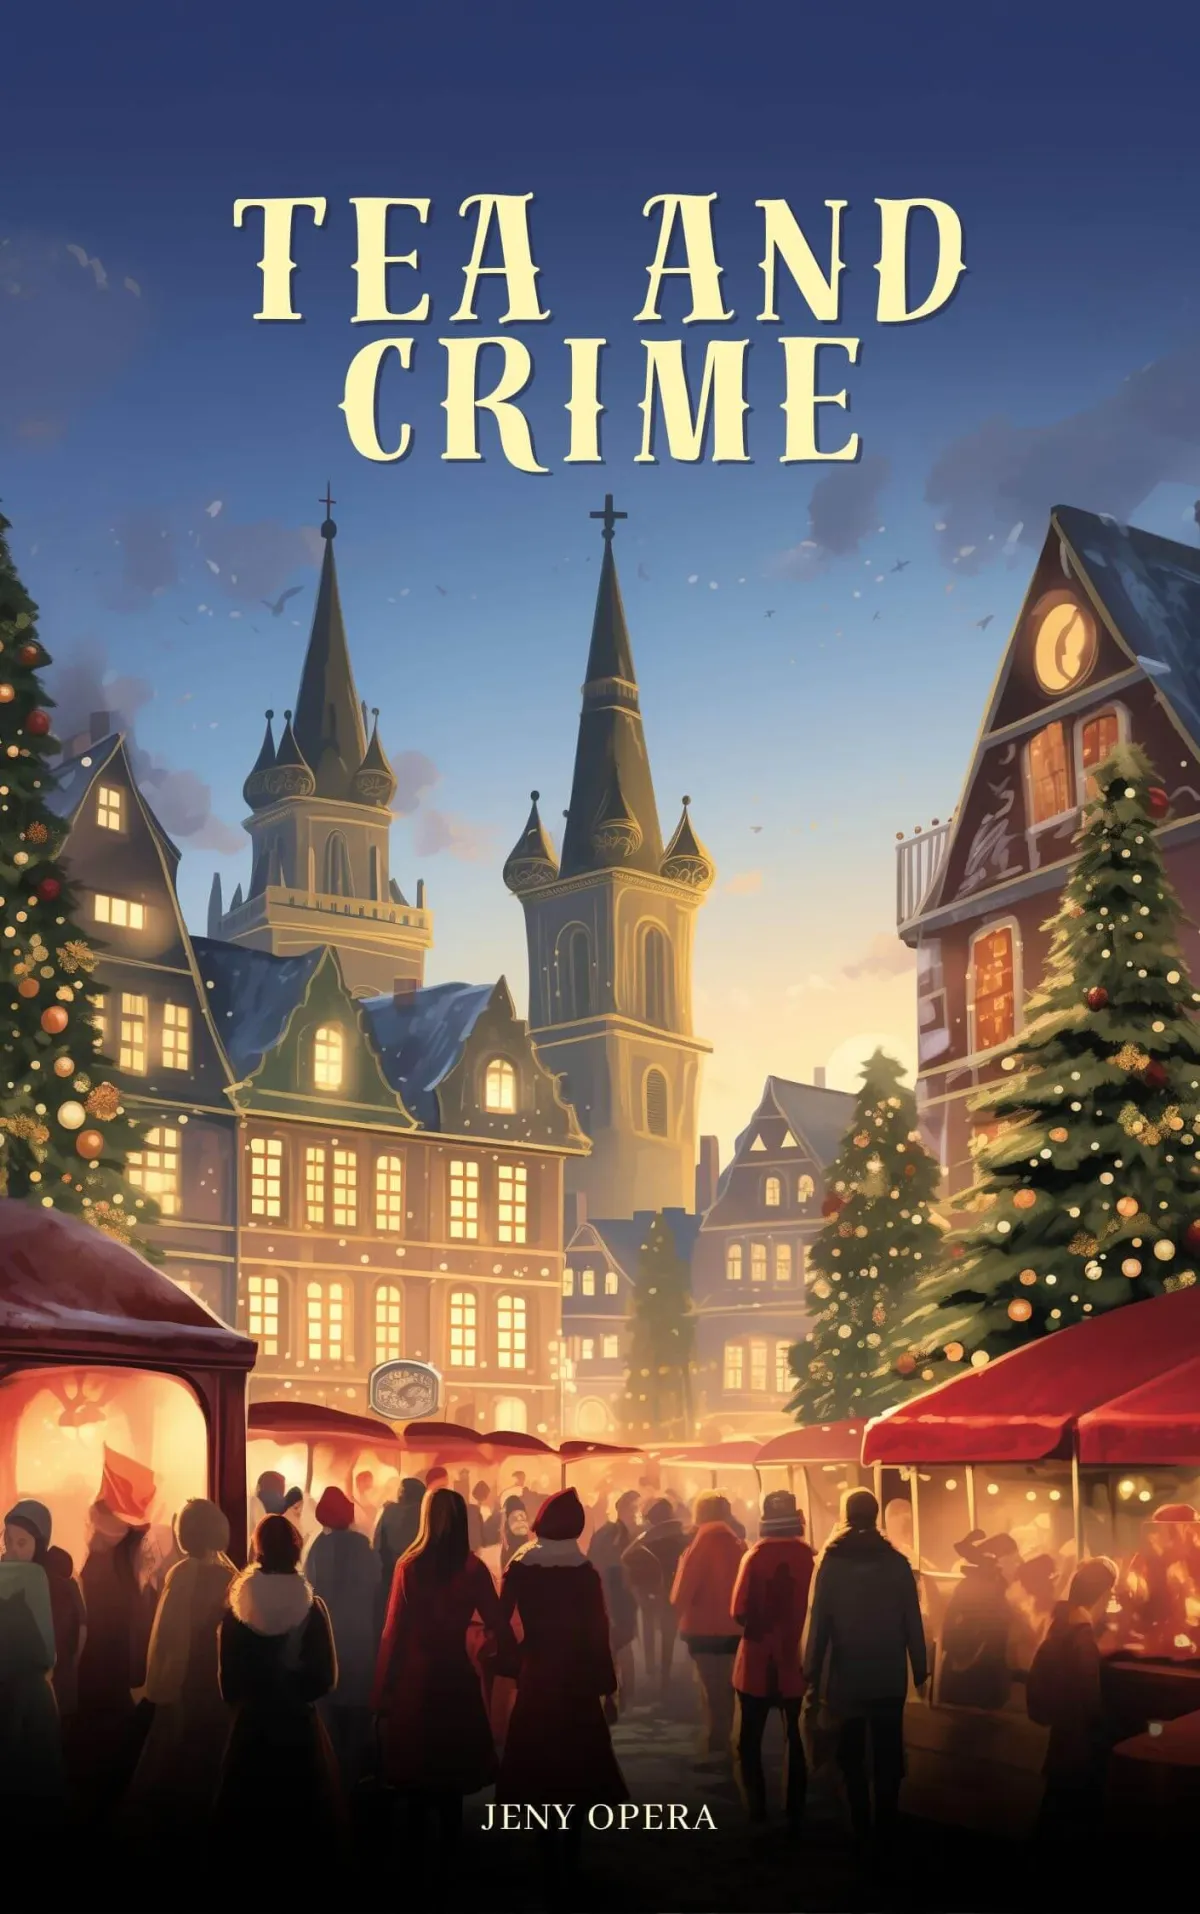
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
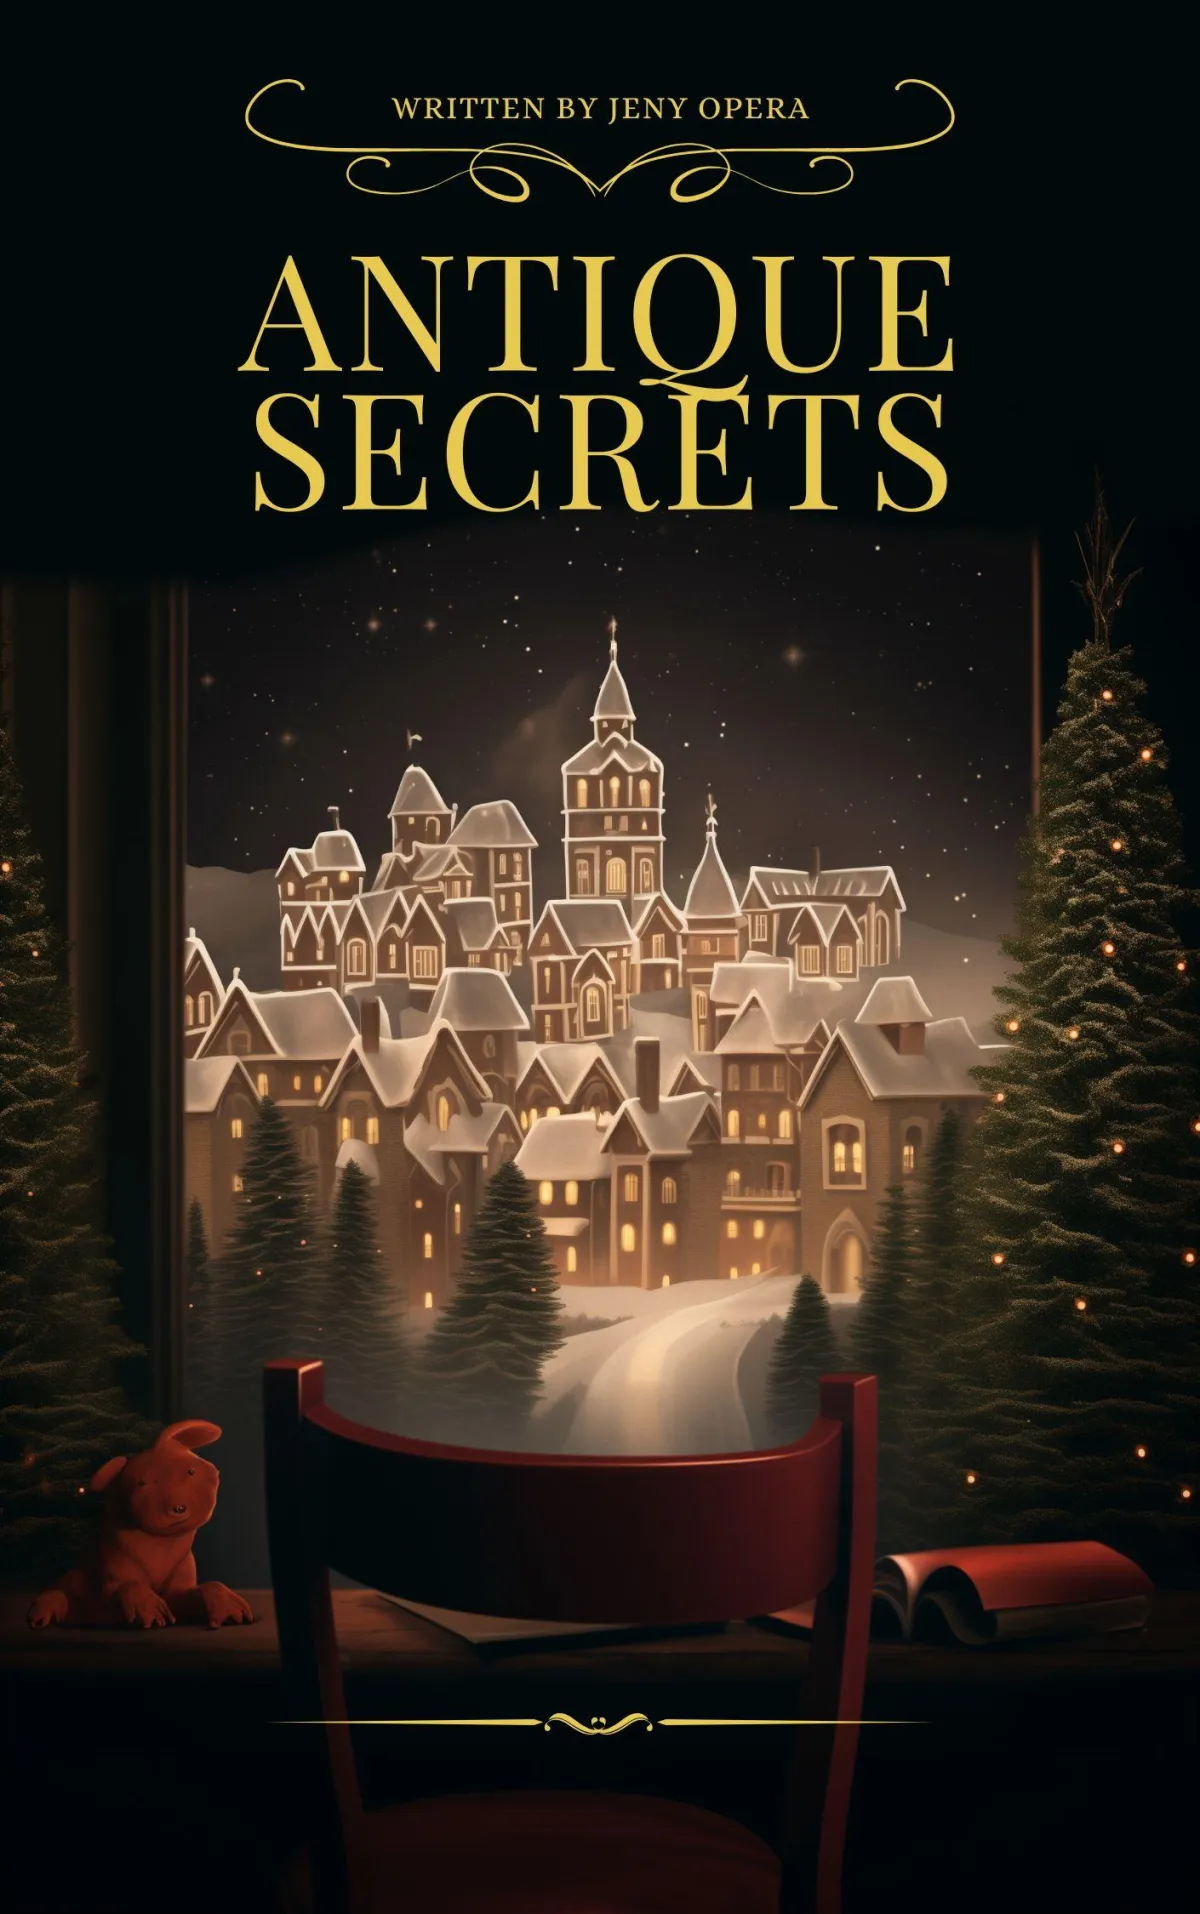
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!
"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
Subscribe to Our Newsletter
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.