📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


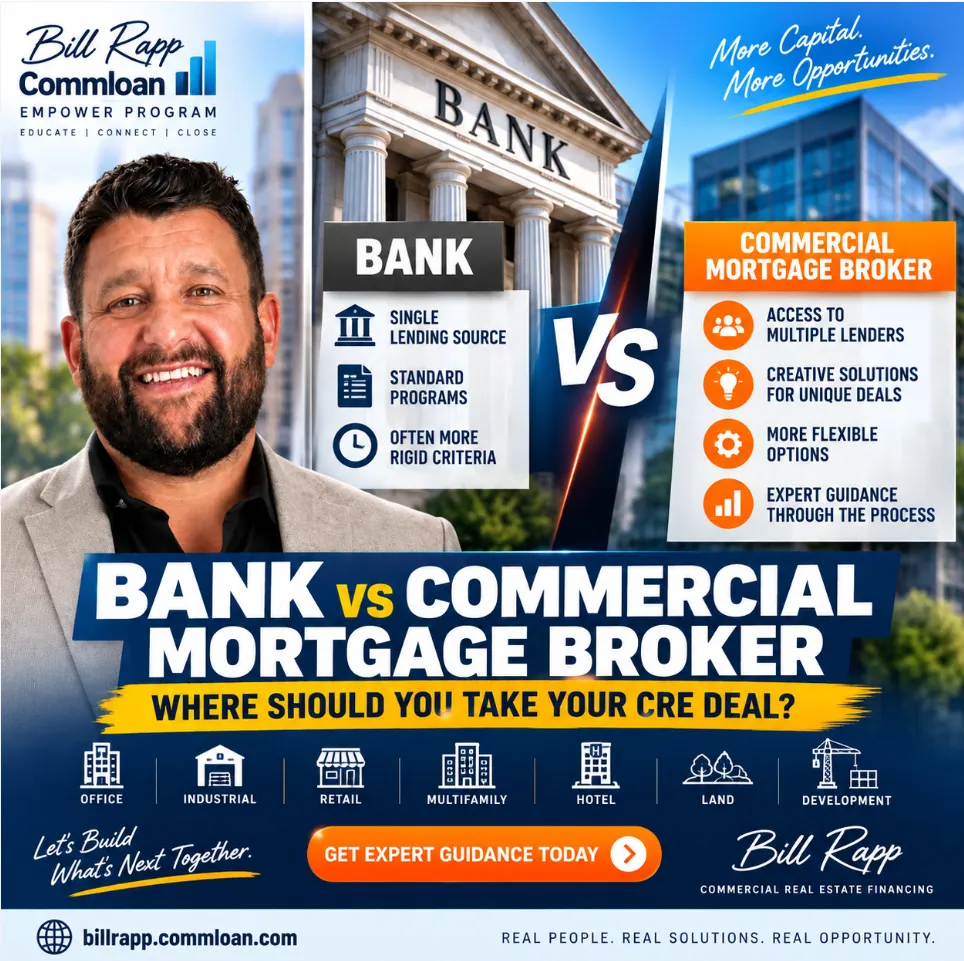
🏦 Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal? 🏢
🏦 Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal? 🏢
💰 Commercial Real Estate Financing: Bank Loan or Commercial Mortgage Broker? 🔑
________________________________________________________________________________
Bank vs. Commercial Mortgage Broker: Where Should You Take Your CRE Deal?
When you need commercial real estate financing, one of the first decisions is where to take the deal.
Do you walk into your existing bank and apply for a commercial real estate loan?
Or do you work with a commercial mortgage broker who can evaluate the transaction and seek financing from multiple potential capital sources?
There is no universal answer. Banks and commercial mortgage brokers serve different functions, and the right approach depends on the property, borrower, transaction structure, timing, leverage, cash flow, and overall financing objective.
The key is understanding the difference before you commit to a financing strategy.
What Happens When You Take a CRE Deal Directly to a Bank?
A bank evaluates your commercial real estate transaction against its own lending criteria.
That can include:
·Property type
·Loan size
·Loan-to-value ratio (LTV)
·Debt service coverage ratio (DSCR)
·Borrower liquidity
·Net worth
·Credit history
·Guarantor strength
·Geographic footprint
·Deposit relationship
·Industry concentration
·Loan concentration
·Amortization and maturity requirements
If your transaction fits the bank's credit box, a direct bank relationship can work very well.
This can be especially true when you already have a strong banking relationship, the property and borrower fit conventional underwriting standards, and the bank is actively lending on that particular type of transaction.
But there is an important distinction:
A bank can generally offer you the financing solutions available from that bank.
That is different from evaluating the deal across a broader commercial lending market.
What Does a Commercial Mortgage Broker Do?
A commercial mortgage broker or capital advisor approaches the transaction from a different direction.
Rather than asking:
"Does this deal fit our bank?"
The question becomes:
"What type of lender and financing structure best fits this transaction?"
Depending on the deal, potential capital sources can include:
·Banks
·Credit unions
·SBA lenders
·Agency lenders
·CMBS lenders
·Debt funds
·Bridge lenders
·Life insurance companies
·Private lenders
·Specialty finance companies
·Other commercial real estate capital sources
That broader perspective can become particularly valuable when a transaction doesn't fit neatly inside one lender's underwriting box.
Bank vs. Commercial Mortgage Broker: The Fundamental Difference
Think about the difference this way.
A bank is a source of capital.
A commercial mortgage broker is a source of potential capital relationships and financing strategies.
That does not automatically make one approach better than the other.
A strong local bank may provide exactly the financing you need.
But when the transaction is complicated—or when you want to understand alternatives—a commercial mortgage broker can help determine which lenders may be appropriate for the opportunity.
When Going Directly to a Bank Can Make Sense
A direct bank relationship can be attractive when you have a relatively straightforward transaction.
For example, imagine a business owner purchasing the building their company has occupied for several years.
The business has strong historical cash flow, the borrower has excellent liquidity and credit, leverage is conservative, and the borrower already has a substantial relationship with a local bank.
That may be an excellent bank transaction.
Existing relationships can matter in commercial lending. A bank that understands your business, financial history, deposits, and management team may be comfortable underwriting a transaction that fits its credit standards.
When a Commercial Mortgage Broker Can Add Value
Now consider a different transaction.
An investor is purchasing a property with:
·Significant vacancy
·Near-term lease rollover
·Planned renovations
·An aggressive closing deadline
·Transitional cash flow
·A request for higher leverage
One bank might decline the transaction because of occupancy.
Another lender might consider it but reduce proceeds because of DSCR.
A bridge lender might evaluate the transaction based on the stabilization strategy.
Another institution might have an attractive program but require different reserves or sponsorship strength.
This is where commercial mortgage brokerage and capital advisory can become particularly useful.
The problem isn't necessarily that the transaction cannot be financed.
The challenge may be identifying the right capital source for the transaction.
Commercial Real Estate Financing Is More Than Finding the Lowest Rate
Borrowers naturally focus on interest rates.
Rates matter.
But the lowest advertised rate does not automatically produce the best financing structure for a particular transaction.
Commercial borrowers should also evaluate:
Loan proceeds. How much will the lender actually advance?
Amortization. Is the loan amortized over 20, 25, or 30 years?
Maturity. Is the loan due in five, seven, or ten years?
Recourse. Will personal guarantees be required?
Prepayment provisions. Is there a declining prepayment penalty, yield maintenance, defeasance, or another restriction?
Reserves. Will the lender require replacement, tax, insurance, tenant improvement, or leasing commission reserves?
Covenants. What ongoing financial requirements will apply?
Closing timeline. Can the lender realistically meet the transaction deadline?
A slightly lower interest rate can lose much of its appeal if the structure doesn't accomplish the borrower's actual objective.
Why Lender Fit Matters
Commercial lenders do not evaluate every property type equally.
A lender that aggressively finances stabilized multifamily properties may have little appetite for hotels.
A bank comfortable with owner-occupied industrial buildings may not want a partially vacant retail center.
A lender interested in $2 million loans may have little interest in a $20 million request—and vice versa.
Lending appetite can also change.
Banks manage concentrations. Capital markets move. Credit policies change. Property types move in and out of favor.
That means a lender that financed your last transaction may not necessarily be the right lender for your next one.
The Three Numbers That Can Limit Your Loan
Commercial real estate investors should understand three particularly important underwriting metrics:
Loan-to-Value Ratio
LTV = Loan Amount ÷ Property Value
A lender offering 75% LTV does not necessarily mean you will receive 75% financing.
Debt Service Coverage Ratio
DSCR = Net Operating Income ÷ Annual Debt Service
Even when the property's value supports the requested loan, cash flow must generally support the associated debt service under the lender's underwriting requirements.
Debt Yield
Debt Yield = Net Operating Income ÷ Loan Amount
Debt yield allows lenders to evaluate property income relative to loan exposure without relying directly on interest rate or amortization.
Depending on the lender and transaction, one of these tests may become the binding constraint on proceeds.
That is why asking "What's your maximum LTV?" is often only the beginning of the financing discussion.
Should You Shop Your CRE Loan Yourself?
You certainly can.
But commercial financing isn't always comparable to requesting three identical mortgage quotes.
Different lenders may underwrite NOI differently, offer different amortization periods, require different reserves, calculate DSCR differently, or have completely different appetites for the same property.
Submitting a transaction indiscriminately to numerous lenders can also create unnecessary confusion.
Effective commercial mortgage brokerage isn't simply sending a loan request everywhere.
It is matching the transaction to lenders whose programs and credit criteria make sense for the deal.
What Information Should You Prepare?
Whether you approach a bank directly or work with a commercial mortgage broker, preparation matters.
For an investment property, lenders commonly want information such as:
·Purchase contract or loan statement
·Current rent roll
·Historical operating statements
·Property financial projections when applicable
·Personal financial statement
·Schedule of real estate owned
·Borrower liquidity information
·Organizational documents
·Property information
·Sponsor experience
For owner-occupied properties, underwriting may also require:
·Business tax returns
·Interim profit-and-loss statements
·Balance sheets
·Business debt schedules
·Ownership information
·Business projections when applicable
The cleaner the financing package, the easier it becomes to identify potential problems before they threaten the transaction.
Financing Should Start Before the Purchase Contract
One of the biggest mistakes commercial buyers make is treating financing as an afterthought.
A property may appear affordable based on purchase price alone.
But lender requirements for DSCR, LTV, liquidity, reserves, debt yield, guarantor strength, and property condition can materially affect how much capital is available.
Understanding those constraints before making an offer can improve your negotiating position and reduce the chance of discovering a financing gap after going under contract.
Bank or Commercial Mortgage Broker?
The better question may be:
How straightforward is the transaction, and how much of the commercial lending market do you need to evaluate?
A strong bank relationship can be extremely valuable.
A commercial mortgage broker can be valuable when you need broader lender access, help evaluating structures, a solution for a more complicated transaction, or assistance navigating the commercial financing process.
And these approaches aren't necessarily mutually exclusive.
A qualified capital advisor may ultimately determine that a bank is the appropriate destination for your transaction.
The objective isn't to avoid banks.
The objective is to get the right CRE deal in front of the right capital source.
Start With the Deal, Not the Lender
Before deciding where to take your next commercial real estate transaction, start with the fundamentals:
What are you buying or refinancing?
How much financing do you need?
What does the property's cash flow support?
How much equity and liquidity do you have?
What is your timeline?
What are you ultimately trying to accomplish?
Once those questions are answered, you can build the financing strategy around the transaction instead of trying to force the transaction into a predetermined lending box.
I'm Bill Rapp with the CommLoan Empower Program. If you're buying, refinancing, or repositioning commercial real estate, let's evaluate the deal and determine what financing strategy may fit the opportunity.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Subscribe to Our Newsletter
New Released

Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!

"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.