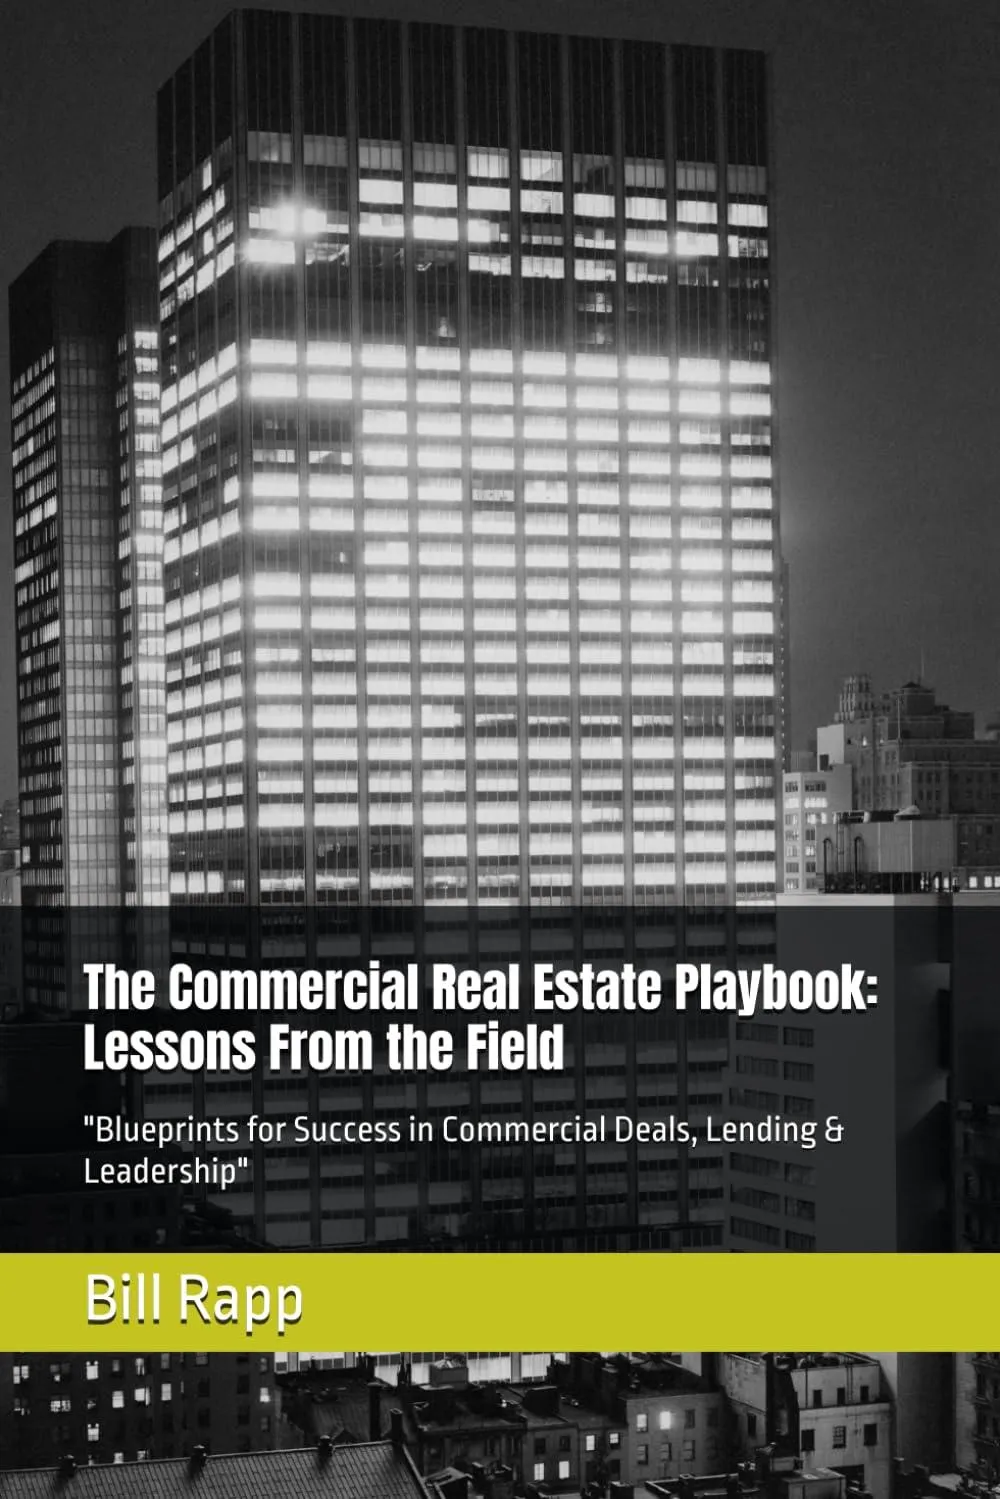
📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
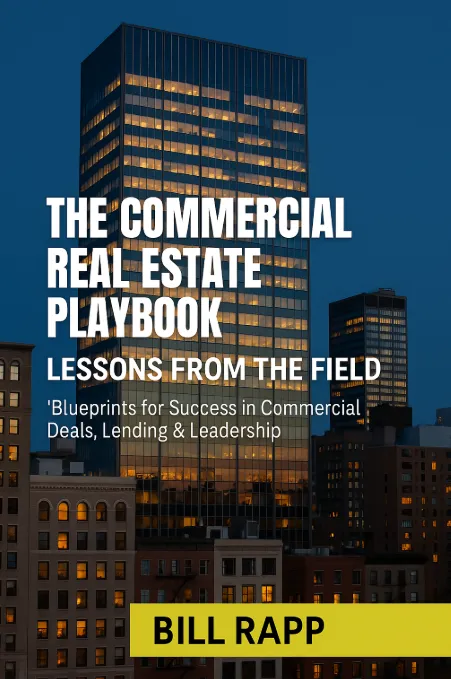
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


💰 Commercial Loan Balloon Payments: What Investors Must Know 🚨
💰 Commercial Loan Balloon Payments: What Investors Must Know 🚨
🚨 Commercial Loan Balloon Payment: Avoid a Costly Surprise 💸
________________________________________________________________________________
Commercial Loan Balloon Payments: What Investors Must Know
The $2 Million Payment You Didn't See Coming
Imagine owning a successful commercial property. Your tenants are paying rent, your cash flow is positive, and you've never missed a mortgage payment.
Then your lender sends a notice: Your $2 million balloon payment is due in six months.
You thought you had a 25-year mortgage. What you actually had was a commercial loan with a five-year term and a 25-year amortization schedule.
That distinction could determine whether you keep your investment, refinance under pressure, or are forced to sell.
Understanding how a commercial loan balloon payment works is essential for commercial real estate investors and business owners.
In this guide, we'll explain balloon payments, why commercial lenders use them, how to calculate your exposure, and five strategies to protect your investment.
What Is a Commercial Loan Balloon Payment?
A commercial loan balloon payment is the remaining principal balance that becomes due when a commercial mortgage reaches its contractual maturity date.
Unlike a fully amortizing residential mortgage, many commercial real estate loans have a shorter loan term than their amortization period.
For example, a commercial mortgage might feature:
Loan amount: $3,000,000
Interest rate: 7.00%
Loan term: 5 years
Amortization: 25 years
Monthly principal and interest: Approximately $21,203
Remaining balance after 60 payments: Approximately $2,737,000
That remaining $2.74 million becomes due at maturity, even though the borrower has made every scheduled monthly payment.
The borrower must generally repay the balance through refinancing, a property sale, available cash, or another lender-approved arrangement.
Commercial Loan Term vs. Amortization: What's the Difference?
Two numbers determine how your commercial mortgage behaves.
Loan term is the period until the loan matures and the remaining balance must be repaid. A five-year term means the loan becomes due in five years.
Amortization period is the schedule used to calculate monthly principal and interest payments. A 25-year amortization spreads the scheduled principal repayment across 300 months.
A five-year term with 25-year amortization means your payments are calculated as though you had 25 years to repay the debt, but the outstanding balance becomes due after five years.
Not every commercial mortgage has a balloon payment. Some loans fully amortize over their contractual terms, while others use interest-only structures or different repayment provisions.
The key is to understand your actual maturity date, not simply your monthly payment.
Why Do Commercial Lenders Use Balloon Payments?
Commercial lenders use shorter maturities for several reasons.
1. Interest Rate Risk
A shorter loan term allows lenders to reprice or restructure financing as market interest rates change.
2. Property Performance
Commercial property values depend heavily on income, occupancy, expenses, and market capitalization rates. Shorter maturities give lenders opportunities to reassess collateral performance.
3. Borrower Credit Risk
Lenders may want to reevaluate the borrower's financial condition, liquidity, and repayment capacity periodically.
4. Capital Management
Commercial banks and other lenders manage funding costs, liquidity, portfolio concentrations, and regulatory requirements.
A balloon structure is not inherently bad. It can offer attractive financing flexibility when the borrower has a realistic exit strategy.
The problem arises when investors assume they will automatically qualify for another loan.
The Biggest Risks of a Commercial Mortgage Balloon Payment
Refinancing Risk
A commercial property that qualified for financing five years ago may not qualify today.
Lenders may impose stricter loan-to-value limits, higher debt service coverage requirements, or more conservative underwriting assumptions.
Interest Rate Risk
If your original commercial loan carried a 5.5% interest rate and today's available financing is substantially higher, your new monthly payment could increase.
That can reduce cash flow or prevent the property from meeting a lender's required debt service coverage ratio.
Property Valuation Risk
Commercial property values can decline even when the property remains profitable.
For example:
Net operating income: $300,000
Value at a 6% cap rate: $5,000,000
Value at a 7.5% cap rate: $4,000,000
That's a $1 million decline in estimated value without any change in net operating income.
If the lender's maximum LTV is 65%, the $4 million valuation supports only $2.6 million in financing before other underwriting constraints.
Cash Flow and DSCR Risk
Debt service coverage ratio, or DSCR, measures a property's ability to cover its debt payments.
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose a commercial property generates $300,000 in annual NOI and its proposed annual debt service is $250,000.
The DSCR is 1.20.
If the lender requires 1.25, the property falls short—even if its LTV is acceptable.
Maturity Default Risk
Failure to repay the balloon payment by the contractual maturity date can constitute a loan default.
Depending on the loan documents, consequences may include default interest, additional fees, enforcement remedies, or foreclosure.
An extension is not guaranteed unless the documents provide an enforceable extension right and its conditions are satisfied.
Real-World Example: The $2 Million Balloon Payment
Consider a hypothetical investor who purchases a neighborhood retail center.
Original financing:
Purchase price: $3,500,000
Initial loan: $2,450,000
Interest rate: 6.50%
Amortization: 25 years
Loan term: 5 years
Monthly principal and interest: Approximately $16,543
After five years, the loan has an outstanding balance of approximately $2.19 million.
The investor has made every payment on time.
However, the property now faces two challenges.
First, higher market capitalization rates have reduced the property's estimated value to $3.1 million.
Second, the lender will only offer a 65% LTV refinance.
Maximum loan based on value:
$3,100,000 × 65% = $2,015,000
Estimated refinancing shortfall:
$2,190,000 − $2,015,000 = $175,000
The investor must find approximately $175,000, plus applicable closing costs, reserves, and fees, to complete the refinance—assuming the property also satisfies DSCR and other underwriting requirements.
This is called a refinancing equity gap.
The property may still be profitable, but the borrower needs additional capital to satisfy the balloon payment.
Five Strategies to Avoid a Commercial Loan Balloon Payment Surprise
Strategy 1: Start Planning 12–18 Months Before Maturity
Review your existing loan documents and establish a refinancing timeline.
Identify your maturity date, expected balloon balance, prepayment provisions, extension options, and lender notification requirements.
Do not wait until your lender sends a maturity notice.
Strategy 2: Evaluate Multiple Commercial Lending Options
Different lenders evaluate commercial properties differently.
Potential capital sources include:
Commercial banks and credit unions
Life insurance company lenders
Agency multifamily lenders, where eligible
SBA lenders for qualifying owner-occupied businesses
Debt funds and private lenders
Bridge lenders for transitional properties
Each option has different requirements for DSCR, LTV, occupancy, property condition, recourse, and pricing.
The best lender is not always the one offering the lowest advertised interest rate.
Strategy 3: Stress-Test Your Property's Financial Performance
Evaluate your refinance using several interest rate and valuation assumptions.
Ask:
What happens if interest rates are one percentage point higher?
What happens if NOI falls 10%?
What happens if the property's appraised value declines 15%?
How much additional equity would be required?
Stress testing identifies potential problems before they become emergencies.
Strategy 4: Improve NOI and Strengthen Your Refinance Position
Commercial lenders evaluate sustainable income.
Improving occupancy, collecting delinquent rent, renewing leases, controlling operating expenses, and addressing deferred maintenance may strengthen your financing position.
For income-producing properties, stronger NOI can improve DSCR and potentially support a higher valuation.
However, lenders may exclude temporary income or apply their own underwriting adjustments.
Strategy 5: Establish a Backup Exit Strategy
Your primary strategy may be refinancing, but you should also consider alternatives.
These could include negotiating an extension, contributing additional equity, selling the property, obtaining transitional financing, or restructuring the capital stack.
Bridge financing can provide time in appropriate circumstances, but higher financing costs, fees, shorter maturities, and additional refinance risk must be evaluated carefully.
Can You Refinance a Commercial Loan Before the Balloon Payment Is Due?
Yes. Commercial loans can often be refinanced before maturity, subject to existing loan provisions and new lender approval.
However, some loans include prepayment penalties, yield maintenance, defeasance, or other restrictions.
These costs can materially affect the economics of refinancing early.
Before choosing a refinance date, compare the existing loan's payoff requirements with the expected benefits and costs of the replacement financing.
How CommLoan Helps Investors Prepare for Balloon Payments
Commercial real estate financing is not one-size-fits-all.
At CommLoan, we use our CUPID™ commercial lending marketplace to evaluate financing scenarios and identify lender programs aligned with the borrower's property, financial profile, and objectives.
Instead of approaching commercial banks one by one, investors can explore potential financing structures through a coordinated process.
As Director with CommLoan, I help borrowers understand their financing options, assess potential refinancing constraints, and prepare for important capital decisions.
The goal is to address financing challenges before the maturity date becomes a crisis.
Frequently Asked Questions About Commercial Loan Balloon Payments
What happens when a commercial loan balloon payment is due?
The remaining loan balance must be repaid according to the loan documents. Borrowers may refinance, sell the property, pay with available funds, or pursue a lender-approved extension or restructuring.
Are balloon payments common in commercial real estate?
Yes. Balloon payments are common in commercial bank mortgages and certain other commercial financing structures, although not all commercial loans require them.
Can I extend my commercial loan balloon payment?
Possibly. Some loans include extension options, while other extensions require the lender's approval. Terms may involve fees, updated financial statements, new underwriting, or principal reductions.
Can a commercial loan balloon payment be refinanced?
Yes, if the borrower and property qualify under the replacement lender's requirements. Approval depends on factors such as NOI, DSCR, LTV, credit, liquidity, property condition, and market conditions.
What if I cannot afford the balloon payment?
Contact your lender promptly and evaluate refinancing, extension, equity contribution, sale, or restructuring alternatives. Seek qualified legal advice if default is possible.
Final Thoughts: Know Your Maturity Date Before It Becomes a Problem
A commercial loan balloon payment does not have to derail a profitable investment.
But ignoring your maturity date can create unnecessary financial pressure.
Successful commercial real estate investors understand their loan terms, monitor their debt maturities, and develop refinancing strategies well in advance.
Don't let a $2 million balloon payment become a $2 million surprise.
Ready to Review Your Commercial Loan?
I'm Bill Rapp, CCIM, Director with CommLoan.
If you own commercial real estate and have a loan approaching maturity, let's evaluate your financing options before the deadline arrives.
Explore commercial financing: https://billrapp.commloan.com/
Call: 281-222-0433
Educational information only. Financing availability, underwriting, rates, terms, and approval depend on the lender, borrower, property, and market conditions. Examples are hypothetical and rounded.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Subscribe to Our Newsletter
New Released

Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!

"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.