📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
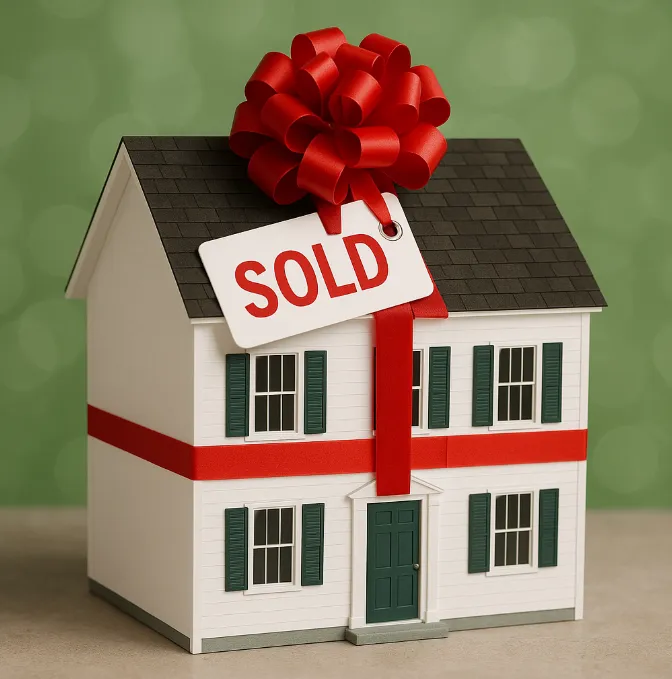
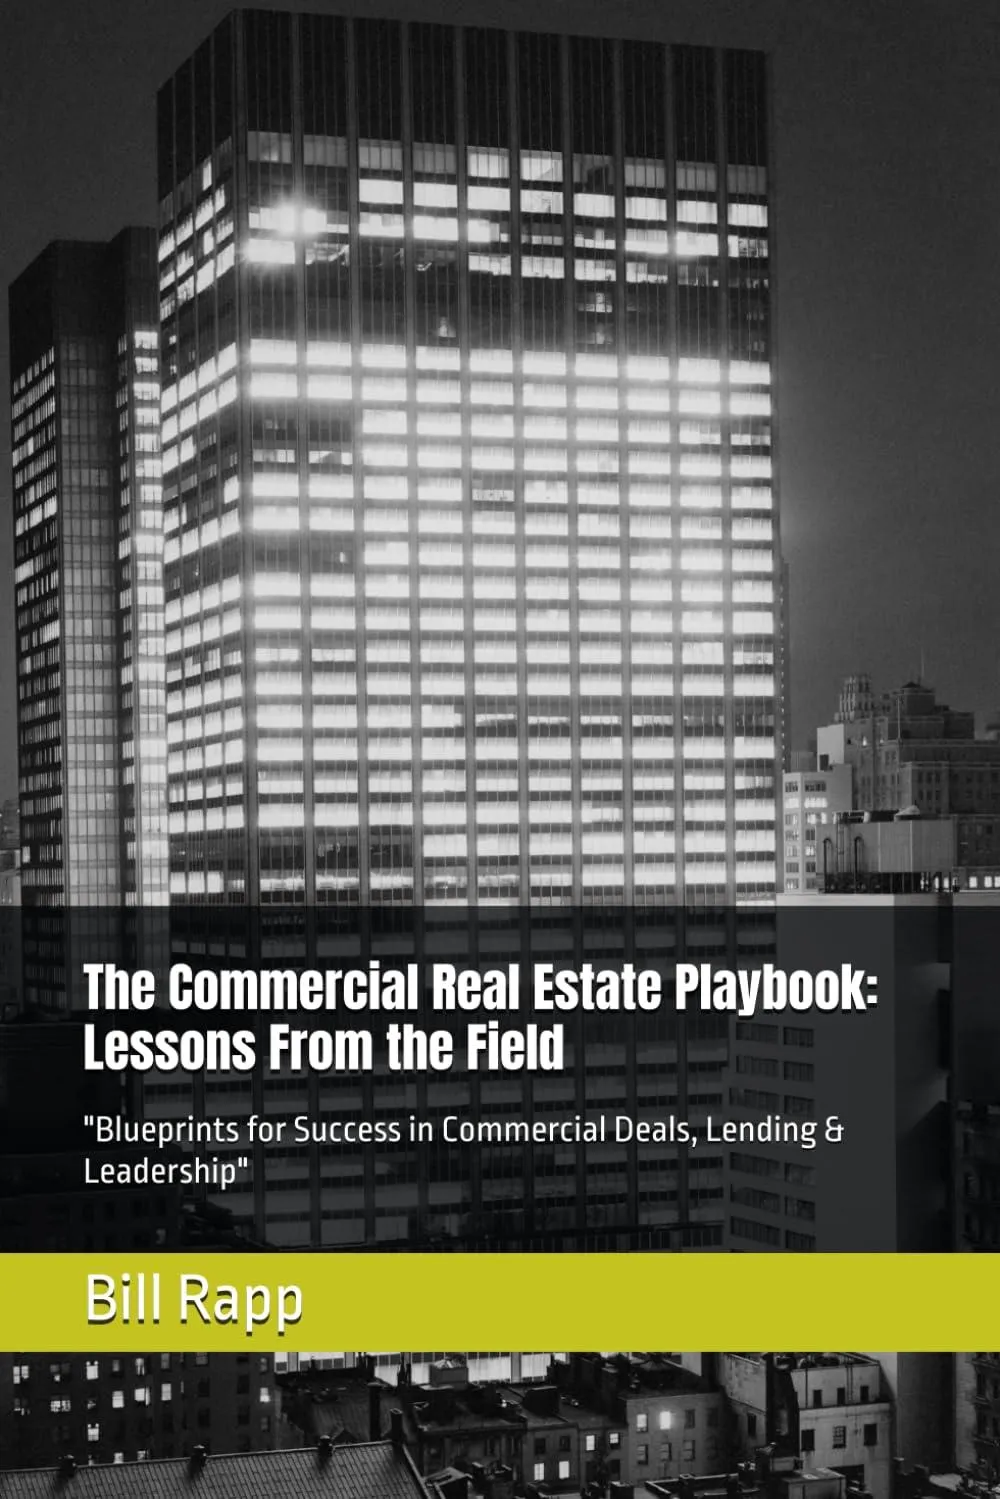
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


💰 Commercial Real Estate Loan Rates Explained 🏦
💰 Commercial Real Estate Loan Rates Explained 🏦
📈 How Banks Price Commercial Mortgage Rates 💵
_______________________________________________________________________________
What Are Current Commercial Real Estate Loan Rates? Understanding Indexes, Credit Spreads and Loan Pricing
By Bill Rapp, CCIM | CommLoan
Commercial real estate investors frequently ask one important question:
What are current commercial real estate loan rates?
The answer is more complicated than simply checking the latest Federal Reserve announcement or searching online for today's mortgage rates.
Unlike residential mortgages, commercial real estate loans are often individually priced based on the property, borrower, loan structure, financial markets and lender's appetite for risk.
Two investors purchasing similar commercial properties could receive substantially different interest rates—even when applying for financing on the same day.
Understanding how commercial mortgage rates are calculated can help investors negotiate more effectively, evaluate financing alternatives and make better investment decisions.
How Are Commercial Real Estate Loan Rates Determined?
Most commercial mortgage pricing begins with two fundamental components:
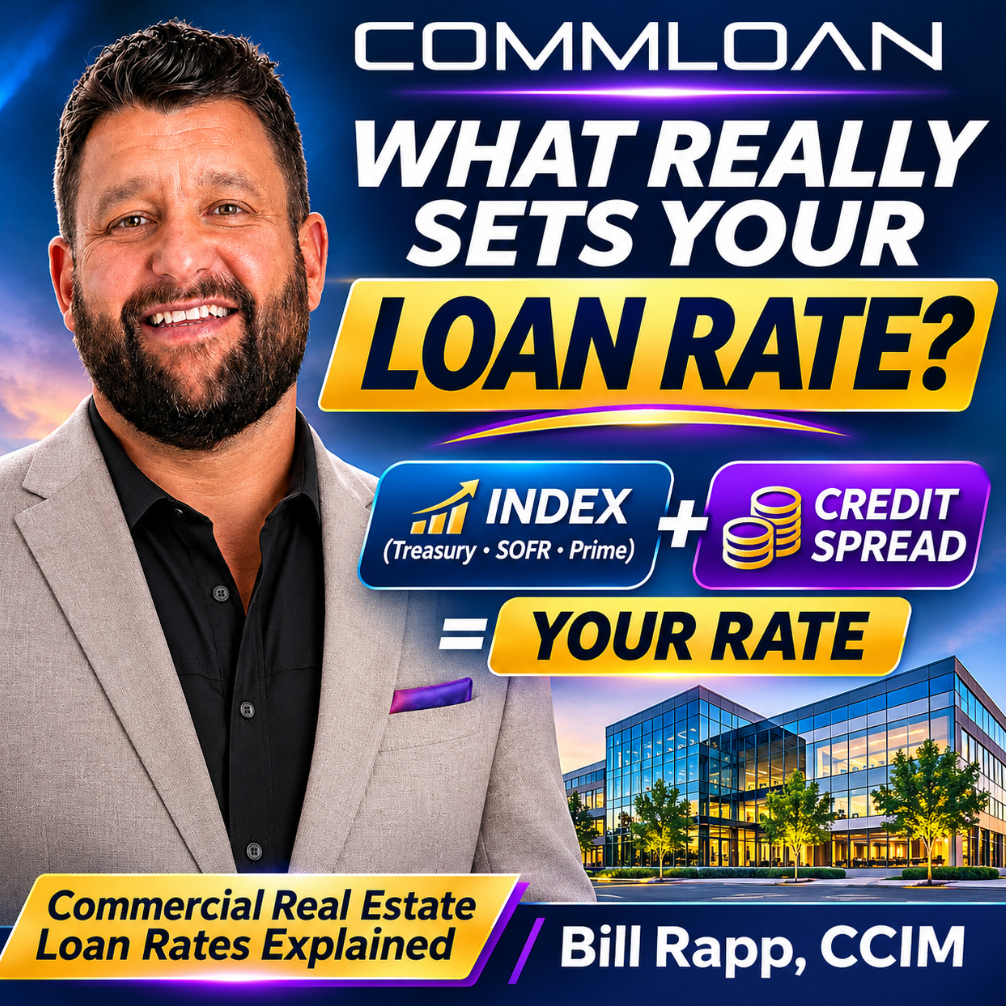
Commercial Loan Interest Rate = Benchmark Index + Credit Spread
The benchmark index represents a market-based reference rate, while the credit spread reflects the lender's pricing for the specific transaction, including credit risk, funding economics, operating costs and required return.
For example, assume a commercial lender prices a loan using the following structure:
Benchmark index: 4.00%
Credit spread: 2.50%
Total interest rate: 6.50%
If the benchmark increases to 4.50% and the spread remains unchanged, the indicated interest rate increases to 7.00%.
However, if the benchmark remains at 4.00% and the lender increases its spread to 3.00%, the interest rate also becomes 7.00%.
This distinction is important because commercial mortgage rates can change even when the Federal Reserve does not change its benchmark policy rate.
The rates used throughout this article are hypothetical examples for educational purposes, not current lender quotes.
What Are the Main Commercial Mortgage Rate Indexes?
Commercial real estate lenders use several benchmark indexes to establish loan pricing. The appropriate index depends on the lender, loan program, fixed-rate period and financing structure.
1. U.S. Treasury Yields
U.S. Treasury yields are among the most important benchmarks in commercial real estate finance.
Common benchmarks include:
Five-year Treasury yield
Seven-year Treasury yield
Ten-year Treasury yield
Banks, insurance companies, CMBS lenders and other capital providers may use Treasury yields when pricing fixed-rate commercial mortgages.
For example, a lender offering a five-year fixed-rate commercial mortgage might price the loan at the five-year Treasury yield plus a predetermined spread.
If the five-year Treasury yield is 4.00% and the lender's spread is 225 basis points, the resulting interest rate would be 6.25%.
Treasury yields fluctuate based on inflation expectations, economic growth, monetary policy expectations and investor demand for government securities.
2. SOFR — Secured Overnight Financing Rate
SOFR stands for Secured Overnight Financing Rate.
It measures the cost of overnight borrowing secured by U.S. Treasury securities in the repurchase agreement market.
SOFR has become a major benchmark for floating-rate commercial real estate loans, particularly:
Bridge loans
Construction loans
Transitional property financing
Floating-rate commercial mortgages
Institutional real estate financing
A floating-rate loan might be priced at one-month Term SOFR plus 350 basis points.
If the applicable SOFR benchmark is 4.00%, the initial interest rate would be 7.50%.
If SOFR subsequently increases to 5.00%, the interest rate could increase to 8.50%, subject to the loan's reset provisions, floors and any applicable interest rate protection.
Borrowers should understand whether their loan uses overnight SOFR, compounded SOFR or forward-looking Term SOFR because the calculation and reset mechanics can differ.
3. Prime Rate
The prime rate is another common commercial lending benchmark, particularly for certain bank loans, business financing and SBA loan programs.
The prime rate generally moves in response to changes in the federal funds target range, although it is established by banks rather than directly by the Federal Reserve.
A lender might offer financing at:
Prime Rate + 1.00%
If prime is 7.00%, the resulting interest rate would be 8.00%.
Prime-based pricing is particularly relevant to many variable-rate SBA 7(a) loans, subject to applicable SBA interest rate limits.
4. Interest Rate Swap Benchmarks
Interest rate swap rates can also influence commercial mortgage pricing.
Some institutional lenders use swap benchmarks to establish fixed-rate pricing or hedge floating-rate exposure.
Swap rates reflect market expectations for future interest rates and the economics of exchanging fixed and floating interest payments.
A commercial borrower may encounter a loan priced using a five-year swap rate plus a credit spread, particularly when dealing with institutional lenders or bank financing involving an interest rate hedge.
Borrowers should also understand potential swap termination costs and how those costs could affect an early refinance or property sale.
What Is a Credit Spread in Commercial Real Estate Lending?
The credit spread is the additional interest rate charged above the selected benchmark.
Commercial mortgage spreads are commonly expressed in basis points.
One basis point equals 0.01 percentage points.
For example:
100 basis points = 1.00%
200 basis points = 2.00%
250 basis points = 2.50%
350 basis points = 3.50%
A lender quoting a commercial mortgage at Treasury plus 250 basis points is adding 2.50 percentage points to the applicable Treasury yield.
Credit spreads compensate lenders for a combination of risks and economic considerations, including:
Borrower default risk
Property cash-flow volatility
Collateral quality
Loan liquidity
Capital requirements
Funding costs
Competitive market conditions
Expected profitability
A lower-risk commercial real estate investment may qualify for a narrower credit spread, while a higher-risk transaction may require a wider spread.
What Factors Determine Your Commercial Mortgage Credit Spread?
Loan-to-Value Ratio
Loan-to-value, or LTV, measures the loan amount relative to the property's value.
A $3 million loan secured by a $5 million property represents a 60% LTV.
A lender may view this transaction as less risky than a loan representing 80% of the property's value because the borrower has more equity invested and the lender has a larger collateral cushion.
Lower leverage can sometimes result in more favorable loan pricing.
Debt Service Coverage Ratio
Debt service coverage ratio, or DSCR, measures the property's ability to cover its debt payments.
DSCR = Net Operating Income ÷ Annual Debt Service
If a commercial property generates $300,000 in annual net operating income and annual debt service is $240,000, the DSCR is 1.25.
This means the property generates 25% more operating income than its scheduled debt payments.
A stronger DSCR can improve lender confidence and potentially support better loan terms.
Debt Yield
Debt yield measures the property's net operating income relative to the loan amount.
Debt Yield = Net Operating Income ÷ Loan Amount
If a property generates $300,000 in annual NOI and the requested loan is $3 million, the debt yield is 10%.
Lenders use debt yield to evaluate the relationship between property income and loan exposure independently of the interest rate or amortization schedule.
A stronger debt yield may improve the overall credit profile of a transaction.
Property Type and Tenant Quality
Commercial mortgage rates can vary significantly by property type.
A stabilized industrial warehouse leased to a financially strong tenant may receive different pricing than a partially vacant office building or a hotel undergoing renovations.
Lenders evaluate factors such as:
Occupancy
Tenant creditworthiness
Lease expiration schedules
Property condition
Location and market fundamentals
Historical operating performance
Re-leasing risk
A property with stable, predictable income may qualify for more competitive pricing than a property with substantial operating uncertainty.
Borrower Financial Strength
Lenders also evaluate the borrower or sponsoring ownership group.
Important considerations include liquidity, net worth, commercial real estate experience, credit history, contingent liabilities and the ability to support the property during periods of financial stress.
Strong sponsorship can improve financing options, although it does not necessarily overcome weak property-level fundamentals.
How Commercial Loan Rates Vary by Financing Program
Different commercial real estate financing programs use different pricing methodologies.
Loan Program | Common Pricing Methodology |
Conventional bank loan | Treasury, swap, prime or internal funding benchmark plus a spread |
Credit union loan | Internal pricing models or market benchmark plus a spread |
SBA 7(a) loan | Prime or another permitted benchmark plus an allowable spread |
SBA 504 loan | Bank first mortgage plus a separately priced CDC debenture |
CMBS loan | Treasury or swap benchmark plus a spread |
Life insurance company loan | Treasury or other capital-market benchmark plus a spread |
Agency multifamily loan | Capital-market benchmark plus program-specific pricing |
Bridge loan | SOFR plus a spread or a fixed private-lender rate |
Construction loan | Frequently a floating benchmark plus a spread |
The best financing program is not necessarily the one advertising the lowest interest rate.
Investors should also evaluate loan proceeds, amortization, recourse, prepayment penalties, reserves, closing costs and execution certainty.
How Does the Federal Reserve Affect Commercial Mortgage Rates?
The Federal Reserve influences short-term interest rates through monetary policy.
However, commercial mortgage rates do not always move in the same direction or by the same amount as the federal funds rate.
Floating-rate commercial loans tied to short-term benchmarks such as SOFR or prime may respond relatively quickly to monetary policy changes.
Longer-term fixed-rate commercial mortgages are influenced more heavily by Treasury yields, swap rates and expectations for future economic conditions.
For example, the Federal Reserve could reduce its policy rate while the ten-year Treasury yield increases because investors expect higher inflation or stronger economic growth.
In that situation, some fixed-rate commercial mortgages could become more expensive despite a Federal Reserve rate cut.
This is why commercial real estate investors should monitor the relevant benchmark rather than relying exclusively on Federal Reserve announcements.
Real-World Commercial Mortgage Pricing Example
Consider an investor purchasing a stabilized industrial property for $5 million.
The investor requests a $3.5 million commercial mortgage, representing 70% LTV.
The property generates $350,000 in annual net operating income.
Two lenders provide the following hypothetical financing proposals:
Loan Terms | Lender A | Lender B |
Loan amount | $3,500,000 | $3,500,000 |
Benchmark | 4.00% | 4.00% |
Credit spread | 2.25% | 3.00% |
Interest rate | 6.25% | 7.00% |
Amortization | 25 years | 25 years |
Approx. monthly payment | $23,088 | $24,737 |
Approx. annual debt service | $277,061 | $296,847 |
DSCR | 1.26x | 1.18x |
Annual cash flow after debt service | $72,939 | $53,153 |
The difference in interest rates is only 75 basis points.
However, Lender B requires approximately $19,800 more in annual debt payments.
That difference directly affects the investor's cash flow and potentially the amount of financing the property can support.
If the lender requires a minimum 1.25 DSCR, the second proposal would not support the full requested loan amount based on these assumptions.
This illustrates why commercial mortgage pricing can determine whether an investment transaction is financially viable.
Why Commercial Mortgage Rates Are Only Part of the Equation
A lower interest rate does not automatically mean a better commercial loan.
Consider two lenders:
Lender A offers a lower rate but requires a substantial prepayment penalty, shorter amortization and full personal recourse.
Lender B offers a slightly higher rate but provides longer amortization, more flexible prepayment terms and limited recourse.
Depending on the investor's business plan, Lender B could provide the more attractive overall financing structure.
Before accepting a commercial mortgage proposal, evaluate:
Interest rate and benchmark
Credit spread and rate-lock provisions
Loan term and amortization
Loan proceeds and equity requirements
Origination fees and closing costs
Prepayment penalties
Recourse and guaranty requirements
Interest rate floors, caps and hedging costs
Financial covenants and reserve requirements
Refinance and maturity risk
The objective is to secure financing that supports your investment strategy—not simply the lowest advertised rate.
How Can Investors Find Current Commercial Real Estate Loan Rates?
Because commercial mortgage rates are transaction-specific, borrowers should obtain current financing proposals from lenders that actively finance their property type and loan size.
Start by monitoring reliable benchmark sources:
U.S. Treasury daily yield curve rates for Treasury benchmarks.
Federal Reserve Bank of New York for published SOFR data.
Federal Reserve economic data for prime rates and other interest rate indicators.
Current lender term sheets for applicable credit spreads and loan structures.
Then prepare a complete financing package that includes:
Property rent roll
Historical operating statements
Current net operating income
Purchase price or estimated property value
Requested loan amount
Borrower financial statements
Property and tenant information
Business plan and exit strategy
Providing lenders with complete information can improve the quality and accuracy of financing proposals.
How CommLoan Helps Commercial Real Estate Borrowers
Navigating the commercial mortgage market can be challenging because every lender has different underwriting requirements, property preferences and pricing models.
Through CommLoan's commercial mortgage marketplace, borrowers can explore financing opportunities across a broad network of capital providers.
Whether you are purchasing an industrial warehouse, refinancing a retail center, acquiring an apartment community or financing an owner-occupied commercial property, evaluating multiple lenders can help identify a financing structure aligned with your investment objectives.
As a commercial real estate and capital advisory professional, I help borrowers understand how loan pricing, underwriting requirements and capital structure affect the financial performance of their investments.
Frequently Asked Questions
What is a good commercial real estate loan rate?
A competitive commercial mortgage rate depends on the applicable benchmark, credit spread, property type, leverage, cash flow, loan structure and borrower qualifications. Compare current proposals for similar transactions rather than relying on a universal target rate.
Are commercial mortgage rates higher than residential mortgage rates?
Commercial mortgage rates are often higher because commercial loans involve different underwriting requirements, collateral risks, loan structures and funding sources. However, highly competitive commercial financing programs can sometimes offer favorable pricing.
Can I negotiate my commercial mortgage credit spread?
Potentially. Strong property cash flow, lower leverage, experienced sponsorship and competing lender proposals may help borrowers negotiate more favorable pricing.
Do commercial mortgage rates fall when the Fed cuts rates?
Not necessarily. Floating-rate loans may respond more directly to changes in short-term interest rates, while fixed-rate commercial mortgages depend on longer-term market benchmarks and lender spreads.
Should I choose a fixed-rate or floating-rate commercial loan?
The appropriate structure depends on your investment horizon, cash-flow stability, interest rate outlook, refinancing strategy and tolerance for payment volatility.
What is a commercial mortgage rate lock?
A rate lock establishes certain pricing terms for a specified period, subject to the lender's agreement and conditions. Some lenders lock the benchmark and spread together, while others establish the spread first and lock the benchmark closer to closing.
Final Thoughts: Understand the Formula Before You Borrow
Commercial real estate loan rates are determined by more than the Federal Reserve or the latest financial headlines.
They reflect the interaction between market benchmarks, lender credit spreads, property performance, borrower qualifications and loan structure.
Understanding these factors gives investors a significant advantage when comparing commercial mortgage proposals.
Before committing to your next acquisition or refinance, make sure you understand both the benchmark and the spread—and how the resulting loan structure affects your cash flow and investment returns.
Ready to explore commercial real estate financing options?
Connect with Bill Rapp, CCIM, through CommLoan to evaluate financing opportunities for your next commercial real estate investment.
Current Commercial Loan Rate Benchmarks
Market snapshot — November 16, 2026
This is a recommended addition to the blog immediately following the introduction. It provides current market context while keeping the remainder of the article evergreen.
5-Year Treasury
4.98%
November 13, 2026
10-Year Treasury
5.15%
November 13, 2026
Overnight SOFR
3.90%
November 12, 2026
Bank Prime Rate
7.00%
November 12, 2026
Sources: U.S. Treasury, Federal Reserve H.15 and published SOFR market data.
U.S. Department of the Treasury+2
Current Treasury Yield Curve
3.85%4.4%4.95%5.5%6.05%1 Mo3 Mo6 Mo1 Yr2 Yr3 Yr5 Yr7 Yr10 Yr20 Yr30 Yr
U.S. Treasury par yield curve, November 13, 2026.
U.S. Department of the Treasury
Illustrative Commercial Mortgage Pricing Using Current Benchmarks
Financing benchmark | Assumed spread | Illustrative rate |
5-Year Treasury: 4.98% | 200 bps | 6.98% |
5-Year Treasury: 4.98% | 250 bps | 7.48% |
10-Year Treasury: 5.15% | 175 bps | 6.90% |
10-Year Treasury: 5.15% | 250 bps | 7.65% |
Overnight SOFR: 3.90% | 350 bps | 7.40% |
Prime: 7.00% | 100 bps | 8.00% |
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Subscribe to Our Newsletter
New Released

Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!

"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.