📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


🏡 Fixed-Rate vs. Adjustable-Rate Mortgage: Which Home Loan Saves You More Money? 💰
🏡 Fixed-Rate vs. Adjustable-Rate Mortgage: Which Home Loan Saves You More Money? 💰
💵 Fixed vs. Adjustable Mortgage Rates: 7 Things Every Homebuyer Should Know Before Choosing 🏠
____________________________________________________________________________
Fixed-Rate vs. Adjustable-Rate Mortgage: Which Home Loan Saves You More Money?
When you're shopping for a mortgage, one of the most important decisions you'll make is whether to choose a fixed-rate mortgage or an adjustable-rate mortgage (ARM).
Both options can help you purchase a home, but they work differently. One offers predictable monthly principal and interest payments, while the other may offer a lower introductory interest rate in exchange for uncertainty later.
So which mortgage is better for you?
The answer depends on your financial goals, how long you expect to own the home, your budget, and your tolerance for changing interest rates.
At Medallion Funds, we help homebuyers understand their financing options so they can make informed decisions rather than simply choosing the loan with the lowest advertised rate.
Let's break down the differences.
What Is a Fixed-Rate Mortgage?
A fixed-rate mortgage is a home loan with an interest rate that remains unchanged throughout the entire loan term.
Whether you choose a 15-year, 20-year, or 30-year fixed-rate mortgage, your interest rate stays the same unless you refinance or otherwise modify the loan.
Advantages of a Fixed-Rate Mortgage
·Predictable payments: Your monthly principal and interest payment stays the same.
·Protection against rising interest rates: Market rate increases won't change your existing mortgage rate.
·Easier long-term budgeting: You know the scheduled principal and interest payment for the life of the loan.
·Long-term stability: Particularly attractive for homeowners planning to remain in their homes for many years.
Disadvantages of a Fixed-Rate Mortgage
·The initial interest rate may be higher than the introductory rate on an ARM.
·You may pay more interest during the early years compared with a lower-rate ARM.
·Taking advantage of falling market rates generally requires refinancing, which may involve closing costs and qualification requirements.
Important: Even with a fixed-rate mortgage, your total housing payment may change because of property taxes, homeowners insurance, mortgage insurance, or escrow adjustments.
What Is an Adjustable-Rate Mortgage?
An adjustable-rate mortgage, commonly called an ARM, generally begins with a fixed introductory interest rate for a specified period.
After that initial period, the interest rate can adjust periodically based on a financial index plus a lender-defined margin, subject to the loan's adjustment caps.
Common ARM structures include:
·5/1 ARM: Fixed interest rate for five years, then adjustments generally once per year.
·7/1 ARM: Fixed interest rate for seven years, then adjustments generally once per year.
·10/1 ARM: Fixed interest rate for ten years, then adjustments generally once per year.
·5/6 ARM: Fixed interest rate for five years, then adjustments generally every six months.
The first number represents the initial fixed-rate period in years. The second number indicates the adjustment frequency afterward.
For example, a 7/6 ARM generally maintains its introductory rate for seven years before becoming eligible for adjustments every six months.
Advantages of an Adjustable-Rate Mortgage
·Potentially lower introductory rates: Some ARMs offer lower initial interest rates than comparable fixed-rate loans.
·Potential early payment savings: A lower introductory rate can reduce monthly principal and interest payments.
·Flexibility for shorter ownership plans: May suit borrowers who expect to sell or relocate before the first adjustment.
·Potential benefit if rates decline: Future adjustments could reduce the interest rate, depending on the index, margin, and contractual limits.
Disadvantages of an Adjustable-Rate Mortgage
·Your interest rate and payment may increase after the introductory period.
·Future payment amounts are uncertain.
·Refinancing may not be available or financially attractive when you need it.
·Rising payments can create financial stress if your budget is already stretched.
Key takeaway: An ARM isn't automatically riskier for every borrower, but understanding its adjustment structure is essential.
Fixed-Rate vs. Adjustable-Rate Mortgage: Side-by-Side Comparison
Feature | Fixed-Rate Mortgage | Adjustable-Rate Mortgage |
Interest rate | Remains fixed | Fixed initially, then can adjust |
Initial rate | May be higher | May be lower |
Principal and interest payment | Predictable | Can change after initial period |
Rising-rate protection | Throughout loan term | Limited by fixed period and caps |
Long-term budgeting | Easier | More uncertainty |
Common borrower fit | Long-term homeowner | Borrower comfortable with adjustment risk |
Refinancing | Optional strategy | Optional, but not guaranteed |
Neither mortgage type is universally superior.
The best choice is the one that aligns with your expected ownership period, financial flexibility, and long-term goals.
Real-World Example: Fixed-Rate Mortgage vs. 7/6 ARM
Let's compare two hypothetical financing scenarios.
Home purchase price: $450,000
Down payment: $90,000 (20%)
Loan amount: $360,000
Amortization: 30 years
Assume the following illustrative interest rates:
Option A: 30-Year Fixed-Rate Mortgage
·Interest rate: 6.50%
·Monthly principal and interest: Approximately $2,275
·Interest rate stays at 6.50% for the loan term.
Option B: 7/6 Adjustable-Rate Mortgage
·Initial interest rate: 5.75%
·Initial monthly principal and interest: Approximately $2,101
·Rate remains fixed for the first seven years, then can adjust every six months.
Potential Initial Savings
The ARM would save approximately $174 per month in principal and interest during its introductory period.
Over seven years, that represents approximately $14,600 in cumulative payment differences, assuming scheduled payments and unchanged introductory terms.
However, those differences are not the same as total financial savings. The loans amortize differently, and the ARM's interest rate may increase or decrease after year seven.
These figures exclude property taxes, insurance, mortgage insurance, lender fees, points, and other closing costs. Rates are hypothetical, not current loan offers.
What Happens When an ARM Adjusts?
Once the introductory period ends, the ARM's interest rate may move up or down.
Most modern adjustable-rate mortgages use an index, such as the Secured Overnight Financing Rate (SOFR), plus a contractual margin.
For example:
·Index at adjustment: 4.00%
·Contractual margin: 2.75%
·Fully indexed rate: 6.75%
The actual adjusted rate is subject to the mortgage's contractual provisions and applicable caps or floors.
Understanding ARM Rate Caps
ARM rate caps limit how much the interest rate can increase.
A hypothetical 2/1/5 cap structure generally means:
·2% initial adjustment cap: Maximum increase at the first adjustment.
·1% subsequent adjustment cap: Maximum increase at later adjustments.
·5% lifetime adjustment cap: Maximum increase over the initial rate during the life of the loan.
Actual caps vary by product. Some loans also specify downward adjustment limits or interest-rate floors.
Before choosing an ARM, ask your mortgage broker to calculate your possible payment under the maximum permitted interest rate.
When Does a Fixed-Rate Mortgage Make Sense?
A fixed-rate mortgage may be particularly attractive if:
1.You expect to remain in your home for ten years or longer.
2.You prefer stable monthly principal and interest payments.
3.Your household budget has limited room for payment increases.
4.You want protection against future interest-rate increases.
5.You value certainty more than potential introductory savings.
For many first-time homebuyers, the predictability of a fixed-rate mortgage provides valuable peace of mind.
However, long-term stability should still be weighed against the loan's interest rate, fees, and total borrowing costs.
When Does an Adjustable-Rate Mortgage Make Sense?
An ARM may be worth considering when:
1.You expect to relocate within the introductory fixed-rate period.
2.You anticipate selling the property within several years.
3.The ARM provides meaningful initial savings after accounting for fees.
4.You have sufficient income, reserves, and financial flexibility to absorb potential payment increases.
5.You understand the adjustment index, margin, caps, and maximum payment exposure.
An ARM can also be attractive for some medical professionals, executives, or relocating homebuyers who anticipate changes in housing needs.
However, projected career advancement, future income increases, and anticipated refinancing should never be treated as guaranteed.
Should You Choose an ARM If You Expect Mortgage Rates to Fall?
This is one of the most common questions borrowers ask.
If mortgage rates decline, an ARM might eventually adjust downward.
But there are important limitations.
First, your ARM may not adjust until the introductory period expires.
Second, the adjustment depends on the loan's index and contractual provisions, not simply the prevailing advertised mortgage rate.
Third, interest rates could rise instead of fall.
A fixed-rate borrower can also explore refinancing when market rates decline, although refinancing involves new qualification requirements, costs, and potential changes to the loan term.
The better approach is to choose a mortgage you can afford even if your interest-rate forecast turns out to be wrong.
Seven Questions to Ask Before Choosing a Fixed or Adjustable Mortgage
Before making your decision, ask your mortgage broker:
1.What is the initial interest rate and APR for each option?
2.How much are the lender fees, discount points, and closing costs?
3.When can the ARM first adjust, and how frequently afterward?
4.What index, margin, rate caps, and floors apply?
5.What would my payment be at the maximum permitted interest rate?
6.How do the five-year costs and principal balances compare?
7.How does each loan fit my expected ownership period and financial reserves?
A properly prepared Loan Estimate can help you compare interest rates, closing costs, APR, and the projected five-year borrowing costs.
For an ARM, also review the required adjustable-rate disclosures.
Frequently Asked Questions
Is a fixed-rate mortgage better than an ARM?
Not necessarily. Fixed-rate loans offer long-term payment predictability, while ARMs may provide initial savings. The best option depends on your financial circumstances and ownership plans.
Can an adjustable-rate mortgage increase every month?
Not necessarily. Adjustment frequency is specified in the loan documents. For example, a 7/6 ARM generally adjusts no more frequently than every six months after the seven-year introductory period.
Can I refinance an ARM into a fixed-rate mortgage?
Yes, if you qualify for a new loan and refinancing is available. Approval depends on factors such as credit, income, property value, equity, and lender guidelines.
Do adjustable-rate mortgages always start with lower interest rates?
No. ARM pricing depends on market conditions, lender offerings, loan structure, and borrower qualifications. Compare actual offers rather than assuming an ARM is cheaper.
Can an ARM payment decrease?
Yes. If the relevant index declines, an ARM's interest rate and principal and interest payment may decrease, subject to the loan's terms and any applicable floors.
Is a 7/6 ARM better than a 30-year fixed mortgage?
A 7/6 ARM may provide introductory savings, but a fixed-rate loan provides greater long-term certainty. Compare both under realistic scenarios before deciding.
Final Thoughts: Choose the Mortgage That Fits Your Future
Choosing between a fixed-rate mortgage and an adjustable-rate mortgage isn't simply about finding the lowest interest rate today.
It's about understanding your future payment obligations, your financial flexibility, and your long-term homeownership plans.
At Medallion Funds, we help borrowers evaluate financing options, compare loan structures, and understand the potential trade-offs.
Whether you're buying your first home, relocating, purchasing a larger property, or exploring refinancing, the right mortgage strategy begins with the right information.
Let's review your mortgage options together.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Subscribe to Our Newsletter
New Released
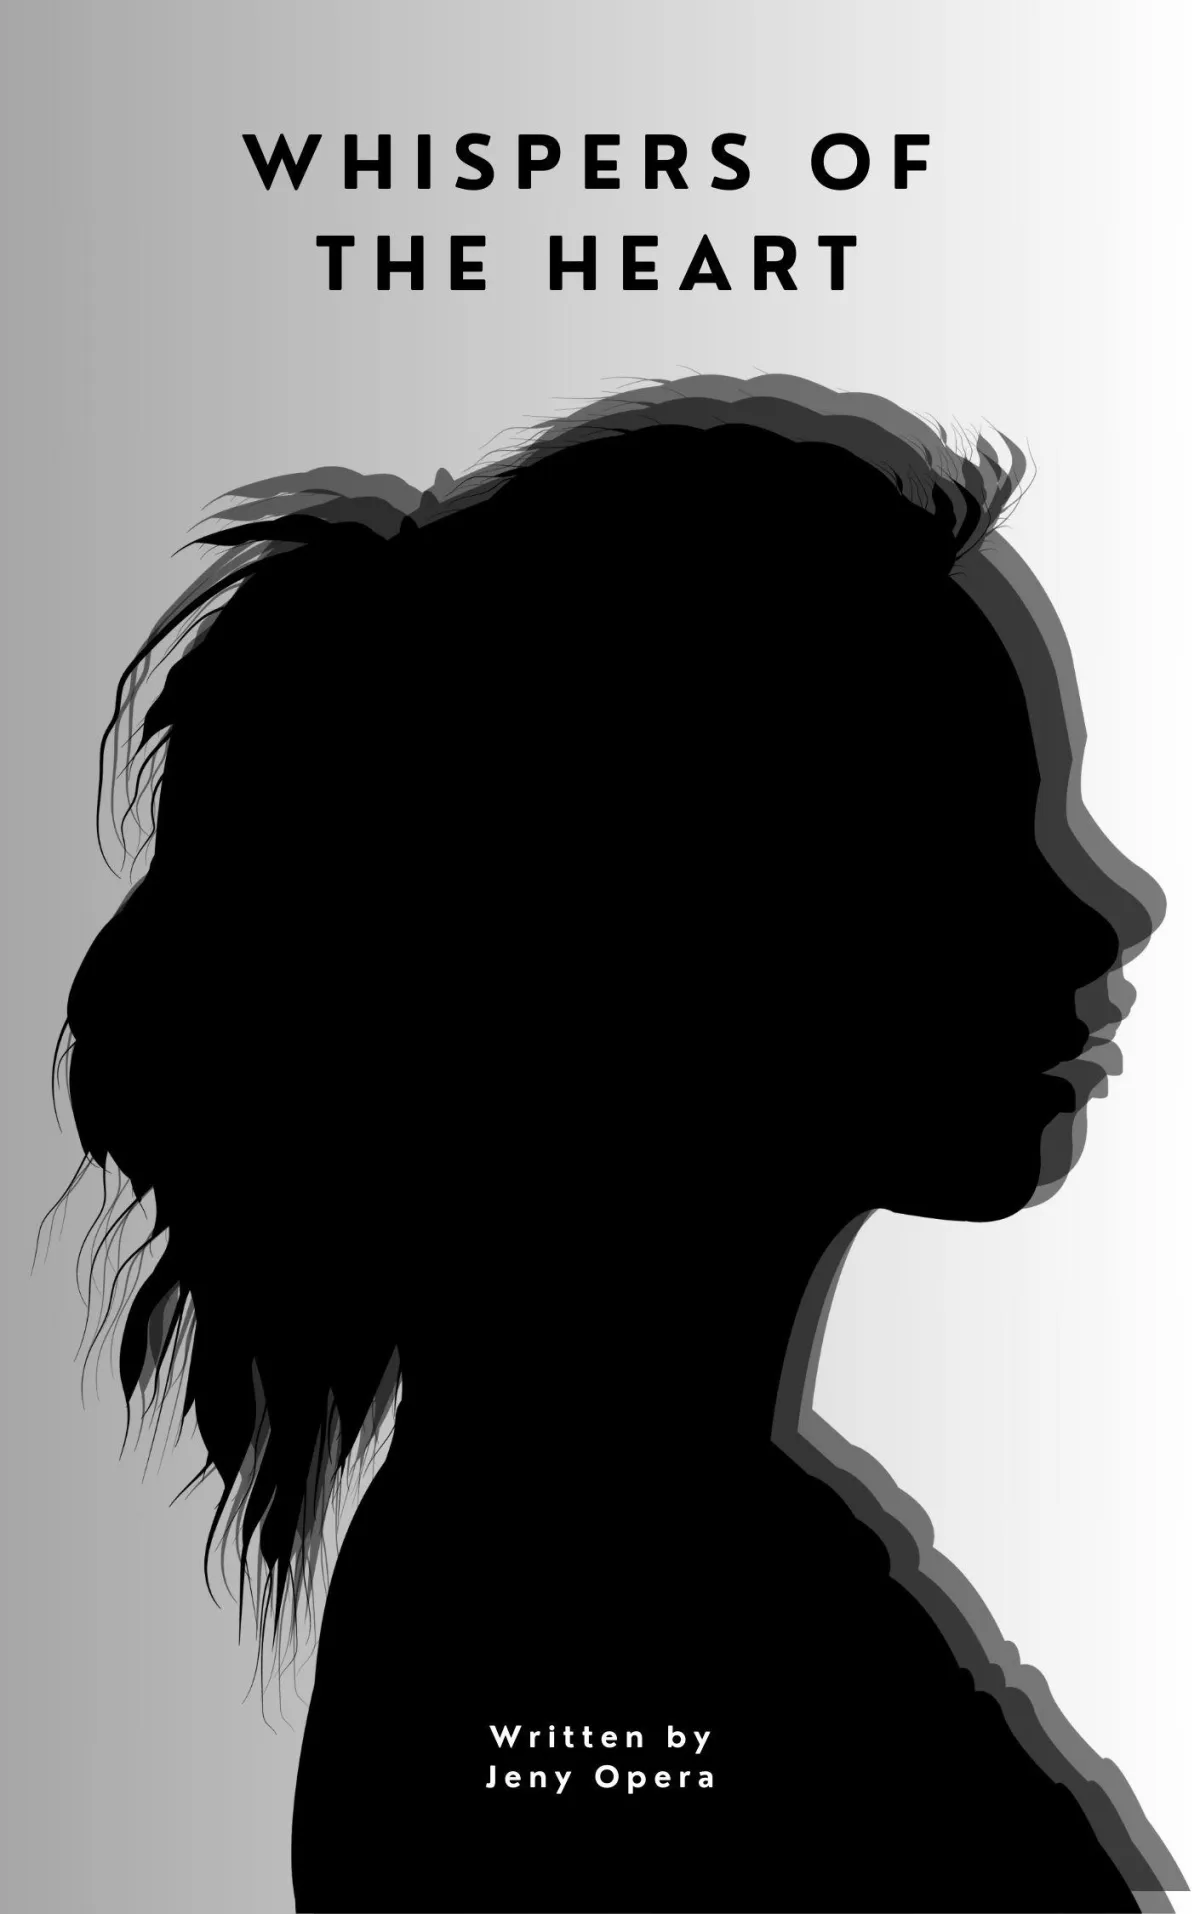
Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
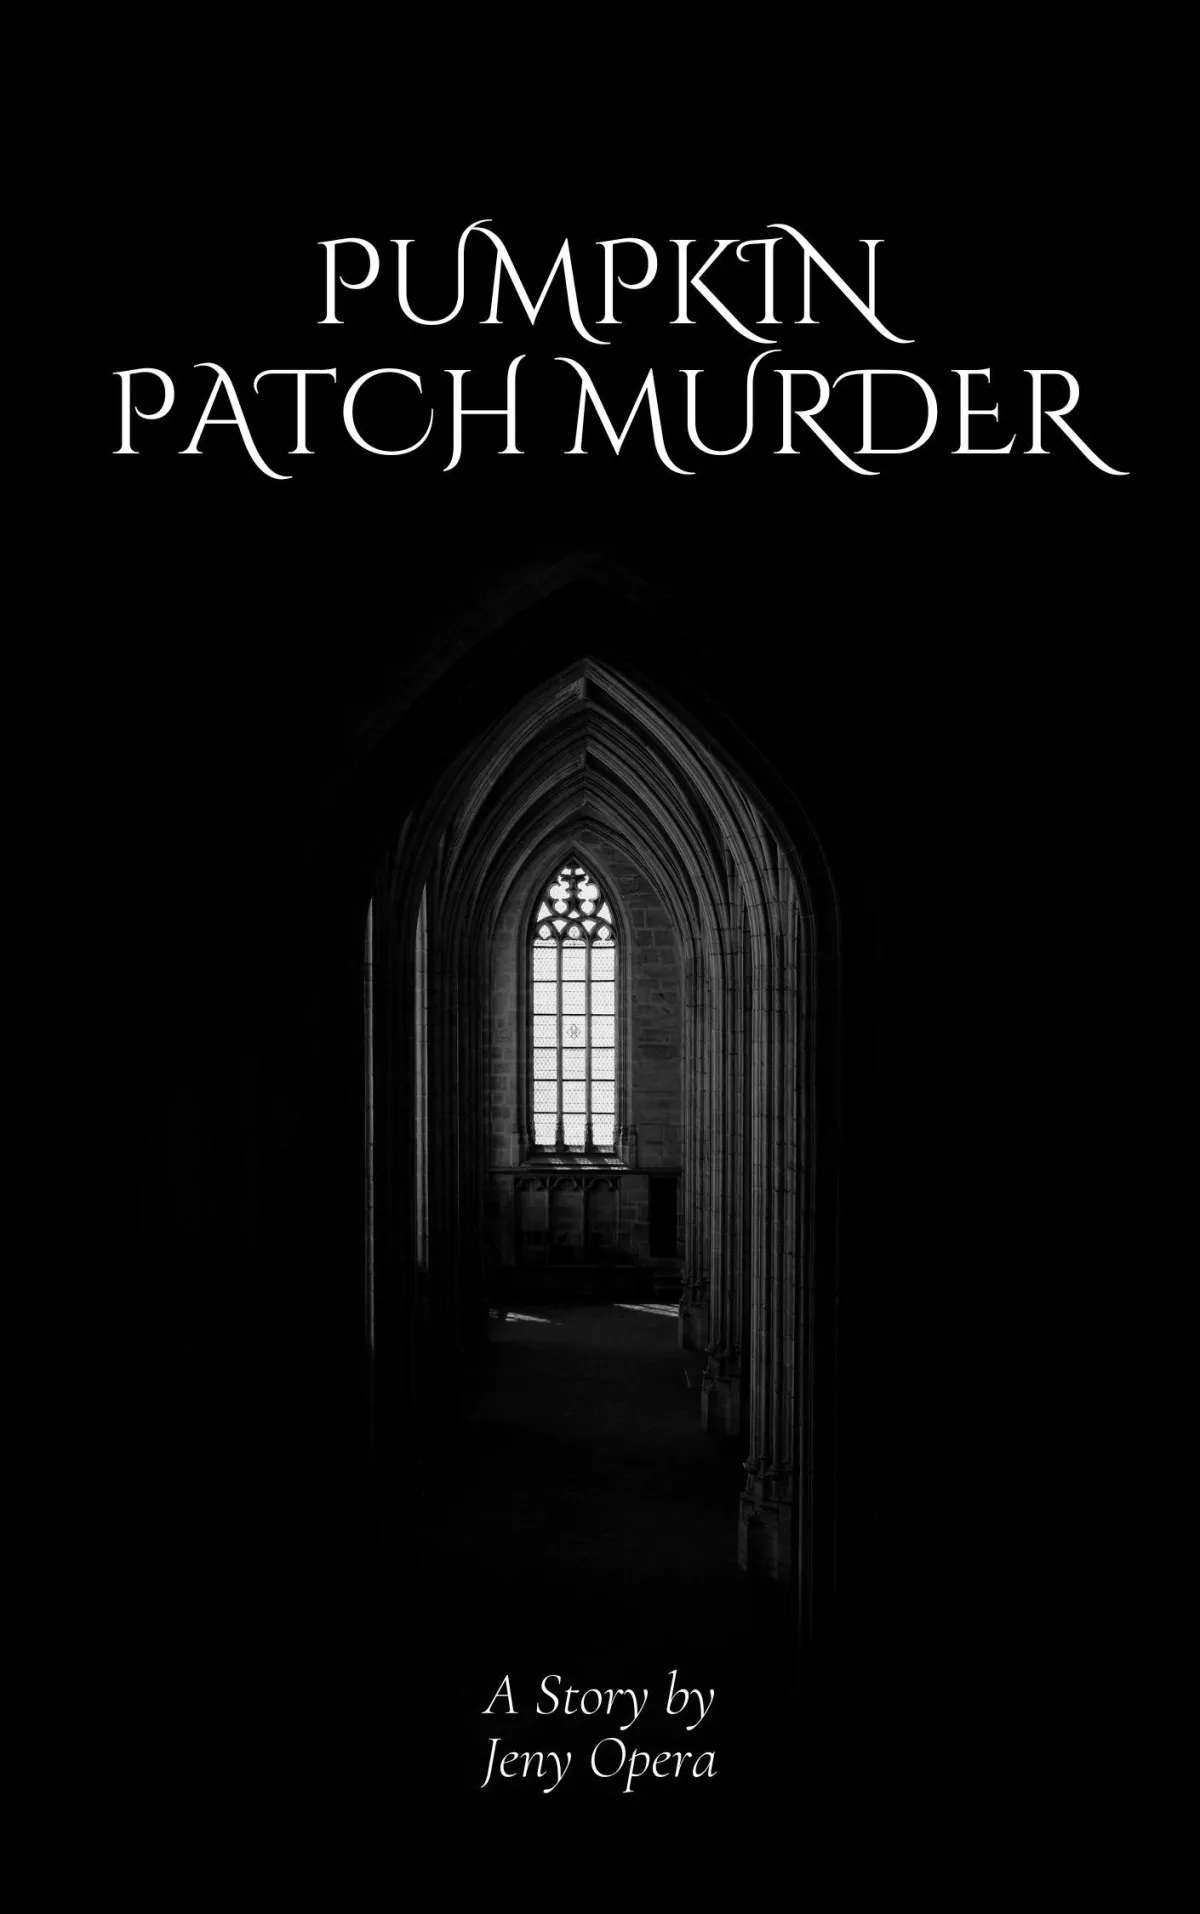
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
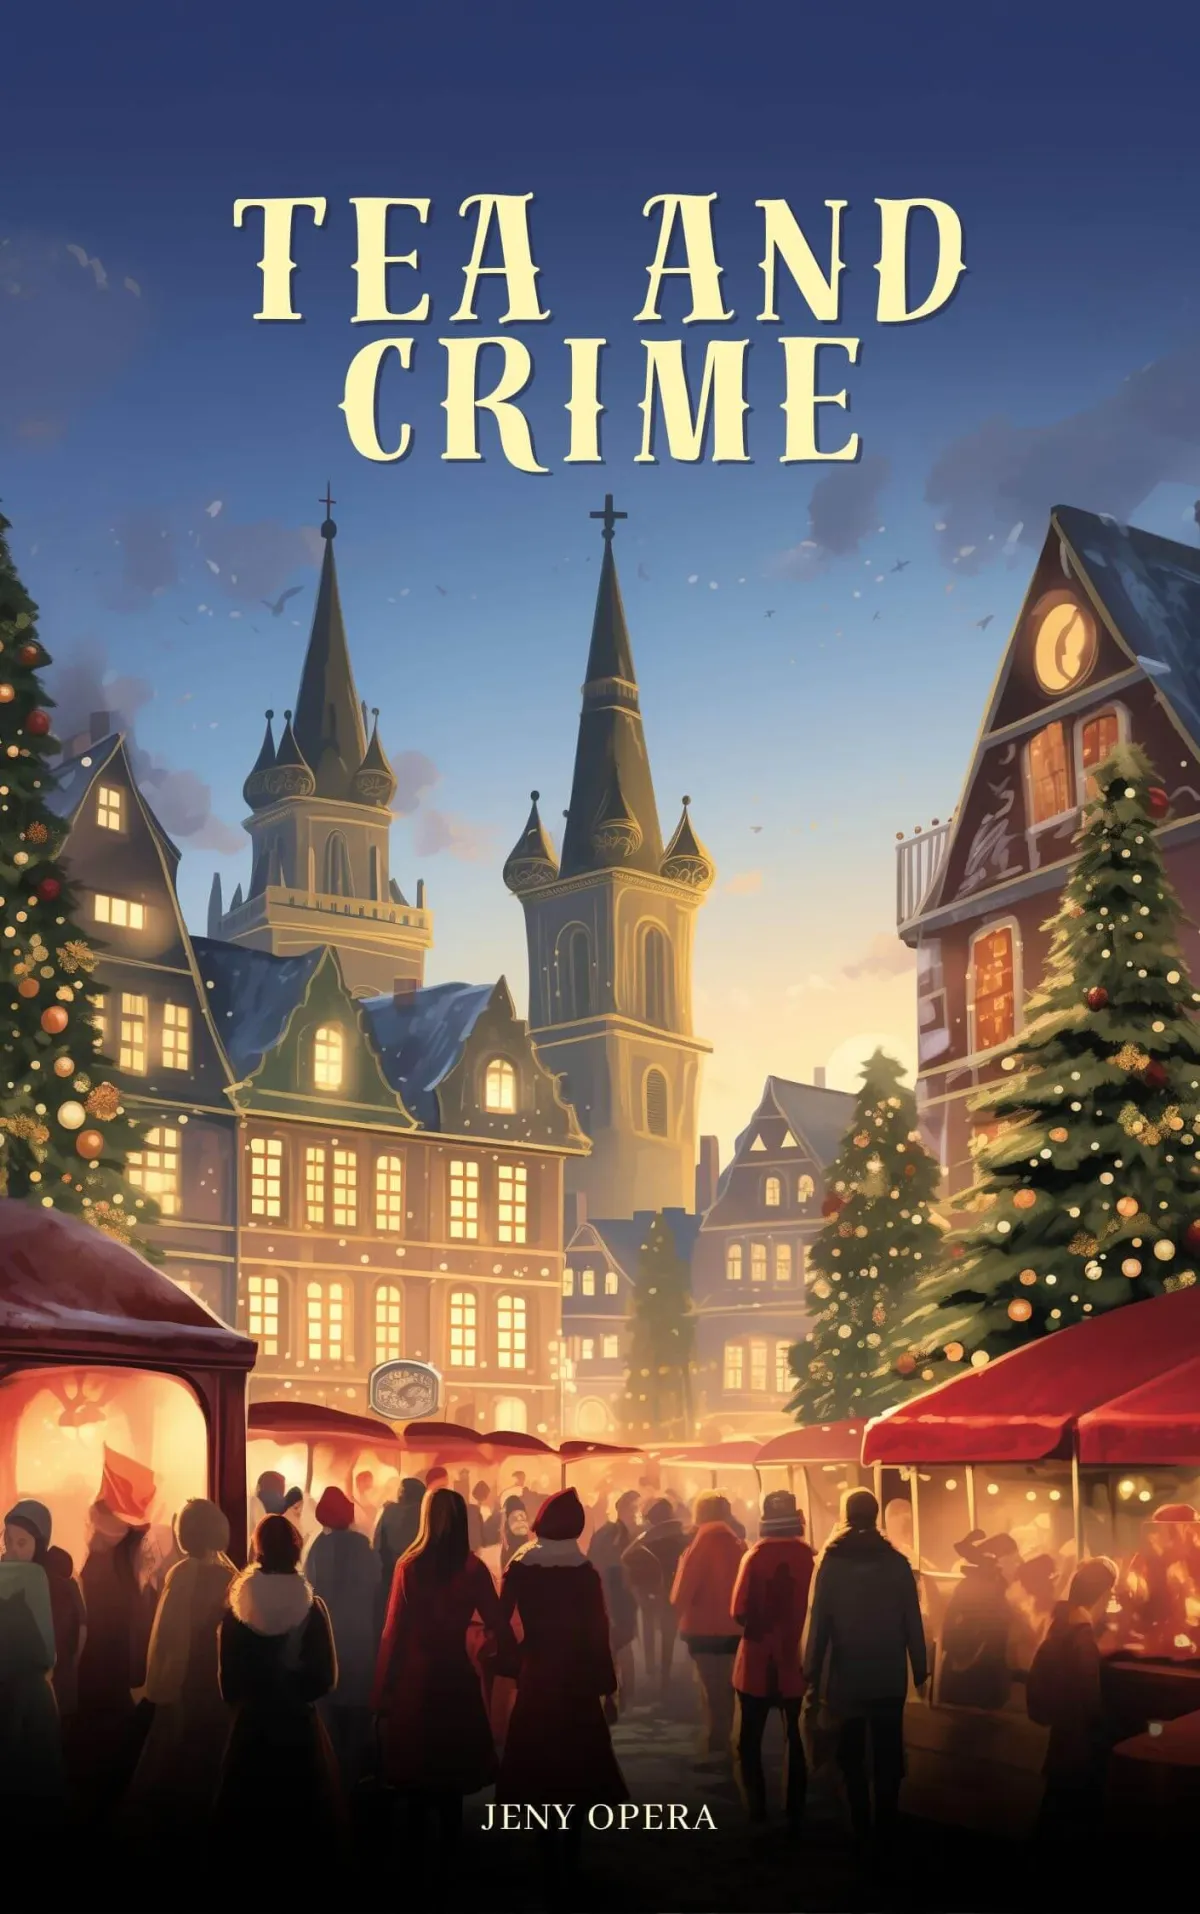
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
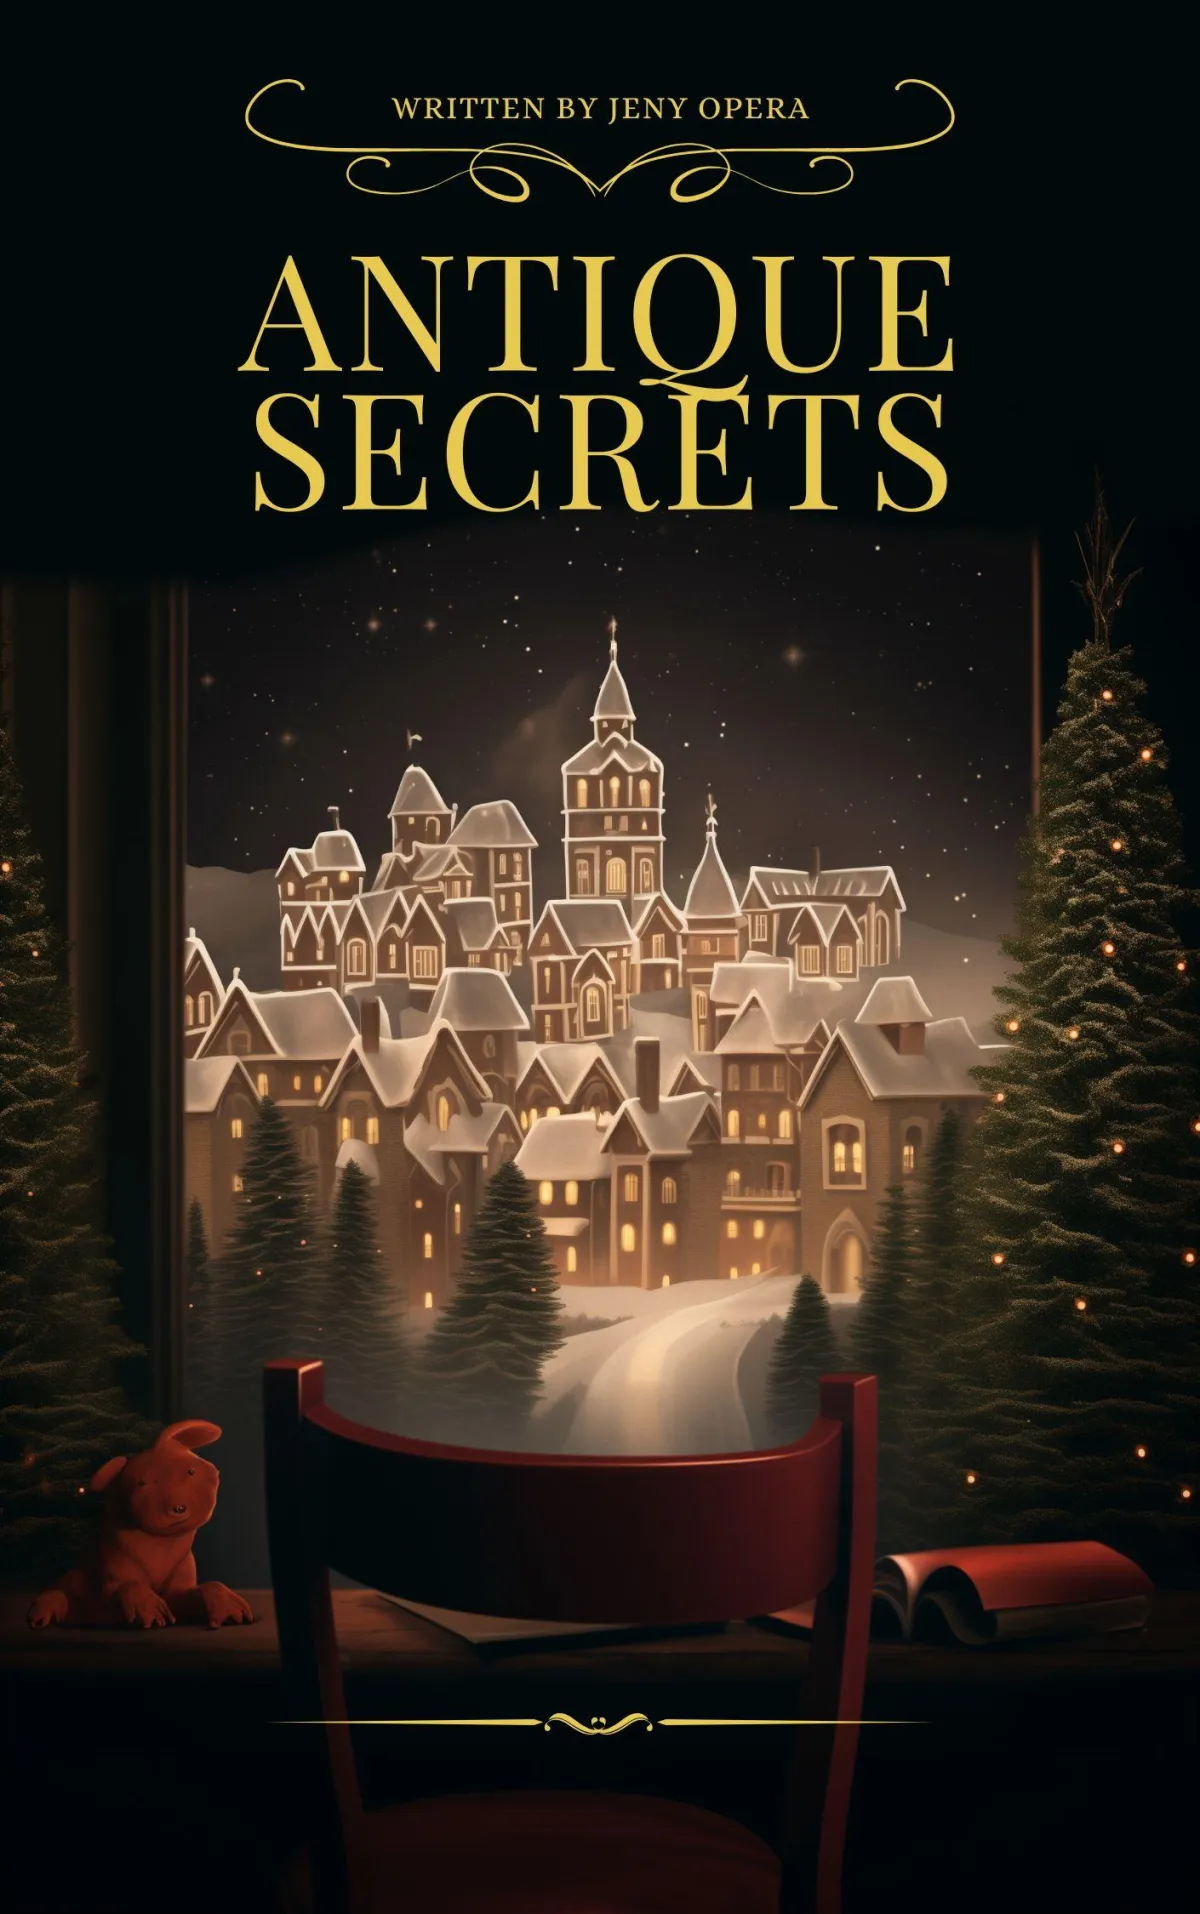
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!
"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.