📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
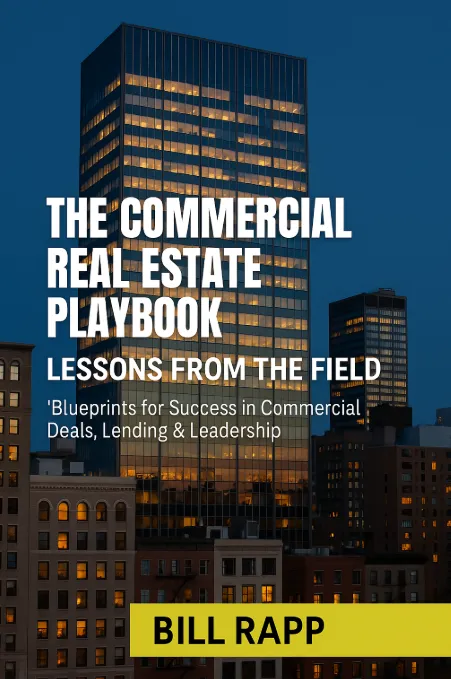
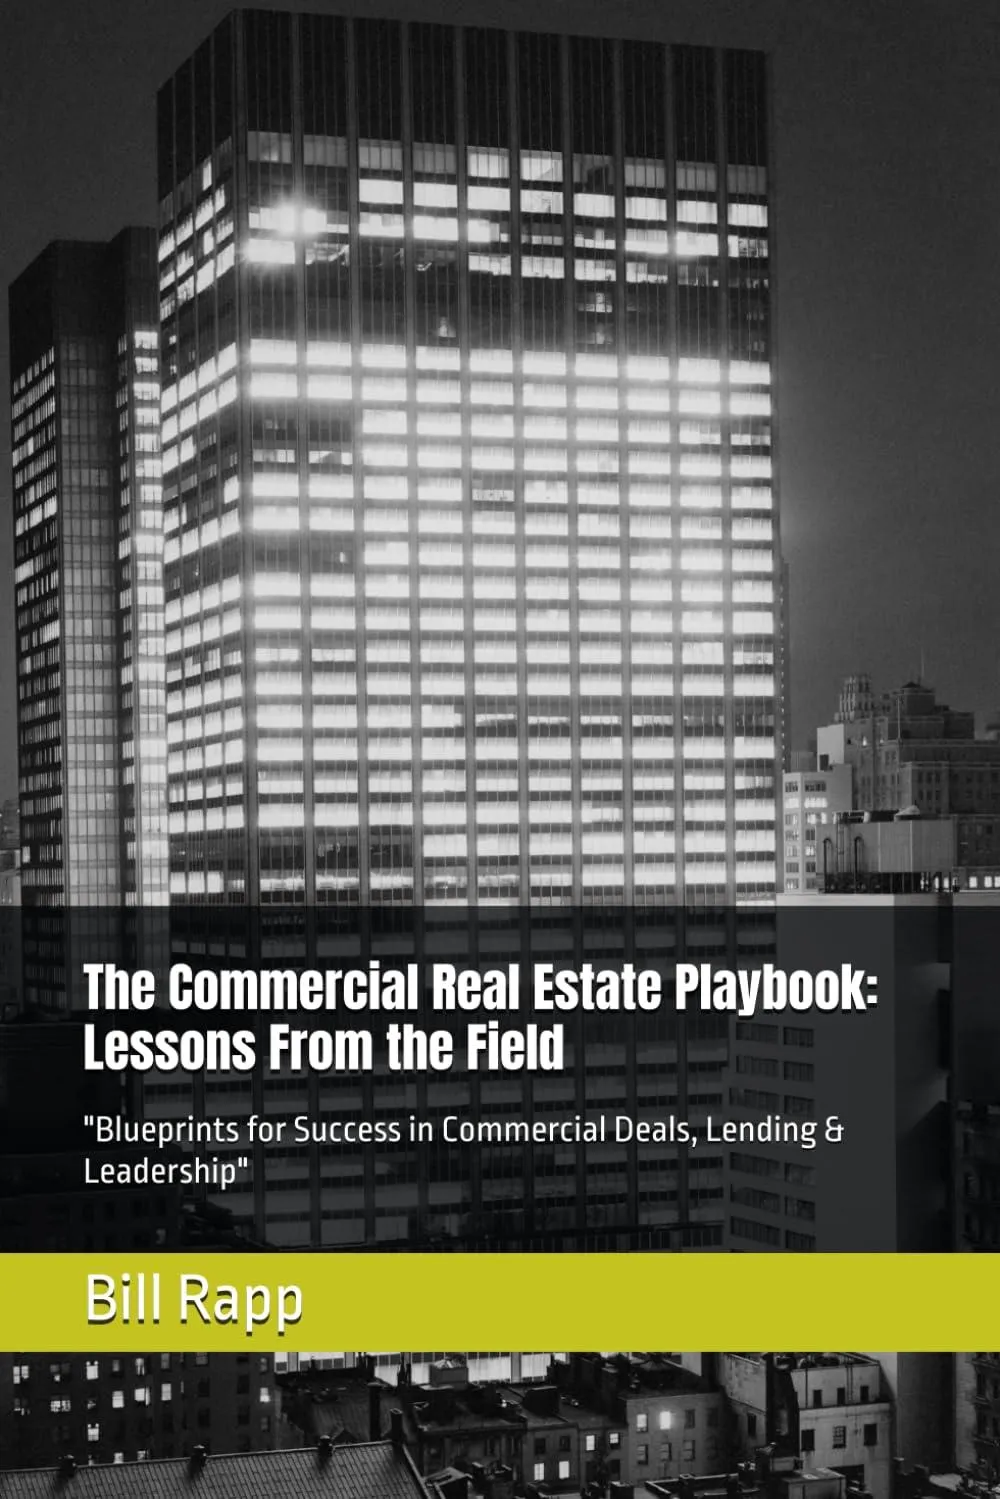
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
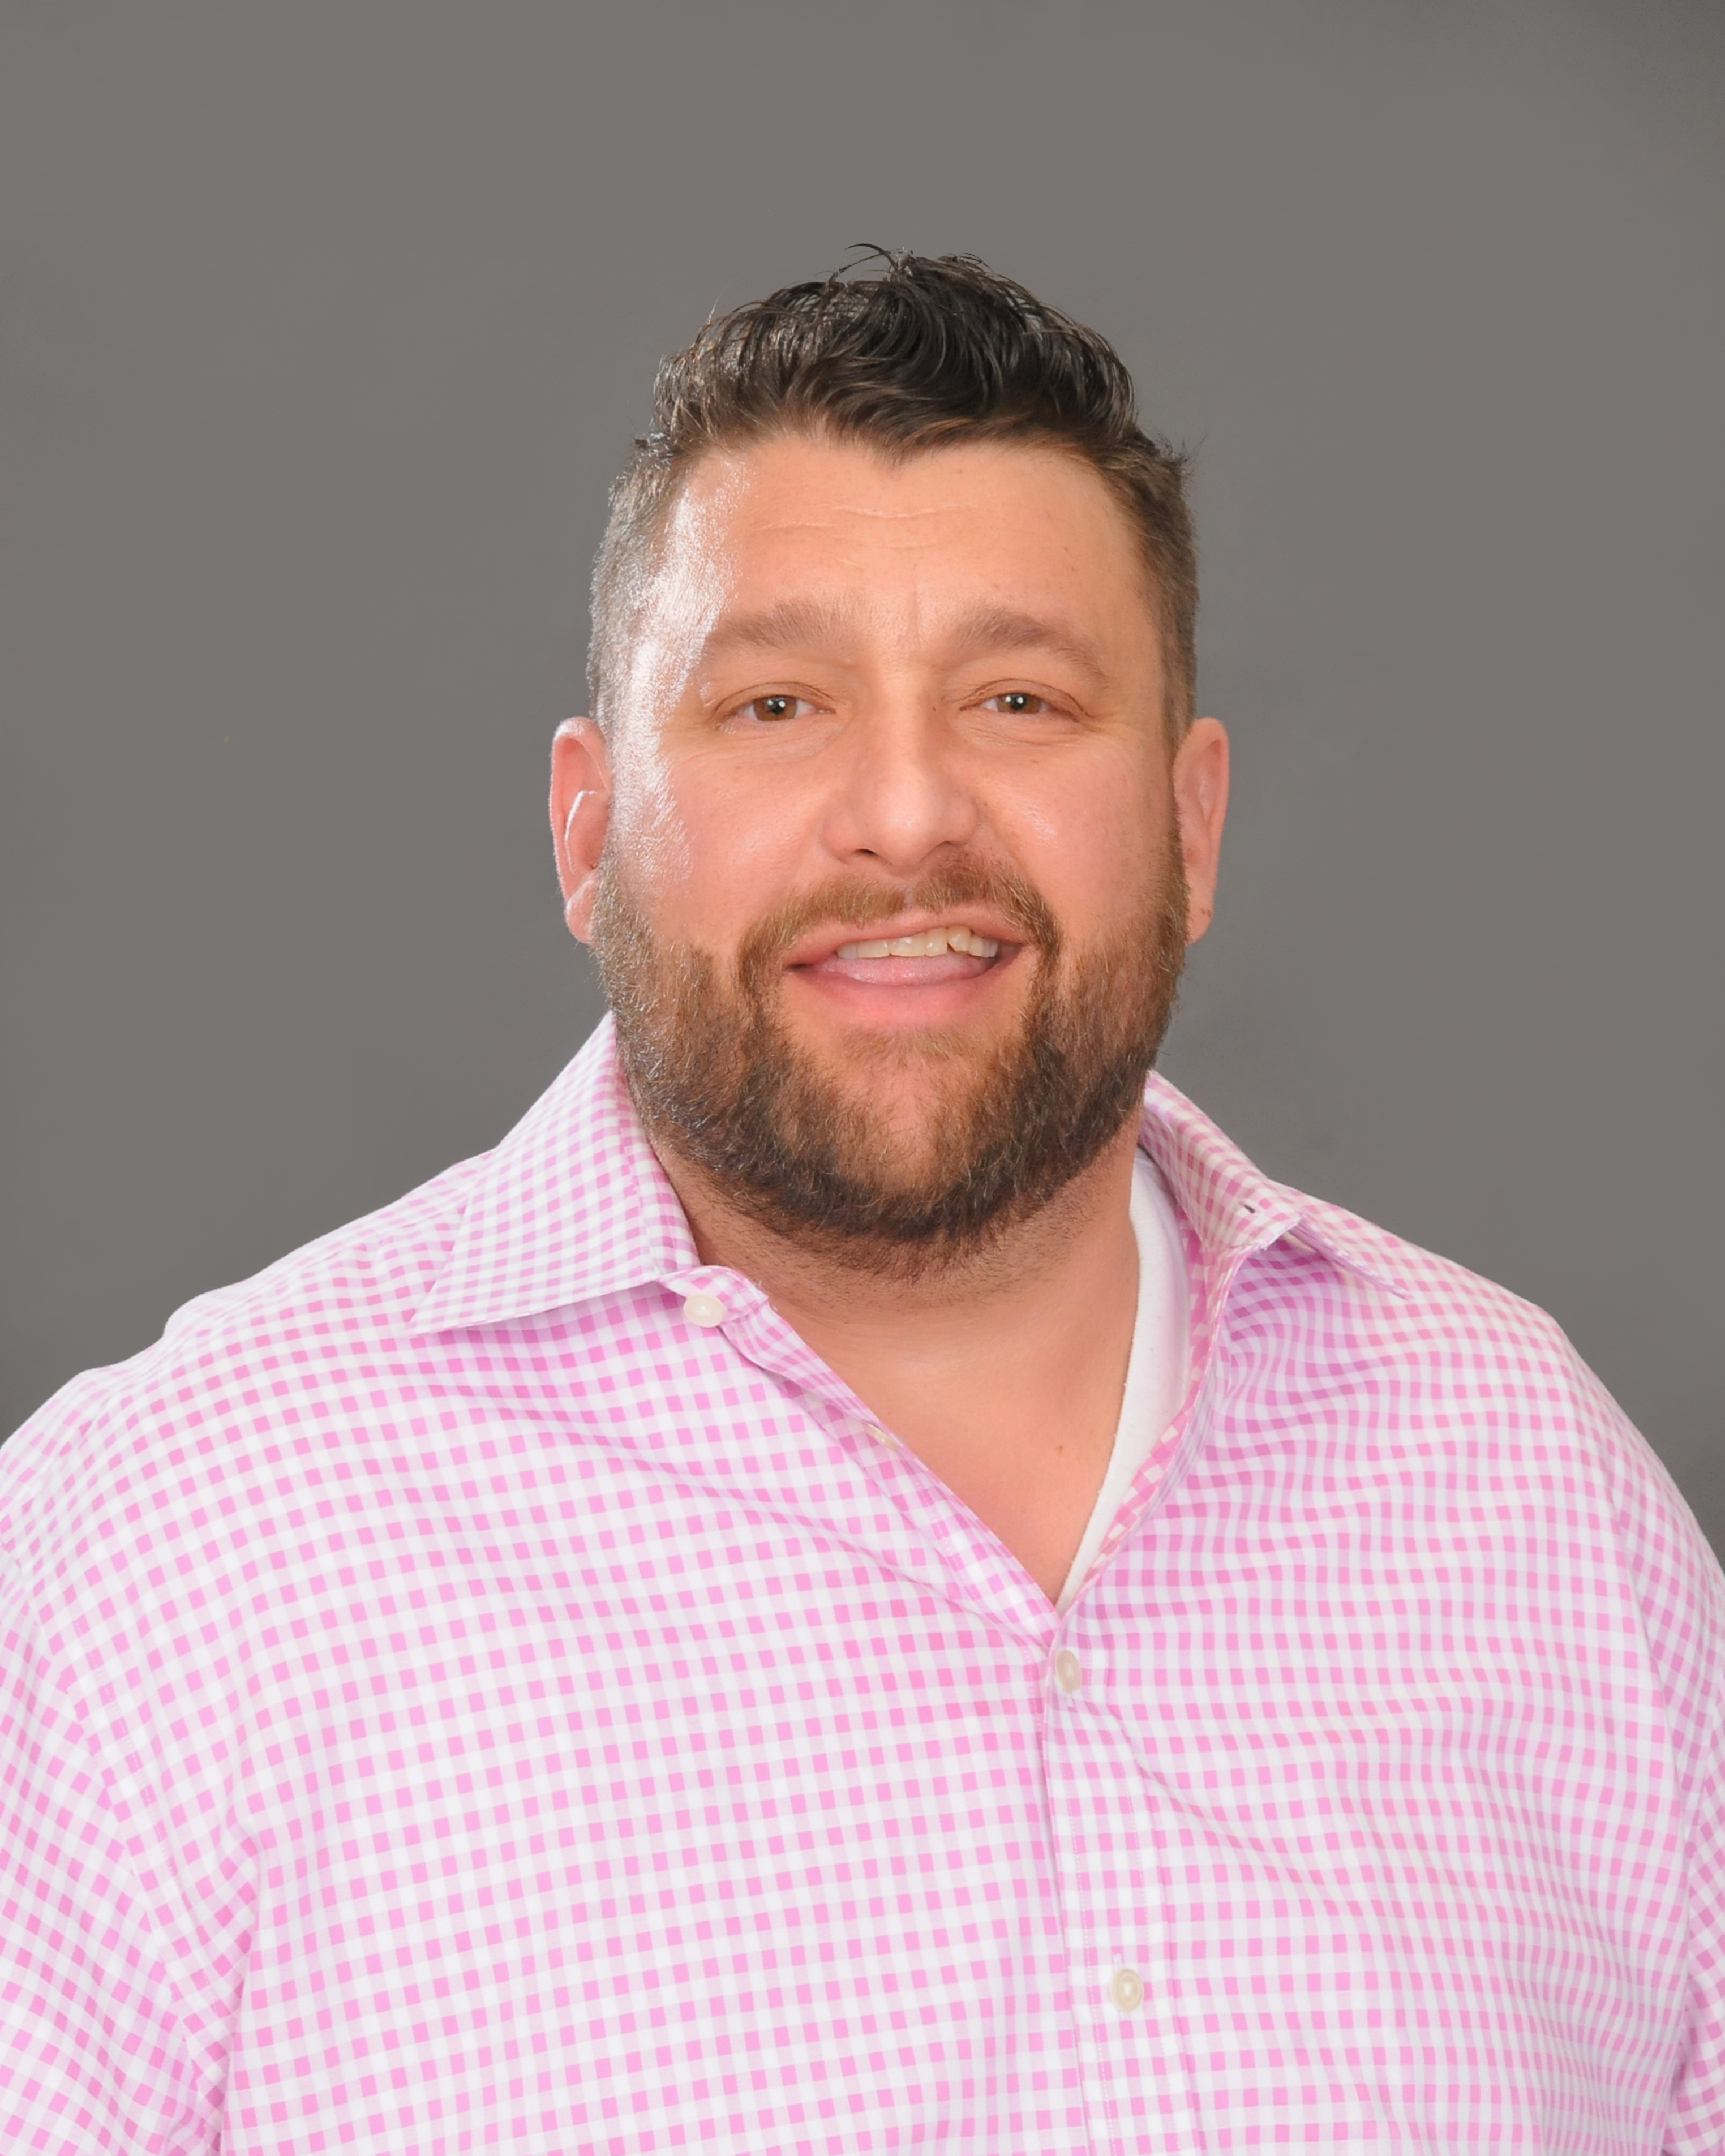
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


🏢 How to Get a Commercial Real Estate Loan: Step-by-Step Guide for Investors & Business Owners 💰
🏢 How to Get a Commercial Real Estate Loan: Step-by-Step Guide for Investors & Business Owners 💰
💵 Commercial Real Estate Loan Requirements: How to Qualify, Find the Right Lender & Secure Financing 🏦
________________________________________________________________________________
Primary keyword: How to Get a Commercial Real Estate Loan
How to Get a Commercial Real Estate Loan: A Step-by-Step Guide
Buying commercial real estate can be one of the most significant financial decisions an investor or business owner makes. Whether you're purchasing an apartment building, office property, retail center, industrial warehouse, or owner-occupied business location, securing the right financing is essential.
But commercial real estate financing works differently from residential mortgage lending.
Commercial lenders evaluate more than your credit score and down payment. They examine the property's income, debt service coverage, borrower experience, liquidity, financial strength, and overall transaction risk.
Understanding how to get a commercial real estate loan can help you avoid costly mistakes, improve your financing options, and negotiate more favorable loan terms.
At the CommLoan Empower Program, we help commercial real estate investors and business owners evaluate financing alternatives through a broad commercial lending marketplace.
Here's what you need to know before applying.
Step 1: Understand the Types of Commercial Real Estate Loans
The first step is identifying the financing program that fits your property, investment strategy, and financial objectives.
Conventional Commercial Real Estate Loans
Conventional commercial mortgages are commonly offered by banks, credit unions, and other commercial lenders.
These loans are frequently used to finance stabilized commercial properties, including office buildings, retail centers, industrial facilities, and multifamily investments.
Typical characteristics may include:
·Loan-to-value ratios around 65%–80%, depending on the lender and property.
·Fixed or floating interest rates.
·Amortization periods commonly ranging from 15–30 years.
·Loan maturities that may be shorter than the amortization schedule.
·Full, partial, or nonrecourse structures, depending on the transaction.
SBA 7(a) and SBA 504 Loans
Small Business Administration loan programs can provide attractive financing for eligible owner-occupied commercial properties.
SBA 7(a) financing can support qualifying real estate purchases, business acquisitions, equipment, and certain working capital needs.
SBA 504 financing primarily supports eligible long-term fixed assets, including commercial property acquisitions, construction, and major equipment.
Qualified borrowers may benefit from lower equity requirements than many conventional commercial mortgages.
SBA financing generally requires qualifying business occupancy and is not designed for passive real estate investment.
Commercial Bridge Loans
Bridge financing is often used when a property needs renovations, lease-up, repositioning, or stabilization before qualifying for permanent financing.
Bridge loans typically offer shorter terms and may carry higher interest rates and fees than stabilized permanent financing.
A clearly defined exit strategy is critical.
Multifamily and Agency Loans
Investors purchasing or refinancing qualifying apartment properties may have access to financing through banks, life insurance companies, debt funds, and agency lending programs.
Fannie Mae and Freddie Mac multifamily programs can provide attractive financing for eligible properties and sponsors.
Construction Loans
Construction financing supports ground-up development, major renovations, and redevelopment projects.
Lenders typically evaluate construction budgets, project feasibility, sponsor experience, guarantees, and the anticipated permanent financing or sale strategy.
Key takeaway: The best loan program depends on the property, borrower, and business plan—not simply the lowest advertised interest rate.
Step 2: Understand Commercial Loan Qualification Requirements
Commercial mortgage lenders generally evaluate several important underwriting factors.
Loan-to-Value Ratio (LTV)
LTV measures the proposed loan amount relative to the property's appraised value.
\[ \text{LTV}=\frac{\text{Loan Amount}}{\text{Property Value}}\times100 \]
For example, if a property is valued at $2,000,000 and the proposed loan is $1,400,000:
\[ \text{LTV}=70\% \]
For acquisitions, lenders may also apply purchase-price or lower-of-cost-or-value limitations.
Debt Service Coverage Ratio (DSCR)
DSCR measures the property's ability to cover its annual mortgage payments from net operating income.
\[ \text{DSCR}=\frac{\text{Net Operating Income}}{\text{Annual Debt Service}} \]
Suppose a commercial property generates $180,000 in annual NOI and requires $135,000 in annual debt service.
\[ \text{DSCR}=1.33x \]
This means the property generates approximately $1.33 in net operating income for every $1.00 of required debt service.
Many lenders target minimum DSCR levels around 1.20x–1.30x, although actual requirements vary by property type, loan product, and lender.
Debt Yield
Debt yield evaluates the property's NOI relative to the loan amount.
\[ \text{Debt Yield}=\frac{\text{NOI}}{\text{Loan Amount}}\times100 \]
For a property with $180,000 in NOI and a proposed $1,800,000 loan:
\[ \text{Debt Yield}=10\% \]
Debt yield helps lenders evaluate credit risk independently of interest rates and amortization.
Borrower Credit, Liquidity, and Net Worth
Commercial lenders may also consider personal credit, available liquidity, contingent liabilities, real estate ownership experience, and post-closing reserves.
A strong property does not automatically overcome a weak borrower profile.
Step 3: Determine Your Down Payment
One of the most common questions is:
How much money do I need down for a commercial real estate loan?
The answer depends on the property type, financing program, and transaction risk.
Financing type | Illustrative equity requirement |
Conventional commercial mortgage | 20%–35% |
SBA 7(a) real estate financing | Often 10% or more |
SBA 504 eligible project | Often 10%–20% |
Multifamily investment financing | 20%–35% |
Hotel financing | 25%–40% or more |
Bridge financing | Varies substantially |
These are general planning ranges, not guaranteed lender terms. SBA equity requirements depend on program rules and transaction characteristics.
Investors should also budget for appraisals, environmental assessments, legal fees, lender fees, reserves, and other closing expenses.
Step 4: Prepare Your Commercial Loan Documentation
One of the fastest ways to delay a commercial financing transaction is submitting an incomplete loan package.
Depending on the lender and transaction, commonly requested documents include:
·Purchase contract or letter of intent.
·Current rent roll and copies of leases.
·Trailing 12-month operating statement (T-12).
·Historical property financial statements.
·Personal financial statement.
·Personal and business tax returns, when required.
·Bank and investment account statements.
·Schedule of real estate owned.
·Business financial statements for owner-occupied properties.
·Property insurance information.
·Business plan, renovation budget, or construction projections when applicable.
A complete package helps lenders evaluate the transaction more efficiently and can reduce repeated document requests.
Step 5: Determine How Much Financing the Property Can Support
One of the biggest misconceptions in commercial real estate financing is that a lender's maximum advertised LTV automatically determines your loan amount.
It doesn't.
Lenders may size loans using several constraints, including LTV, DSCR, debt yield, and borrower financial strength.
Example: Commercial Loan Sizing
Illustrative investment property financing
Property value
$3,000,000
Annual NOI
$210,000
Maximum LTV
75%
Minimum DSCR
1.25x
Loan sizing constraints
LTV maximum
$2,250,000
DSCR maximum
$2,059,000
Estimated maximum loan
$2.06M
Assumes a 7.00% interest rate, 25-year amortization, annual debt service factor of approximately 8.48%, and no more restrictive debt-yield or other constraints. Illustration only.
Even though the lender permits 75% LTV, the property's income supports a smaller loan under the assumed DSCR requirement.
This is why underwriting the property before negotiating financing terms is so important.
Step 6: Compare Commercial Mortgage Lenders
Different commercial lenders have different credit policies, property preferences, and loan structures.
A bank might offer an attractive rate but require substantial recourse.
A debt fund might provide more flexible underwriting but charge higher financing costs.
An agency lender might offer attractive long-term financing for a qualifying multifamily property but impose specific prepayment provisions.
When comparing commercial loan offers, evaluate:
1.Interest rate and total borrowing cost.
2.Maximum loan proceeds.
3.Loan term and amortization.
4.Recourse and guarantee requirements.
5.Prepayment penalties and exit flexibility.
6.Reserve requirements and closing costs.
The cheapest quoted interest rate does not necessarily produce the best investment outcome.
Step 7: Get Prequalified Before Making an Offer
Commercial loan prequalification can help investors understand their potential financing capacity before entering into a purchase agreement.
An initial financing assessment may evaluate property value, anticipated NOI, down payment availability, borrower experience, and proposed loan structure.
Prequalification is not a commitment to lend. Final approval remains subject to underwriting, due diligence, and lender requirements.
Nevertheless, an informed financing strategy can improve negotiations and reduce execution risk.
Step 8: Complete Underwriting and Due Diligence
Once a lender is selected, the transaction moves through formal underwriting.
The process may involve:
·Third-party appraisal.
·Phase I environmental site assessment.
·Property condition assessment.
·Title and survey review.
·Lease and income verification.
·Borrower financial verification.
·Credit approval and legal documentation.
Additional requirements may apply to specialized property types such as hotels, healthcare facilities, restaurants, and construction projects.
Step 9: Review the Loan Terms Before Closing
Before signing commercial mortgage documents, understand the obligations you are accepting.
Pay particular attention to balloon maturities, personal guarantees, cash management provisions, reserve requirements, financial reporting covenants, and prepayment penalties.
Some commercial loans require yield maintenance, defeasance, or other prepayment arrangements that can materially affect the cost of refinancing or selling.
A financing structure should align with your anticipated ownership period and exit strategy.
Step 10: Work With a Commercial Capital Advisor
Commercial financing is not a one-size-fits-all process.
The right capital advisor can help investors understand lender requirements, structure a financeable transaction, evaluate competing loan offers, and identify potential issues before they become closing problems.
Through the CommLoan Empower Program, borrowers can explore financing opportunities through a commercial lending marketplace with access to more than 700 lenders.
Instead of assuming that one bank's credit policy represents the entire lending market, investors can evaluate financing alternatives based on the needs of their specific transaction.
Common Mistakes to Avoid When Applying for a Commercial Real Estate Loan
Several preventable mistakes can undermine an otherwise attractive transaction.
Mistake 1: Shopping exclusively for the lowest rate. Loan proceeds, recourse, prepayment flexibility, and maturity risk may matter just as much.
Mistake 2: Assuming maximum LTV equals available financing. DSCR and debt yield may produce a lower loan amount.
Mistake 3: Underestimating required equity. Closing expenses, reserves, and lender adjustments can increase the cash required.
Mistake 4: Providing incomplete financial documentation. Missing rent rolls, financial statements, and borrower information can delay underwriting.
Mistake 5: Ignoring the exit strategy. A short-term loan without a realistic refinance or sale plan can create significant risk.
Frequently Asked Questions About Commercial Real Estate Loans
What credit score do you need for a commercial real estate loan?
There is no universal minimum credit score. Some commercial lenders emphasize sponsor credit, while others place greater weight on property cash flow, collateral, and liquidity. SBA and bank programs may have specific credit standards.
Can I get a commercial real estate loan with 10% down?
Potentially. Certain qualifying SBA transactions may permit financing with approximately 10% borrower equity, while conventional investment property loans often require substantially more.
How long does it take to get a commercial real estate loan?
Straightforward transactions may close within approximately 30–60 days after a complete application, while complex, agency, SBA, construction, or specialized property transactions may take longer. Timelines vary considerably.
Can an LLC obtain a commercial real estate loan?
Yes. Many commercial real estate loans are originated to limited liability companies or other eligible borrowing entities. Lenders may still require personal guarantees or evaluate the financial strength of the principals.
Can I qualify without substantial commercial real estate experience?
Possibly. Lenders consider borrower experience alongside property performance, leverage, financial resources, and professional management. Requirements vary by lender and program.
Is it better to use a bank or commercial mortgage broker?
A bank offers its own financing programs, while a commercial mortgage broker or capital advisor can help evaluate alternatives across multiple lending sources. The best approach depends on your transaction and existing lending relationships.
Final Thoughts: Getting the Right Commercial Real Estate Loan
Getting a commercial real estate loan involves more than completing an application.
Successful borrowers understand their financing options, prepare complete financial documentation, evaluate the property's cash flow, and select financing that supports their investment strategy.
Whether you're acquiring your first commercial property, expanding your portfolio, refinancing an existing investment, or purchasing real estate for your business, the right financing structure can make a meaningful difference.
Ready to Explore Your Commercial Financing Options?
Bill Rapp, CCIM CommLoan Empower Program | Commercial Capital Advisor
Explore commercial financing alternatives and take the next step toward your investment objectives.
Explore Commercial Financing with Bill Rapp
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Subscribe to Our Newsletter
New Released

Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!

"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.