📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


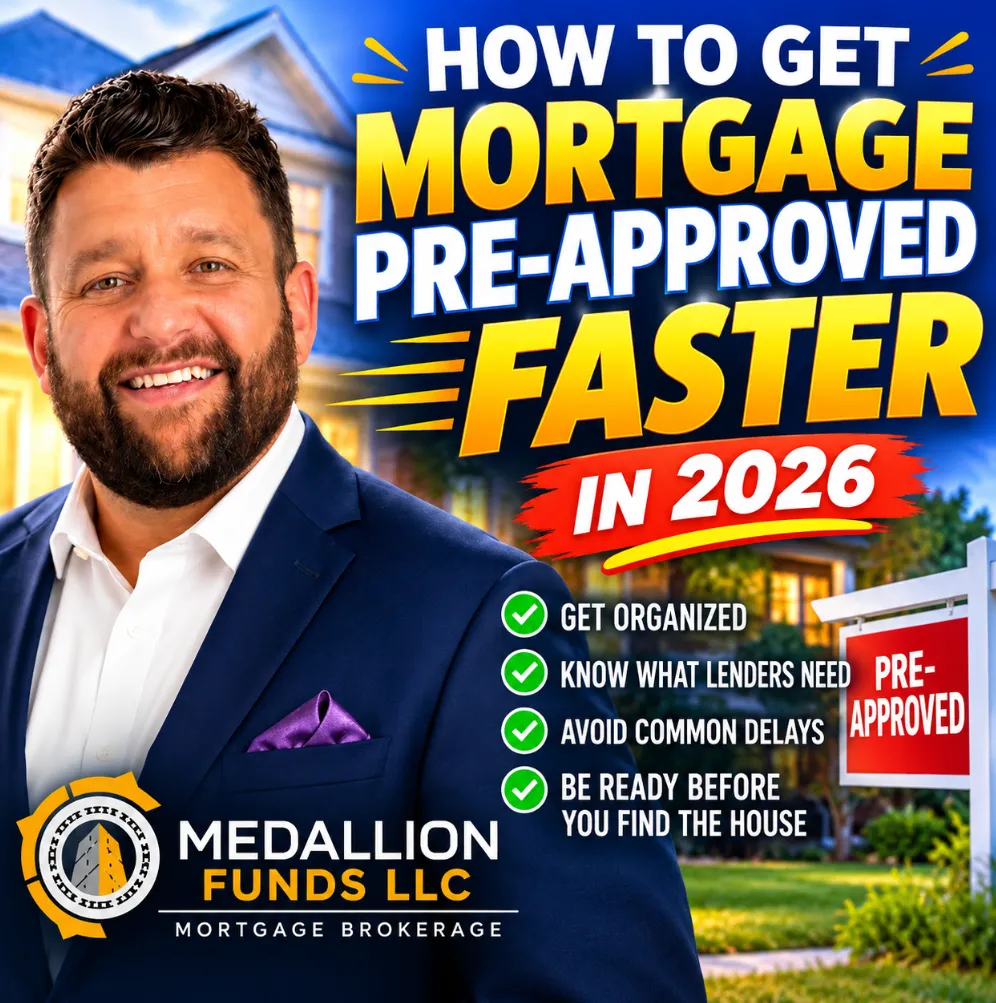
🏡 How to Get Mortgage Pre-Approved Faster in 2026: 7 Steps Before You Start House Hunting 🔑
🏡 How to Get Mortgage Pre-Approved Faster in 2026: 7 Steps Before You Start House Hunting 🔑
⚡ Mortgage Pre-Approval in 2026: How to Get Approved Faster and Avoid Last-Minute Surprises 🏠
How to Get Mortgage Pre-Approved Faster in 2026
When you find the right house, the last thing you want is your mortgage pre-approval slowing you down.
A strong mortgage pre-approval can help you understand your buying power, identify financing issues early, and show a seller that you have already started addressing the financial side of the transaction. The Consumer Financial Protection Bureau notes that lenders generally evaluate your income, assets, debts, and credit record when issuing a pre-approval.
But there is an important distinction:
Getting pre-approved quickly isn't about rushing through the mortgage process. It's about being prepared before the process starts.
Here are seven ways homebuyers can potentially make the mortgage pre-approval process faster and smoother in 2026.
1. Gather Your Mortgage Documents Before Applying
One of the easiest ways to create delays is to start an application and then spend days searching for documents.
For a typical salaried borrower, it can help to have your recent paystubs, W-2s, bank and investment statements, identification, and information about your current debts readily available.
Fannie Mae's current 2026 guidance requires lenders to verify employment income used to qualify. Depending on the loan and underwriting findings, that verification may involve borrower documentation, employer information, or third-party verification services.
If you're self-employed, own multiple businesses, receive rental income, earn commissions or bonuses, or have other less-traditional income, your documentation requirements may be more extensive.
The more complicated your financial picture, the more valuable it can be to start early.
2. Complete the Application Accurately the First Time
Speed isn't just about uploading documents quickly.
It's also about providing accurate information.
Your mortgage application may include information about your:
·Employment and income
·Assets and available funds
·Existing debts
·Real estate owned
·Housing history
·Loan purpose and occupancy
·Other financial obligations
Fannie Mae requires lenders to confirm that information used in underwriting is accurate and complete and to maintain documentation supporting items such as income, employment, assets and credit history.
Missing or inconsistent information can create additional questions later.
3. Don't Hide the Complicated Parts
Changed jobs recently?
Own another property?
Self-employed?
Receiving bonus, commission or overtime income?
Using gift funds?
Have a large recent bank deposit?
Tell your mortgage professional before the file reaches a critical point.
Mortgage underwriting is fundamentally about documenting the borrower's ability to meet the loan requirements. Fannie Mae, for example, describes stable and predictable income as a foundational component of underwriting and requires qualifying income to be appropriately documented.
A potentially complicated issue identified on Day 1 can often be addressed much more efficiently than the same issue discovered days before closing.
4. Know the Difference Between Pre-Qualification and Pre-Approval
These terms are sometimes used interchangeably in the marketplace, but consumers should understand what has actually been reviewed.
A pre-approval generally involves a lender reviewing your financial information and credit to estimate how much you may be able to borrow. It is still not a final loan approval.
The CFPB specifically notes that a pre-approval letter is conditional on further confirmation of the borrower's information.
That's why I encourage buyers to focus on the quality of the review, not simply how quickly someone can generate a letter.
A five-minute letter isn't necessarily better than a thorough pre-approval that identifies potential problems before you sign a purchase contract.
5. Don't Make Major Financial Changes After Pre-Approval
Getting your pre-approval isn't the end of the financing process.
Once you're preparing to purchase a home, avoid making unnecessary financial moves without first discussing them with your mortgage professional.
That can include opening new credit accounts, financing furniture or vehicles, changing employment, moving large amounts of money between accounts, or taking on additional debt.
Remember: your final loan approval depends on the information ultimately verified by the lender.
Your goal should be to keep your financial profile as stable and documentable as possible between pre-approval and closing.
6. Get Pre-Approved Before You Find the House
Waiting until you've found the perfect property puts unnecessary pressure on the process.
The CFPB recommends exploring mortgage choices before finding a home because an accepted offer can leave a buyer with only a short period to arrange financing.
Starting early gives you time to address issues involving credit, debt-to-income ratios, cash reserves, documentation, or loan-program eligibility.
It can also help answer a much more important question than:
"What's the maximum house I qualify for?"
Instead, ask:
"What purchase price and monthly payment make sense for my financial goals?"
Those aren't necessarily the same number.
7. Work With a Mortgage Broker Who Can Evaluate Multiple Loan Options
Not every borrower fits neatly into the same mortgage program.
One borrower may be best suited for conventional financing. Another may need FHA or VA financing. A physician may benefit from evaluating doctor-loan options, while a self-employed borrower may need an alternative documentation program.
That's where working with a mortgage broker can add value.
At Medallion Funds, our objective isn't simply to generate a pre-approval letter. It's to understand the borrower's complete financial picture, evaluate appropriate financing strategies, and identify potential obstacles as early as possible.
That may include Conventional, FHA, VA, USDA, Jumbo, Doctor/Dentist, Bank Statement, Non-QM, DSCR and other financing solutions, subject to program availability and borrower eligibility.
What Should You Have Ready for Mortgage Pre-Approval?
Before contacting your mortgage professional, start assembling your income documentation, asset statements, identification, employment history, housing information and details regarding other properties or businesses you own.
If you're self-employed, additional tax-return and business documentation may be necessary. Fannie Mae's 2026 guidelines, for example, specify tax-return requirements for certain types of qualifying income and require applicable schedules when federal tax returns are used.
Don't worry about deciding exactly which documents apply to you before you call. The objective is simply to get organized.
Pre-Approval vs. Loan Estimate: One Important Difference
A pre-approval letter should not be confused with a Loan Estimate.
The CFPB explains that consumers generally need to provide six pieces of information to trigger a Loan Estimate: name, income, Social Security number, property address, estimated property value and desired loan amount. The lender generally must then provide the Loan Estimate within three business days.
A Loan Estimate allows you to evaluate estimated rates, payments, closing costs and other loan terms.
The CFPB recommends comparing mortgage offers rather than assuming the first option is automatically the best fit.
The Bottom Line
If you want to get mortgage pre-approved faster in 2026, preparation is usually more valuable than speed alone.
Gather your documents. Complete your application accurately. Disclose complications early. Avoid unnecessary financial changes. And start the financing conversation before you find the house.
A strong pre-approval isn't simply a piece of paper.
It's the beginning of your financing strategy.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Subscribe to Our Newsletter
New Released

Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!

"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.