📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


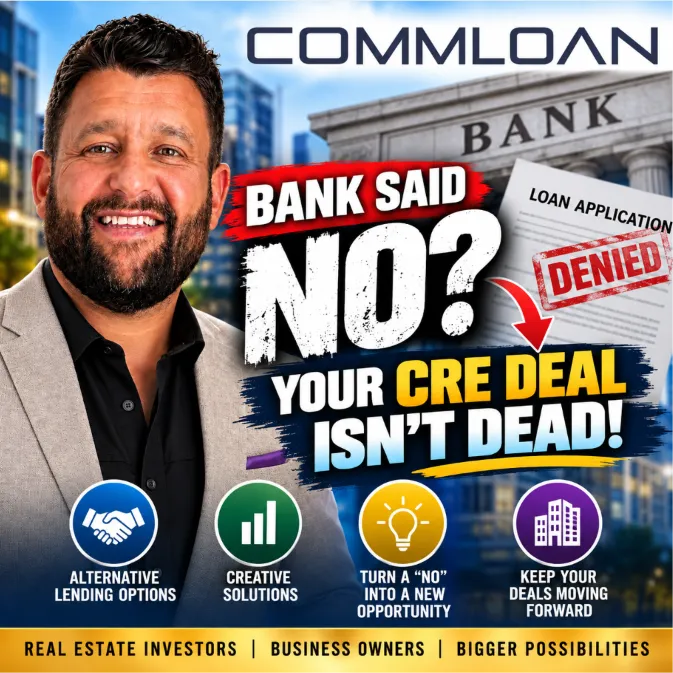
🏦 How to Win CRE Financing Business From Banks That Say No: Turn Declined Loans Into Opportunities 🚀
🏦 How to Win CRE Financing Business From Banks That Say No: Turn Declined Loans Into Opportunities 🚀
💰 Bank Declined Your Commercial Real Estate Loan? How Alternative CRE Financing Can Save the Deal 🔑
________________________________________________________________________________
How to Win CRE Financing Business From Banks That Say No
A commercial bank declining a real estate loan does not necessarily mean the transaction is a bad deal. Sometimes, it simply means the financing request does not fit that particular bank's lending guidelines.
For commercial real estate investors, business owners, and mortgage professionals, understanding this distinction can create significant opportunities.
Every day, banks decline commercial real estate financing requests because of loan-to-value restrictions, debt service coverage requirements, property conditions, concentration limits, or internal credit policies.
But here's the important point:
A bank's inability to approve a commercial loan does not automatically mean another lender cannot finance the transaction.
This is where commercial mortgage brokers, capital advisors, and alternative lending platforms can provide substantial value.
Through the CommLoan Empower Program, commercial real estate financing professionals can evaluate opportunities across a broad lender marketplace and help borrowers explore financing structures that traditional banks may not offer.
Why Banks Decline Commercial Real Estate Loans
Before pursuing alternative commercial real estate financing, it is essential to understand why the original lender declined the request.
1. Debt Service Coverage Ratio (DSCR) Is Too Low
Banks typically require sufficient property cash flow to support the proposed debt payments.
For example, a lender requiring a 1.25x DSCR wants the property's qualifying net operating income to cover annual debt service by at least 125%.
Consider a property generating $150,000 in annual NOI.
At a 1.25x minimum DSCR:
$150,000 ÷ 1.25 = $120,000
The property's maximum annual debt service under that requirement would be $120,000.
If the requested loan requires $140,000 in annual payments, the bank may decline the transaction or reduce the loan amount.
An alternative lender may evaluate the transaction differently, particularly when the property has a credible business plan, improving occupancy, or significant equity.
However, alternative financing does not eliminate the need for a realistic repayment strategy.
2. The Property Does Not Meet Occupancy Requirements
Many banks prefer stabilized commercial properties with predictable income.
Properties with significant vacancy can create challenges, including:
·Insufficient current cash flow
·Uncertainty regarding future lease-up
·Increased operating expenses
·Tenant rollover exposure
·Difficulty establishing sustainable property value
For example, a 60%-occupied multifamily property may not qualify for conventional permanent financing.
However, a bridge lender may consider the transaction when the borrower has adequate liquidity, a realistic renovation and lease-up strategy, and a credible refinancing or sale exit.
The opportunity is not simply finding a lender willing to accept vacancy. It is matching the property's business plan with the appropriate capital structure.
3. The Bank Has Reached Its Lending Concentration Limits
Commercial banks manage exposure across geographic markets, property types, industries, and individual borrowers.
A bank may have reached its internal lending limit for multifamily, hospitality, office, or construction financing.
In these situations, the loan may be financially sound, but the bank cannot add more exposure within that category.
This creates a potential referral opportunity for commercial mortgage professionals who have access to lenders with different portfolio objectives.
4. The Borrower Does Not Meet Traditional Underwriting Requirements
Traditional lenders may evaluate borrowers based on personal credit, liquidity, net worth, global cash flow, and historical operating performance.
Challenges can arise when borrowers have:
·Complex ownership structures
·Limited operating history
·Recent business acquisitions
·Nontraditional income sources
·High existing leverage
·Significant but illiquid assets
Some private credit, debt fund, and other specialized lenders may emphasize property-level collateral, sponsorship, and the business plan differently.
Nevertheless, borrower creditworthiness, liquidity, and repayment capacity remain important.
5. The Loan Request Does Not Fit the Bank's Product Offering
Not every lender finances every property type or transaction structure.
A bank focused on stabilized commercial properties may not offer financing for heavy renovations, ground-up construction, transitional assets, or short-term bridge transactions.
A financing request can be declined because the bank lacks the appropriate product rather than because the underlying transaction is inherently unfinanceable.
The Opportunity: Turn Bank Declines Into Commercial Financing Referrals
For commercial mortgage brokers and capital advisors, declined bank loans can represent a valuable source of business.
Banks frequently encounter borrowers they would like to help but cannot accommodate under their current credit policies.
Instead of losing the relationship entirely, a banker may be able to introduce the borrower to a qualified financing professional, subject to the bank's policies and the borrower's authorization.
A successful referral relationship should create value for three parties.
Participant | Potential benefit |
Bank relationship manager | Helps the customer explore another financing path |
Commercial mortgage broker | Gains an opportunity to structure and place a loan |
Borrower | Receives access to additional financing alternatives |
The most productive relationships are built around solving financing problems, protecting borrower confidentiality, and maintaining professional trust.
Five Strategies for Winning CRE Financing Referrals From Banks
Strategy 1: Build Relationships With Commercial Bankers
Develop relationships with commercial loan officers, business bankers, credit officers, and relationship managers.
Focus on institutions serving commercial real estate investors and business owners.
Instead of simply asking for referrals, explain the types of financing challenges you can help evaluate.
For example:
A banker may be unable to finance a partially occupied retail property because it does not meet the bank's stabilization requirements.
A commercial mortgage advisor could evaluate whether a bridge loan provides a feasible path toward lease-up and eventual permanent financing.
The goal is to become a trusted resource for transactions that fall outside the bank's lending appetite.
Strategy 2: Understand the Reason for the Decline
Not all declined loans are equally attractive opportunities.
Before approaching another lender, identify the underlying issue.
Was the request declined because of DSCR, LTV, borrower credit, property condition, concentration limits, or the loan's intended use?
The answer determines which lender categories may be appropriate.
For example, a loan declined because of bank concentration limits may be a stronger conventional lending candidate than a loan declined because the property cannot generate sufficient cash flow under reasonable assumptions.
Strategy 3: Develop Expertise in Alternative CRE Financing
Commercial mortgage professionals should understand multiple lending structures.
These may include:
·Bridge loans
·Private credit and debt fund financing
·SBA 7(a) and 504 loans for eligible businesses
·Commercial construction financing
·Multifamily financing
·CMBS loans
·Agency multifamily programs
·Owner-occupied commercial real estate loans
·Portfolio lending
·Specialized property financing
Each program has different underwriting requirements, documentation standards, pricing, and exit considerations.
The ability to identify an appropriate financing structure is more valuable than simply presenting a long list of lenders.
Strategy 4: Build a Complete Financing Package
A declined loan is not necessarily improved by submitting the same incomplete package to additional lenders.
A professional financing package should generally include the property description, current rent roll, trailing operating statements, borrower financial information, sources and uses, business plan, requested loan structure, and proposed repayment or exit strategy.
The precise documentation depends on the transaction.
A strong package helps lenders evaluate the opportunity efficiently and can reduce unnecessary back-and-forth.
Strategy 5: Protect the Bank's Relationship With the Borrower
One of the biggest concerns bankers may have when making outside referrals is losing their customers.
Commercial mortgage professionals can address this concern by establishing clear expectations.
When appropriate, explain that the objective is to solve the immediate financing challenge, not solicit unrelated banking relationships.
For example, a borrower might obtain a short-term bridge loan while continuing to maintain deposits, treasury services, or other relationships with the referring bank.
Future permanent financing could potentially return to the bank once the property qualifies, subject to lender approval.
How the CommLoan Empower Program Helps Evaluate Financing Alternatives
The CommLoan Empower Program provides commercial real estate financing professionals access to technology and a broad network of lending relationships.
Through CommLoan's CUPID™ platform, advisors can evaluate commercial financing opportunities across a marketplace of more than 700 lenders.
The platform supports a more structured approach to evaluating potential financing solutions.
Rather than relying exclusively on one bank's credit box, advisors can compare potential financing options across multiple lending categories.
This can be particularly useful for borrowers whose transactions involve transitional properties, unusual financing structures, or specialized commercial assets.
The objective is not to guarantee financing. It is to improve lender alignment, evaluate realistic options, and help borrowers make informed capital decisions.
Example: When a Bank Decline Becomes a Financing Opportunity
Consider a hypothetical commercial real estate investor purchasing a partially occupied retail center.
Illustrative transaction
Purchase price
$2,000,000
Requested loan
$1,400,000
Current occupancy
65%
Target occupancy
90%
The borrower's bank declines the request because current property cash flow does not meet its minimum DSCR requirement.
A commercial mortgage advisor reviews the transaction and determines that a bridge lender might consider the property if the borrower can demonstrate sufficient equity, liquidity, leasing demand, and a viable stabilization plan.
The financing strategy could include a short-term bridge loan, funding for eligible property improvements, a structured lease-up period, and a potential refinance into permanent debt once the property meets underwriting requirements.
This strategy may involve higher financing costs, shorter maturities, and greater execution risk than conventional bank financing.
The borrower must evaluate whether the anticipated improvements justify those risks.
The lesson: A decline from one lender may identify a financing mismatch rather than the end of the transaction.
How Borrowers Should Respond When Their Bank Says No
If your bank declines a commercial real estate loan, avoid immediately submitting the same application to numerous lenders.
Instead, request a clear explanation of the decline, confirm whether the issue can be resolved, and reassess the transaction's cash flow, leverage, collateral, and repayment strategy.
Then work with a qualified commercial mortgage advisor who understands which lenders may be appropriate for the specific transaction.
Sometimes the solution is a different lender. Other times, it requires additional equity, a smaller loan, improved operating performance, or a revised business plan.
And in some situations, the prudent decision is not to proceed.
Frequently Asked Questions
Can I get a commercial real estate loan after my bank declines me?
Possibly. Another lender may have different underwriting guidelines, property preferences, or loan products. Approval depends on the transaction's financial strength and lender requirements.
Are alternative commercial loans more expensive?
They can be. Bridge loans and private credit often carry higher rates, fees, and shorter terms than conventional bank financing. Borrowers should compare total financing costs and exit risks.
Can a commercial mortgage broker help with low-occupancy properties?
Yes. A broker can assess whether bridge, transitional, or value-add financing may be available. Lenders generally expect a credible stabilization strategy and sufficient borrower resources.
Can banks refer declined loans to commercial mortgage brokers?
They may, subject to institutional policies, applicable law, borrower consent, and conflict-of-interest requirements. Referral arrangements and compensation must comply with applicable rules.
What is the biggest mistake after a commercial loan decline?
Assuming that every lender will evaluate the request the same way—or that another lender can overcome a fundamentally unworkable transaction without changing its structure.
Final Thoughts: A Bank's No May Be the Beginning of a Better Financing Strategy
Commercial real estate financing is not a one-size-fits-all business.
Banks, credit unions, debt funds, private lenders, and government-supported lending programs serve different borrower needs.
For commercial real estate investors and business owners, a declined bank loan may create an opportunity to reassess the financing strategy.
For commercial mortgage professionals, developing trusted banking relationships and understanding alternative financing structures can create a valuable referral channel.
The key is identifying financeable transactions, matching them with suitable lenders, and providing borrowers with transparent guidance.
Work With Bill Rapp, CCIM — CommLoan Empower Program
If your bank declined a commercial real estate loan—or you are a banker with a transaction that falls outside your institution's guidelines—let's evaluate the available options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Subscribe to Our Newsletter
New Released
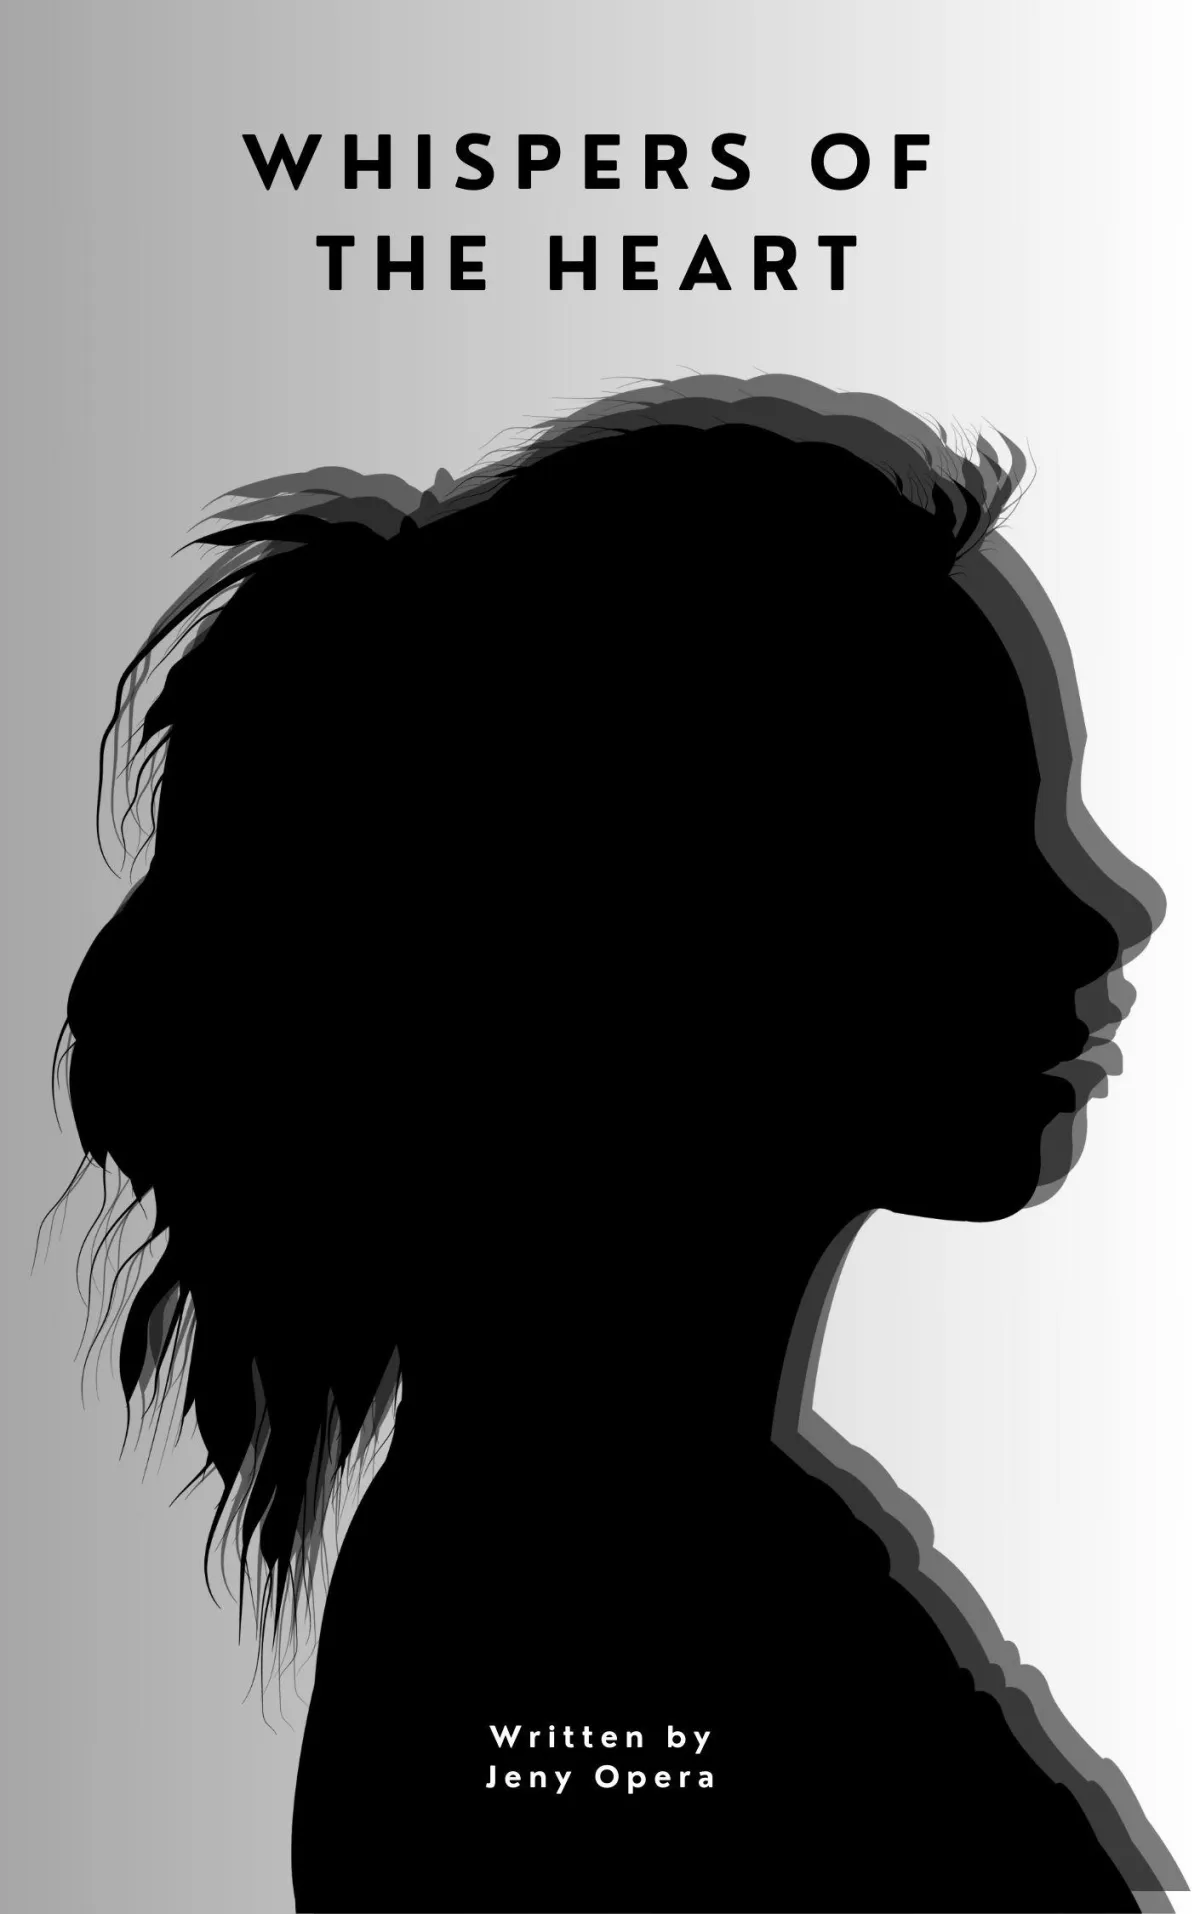
Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
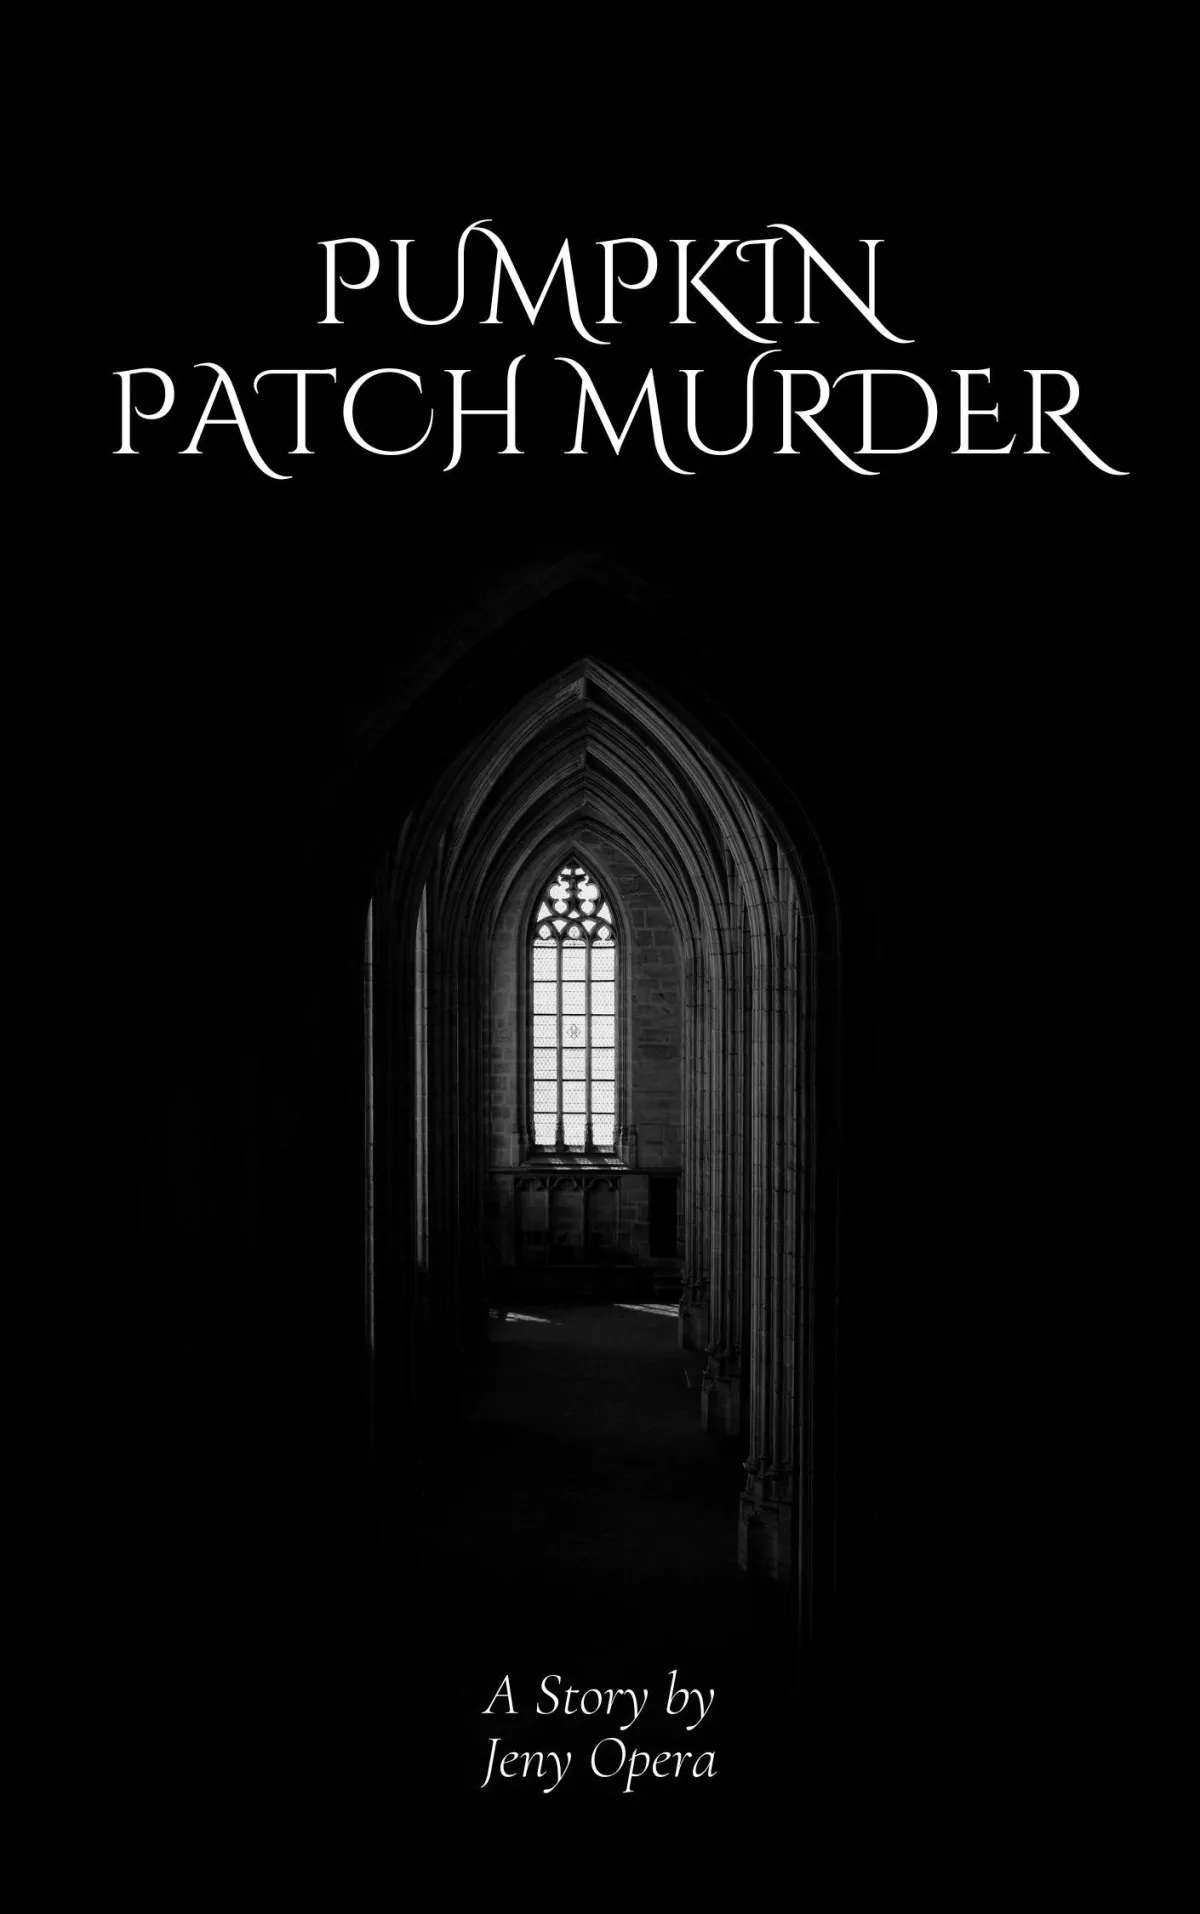
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
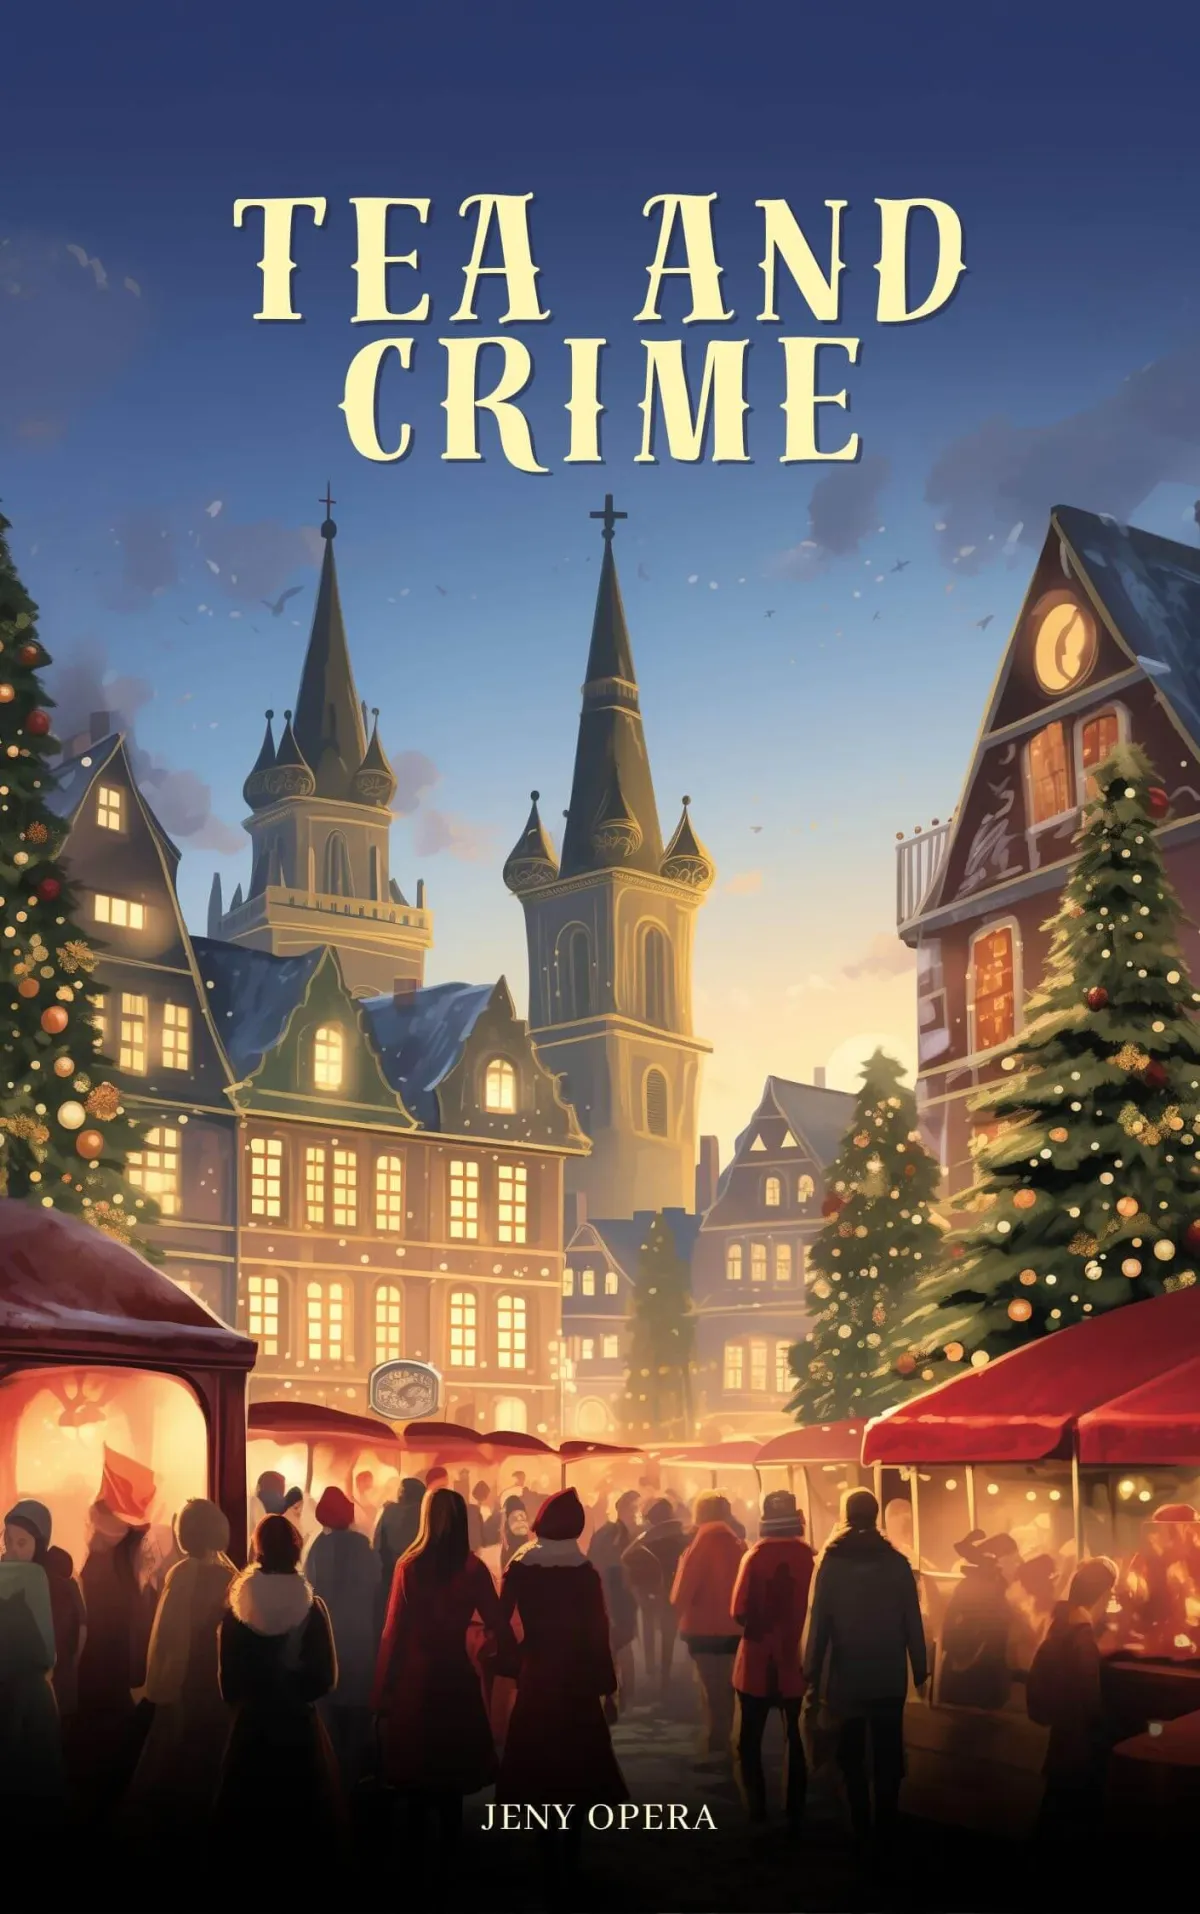
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
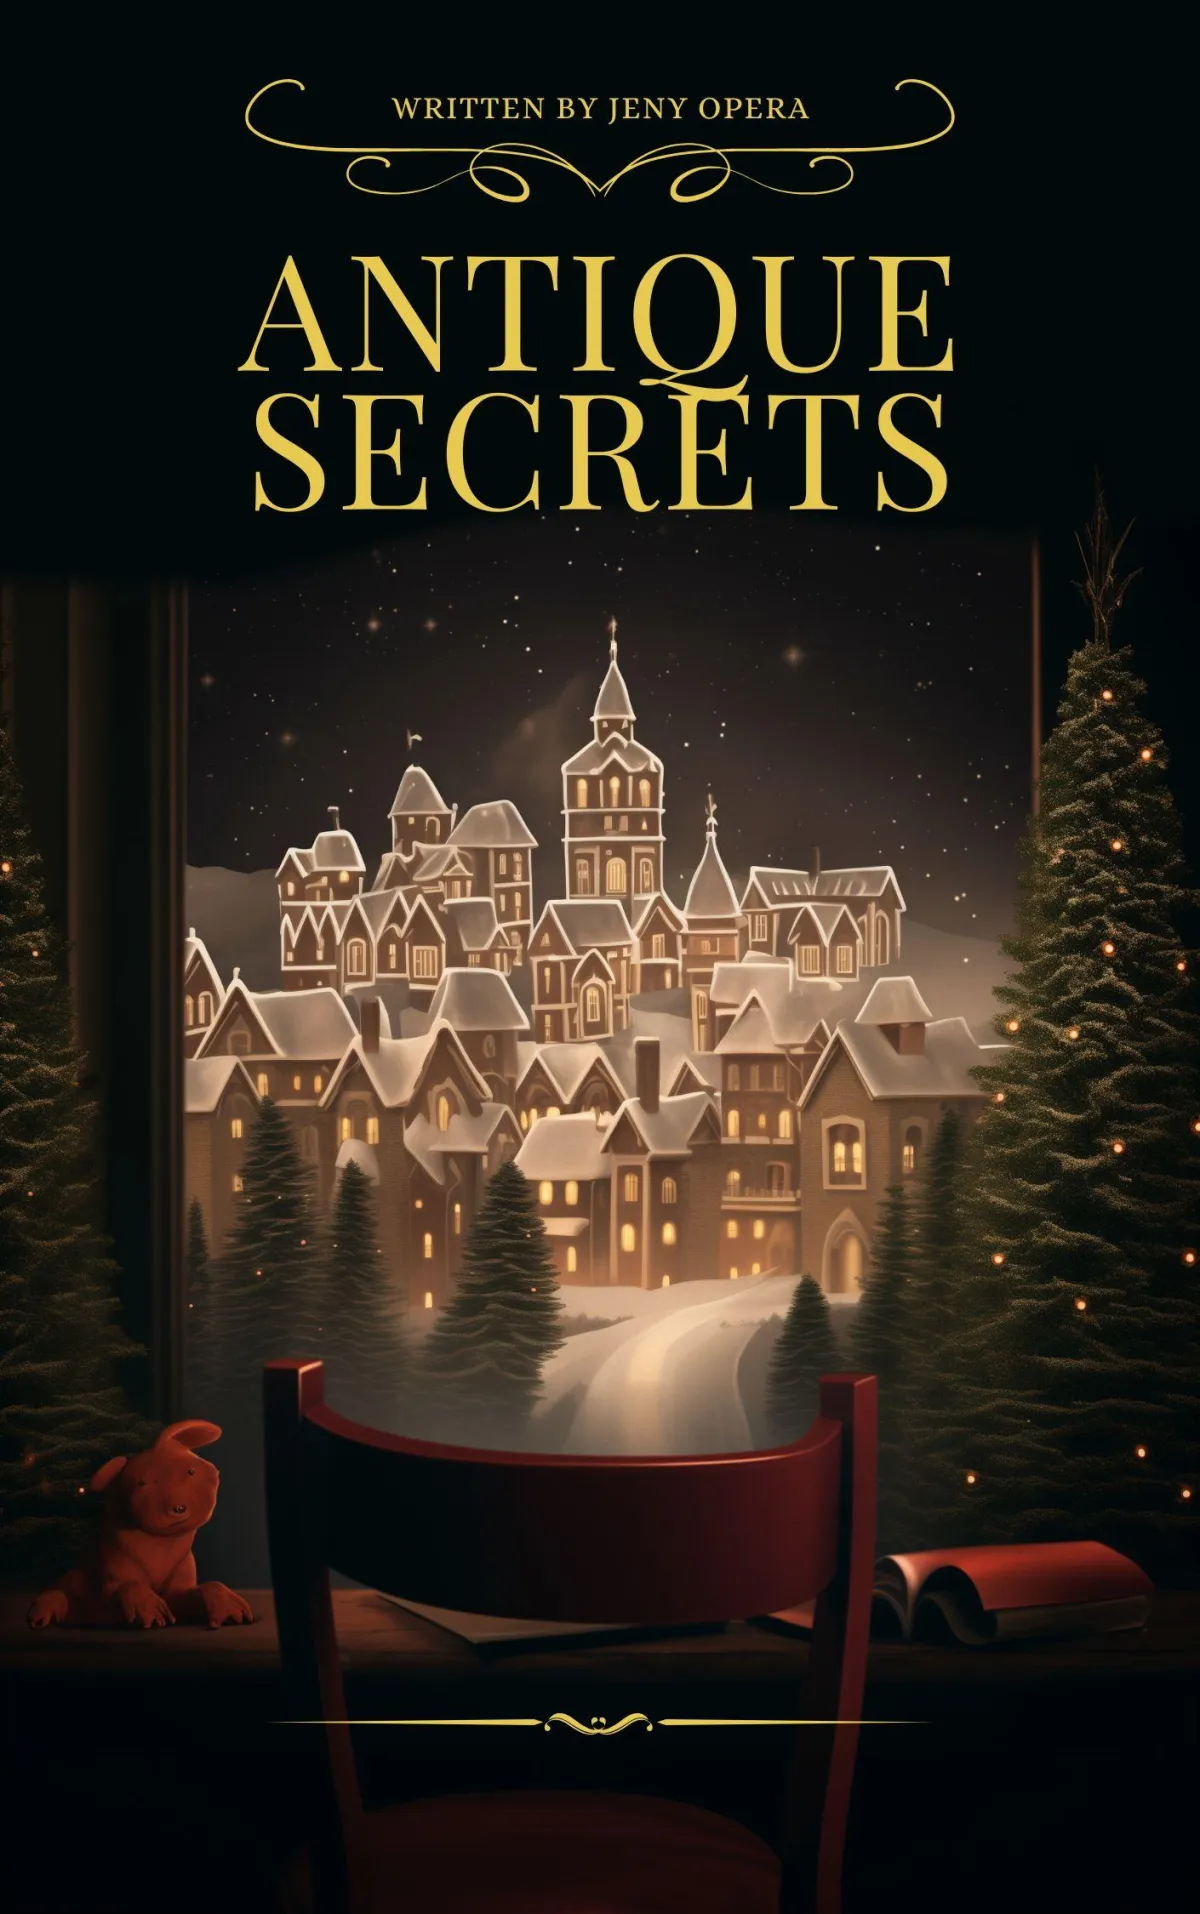
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!
"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.