📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
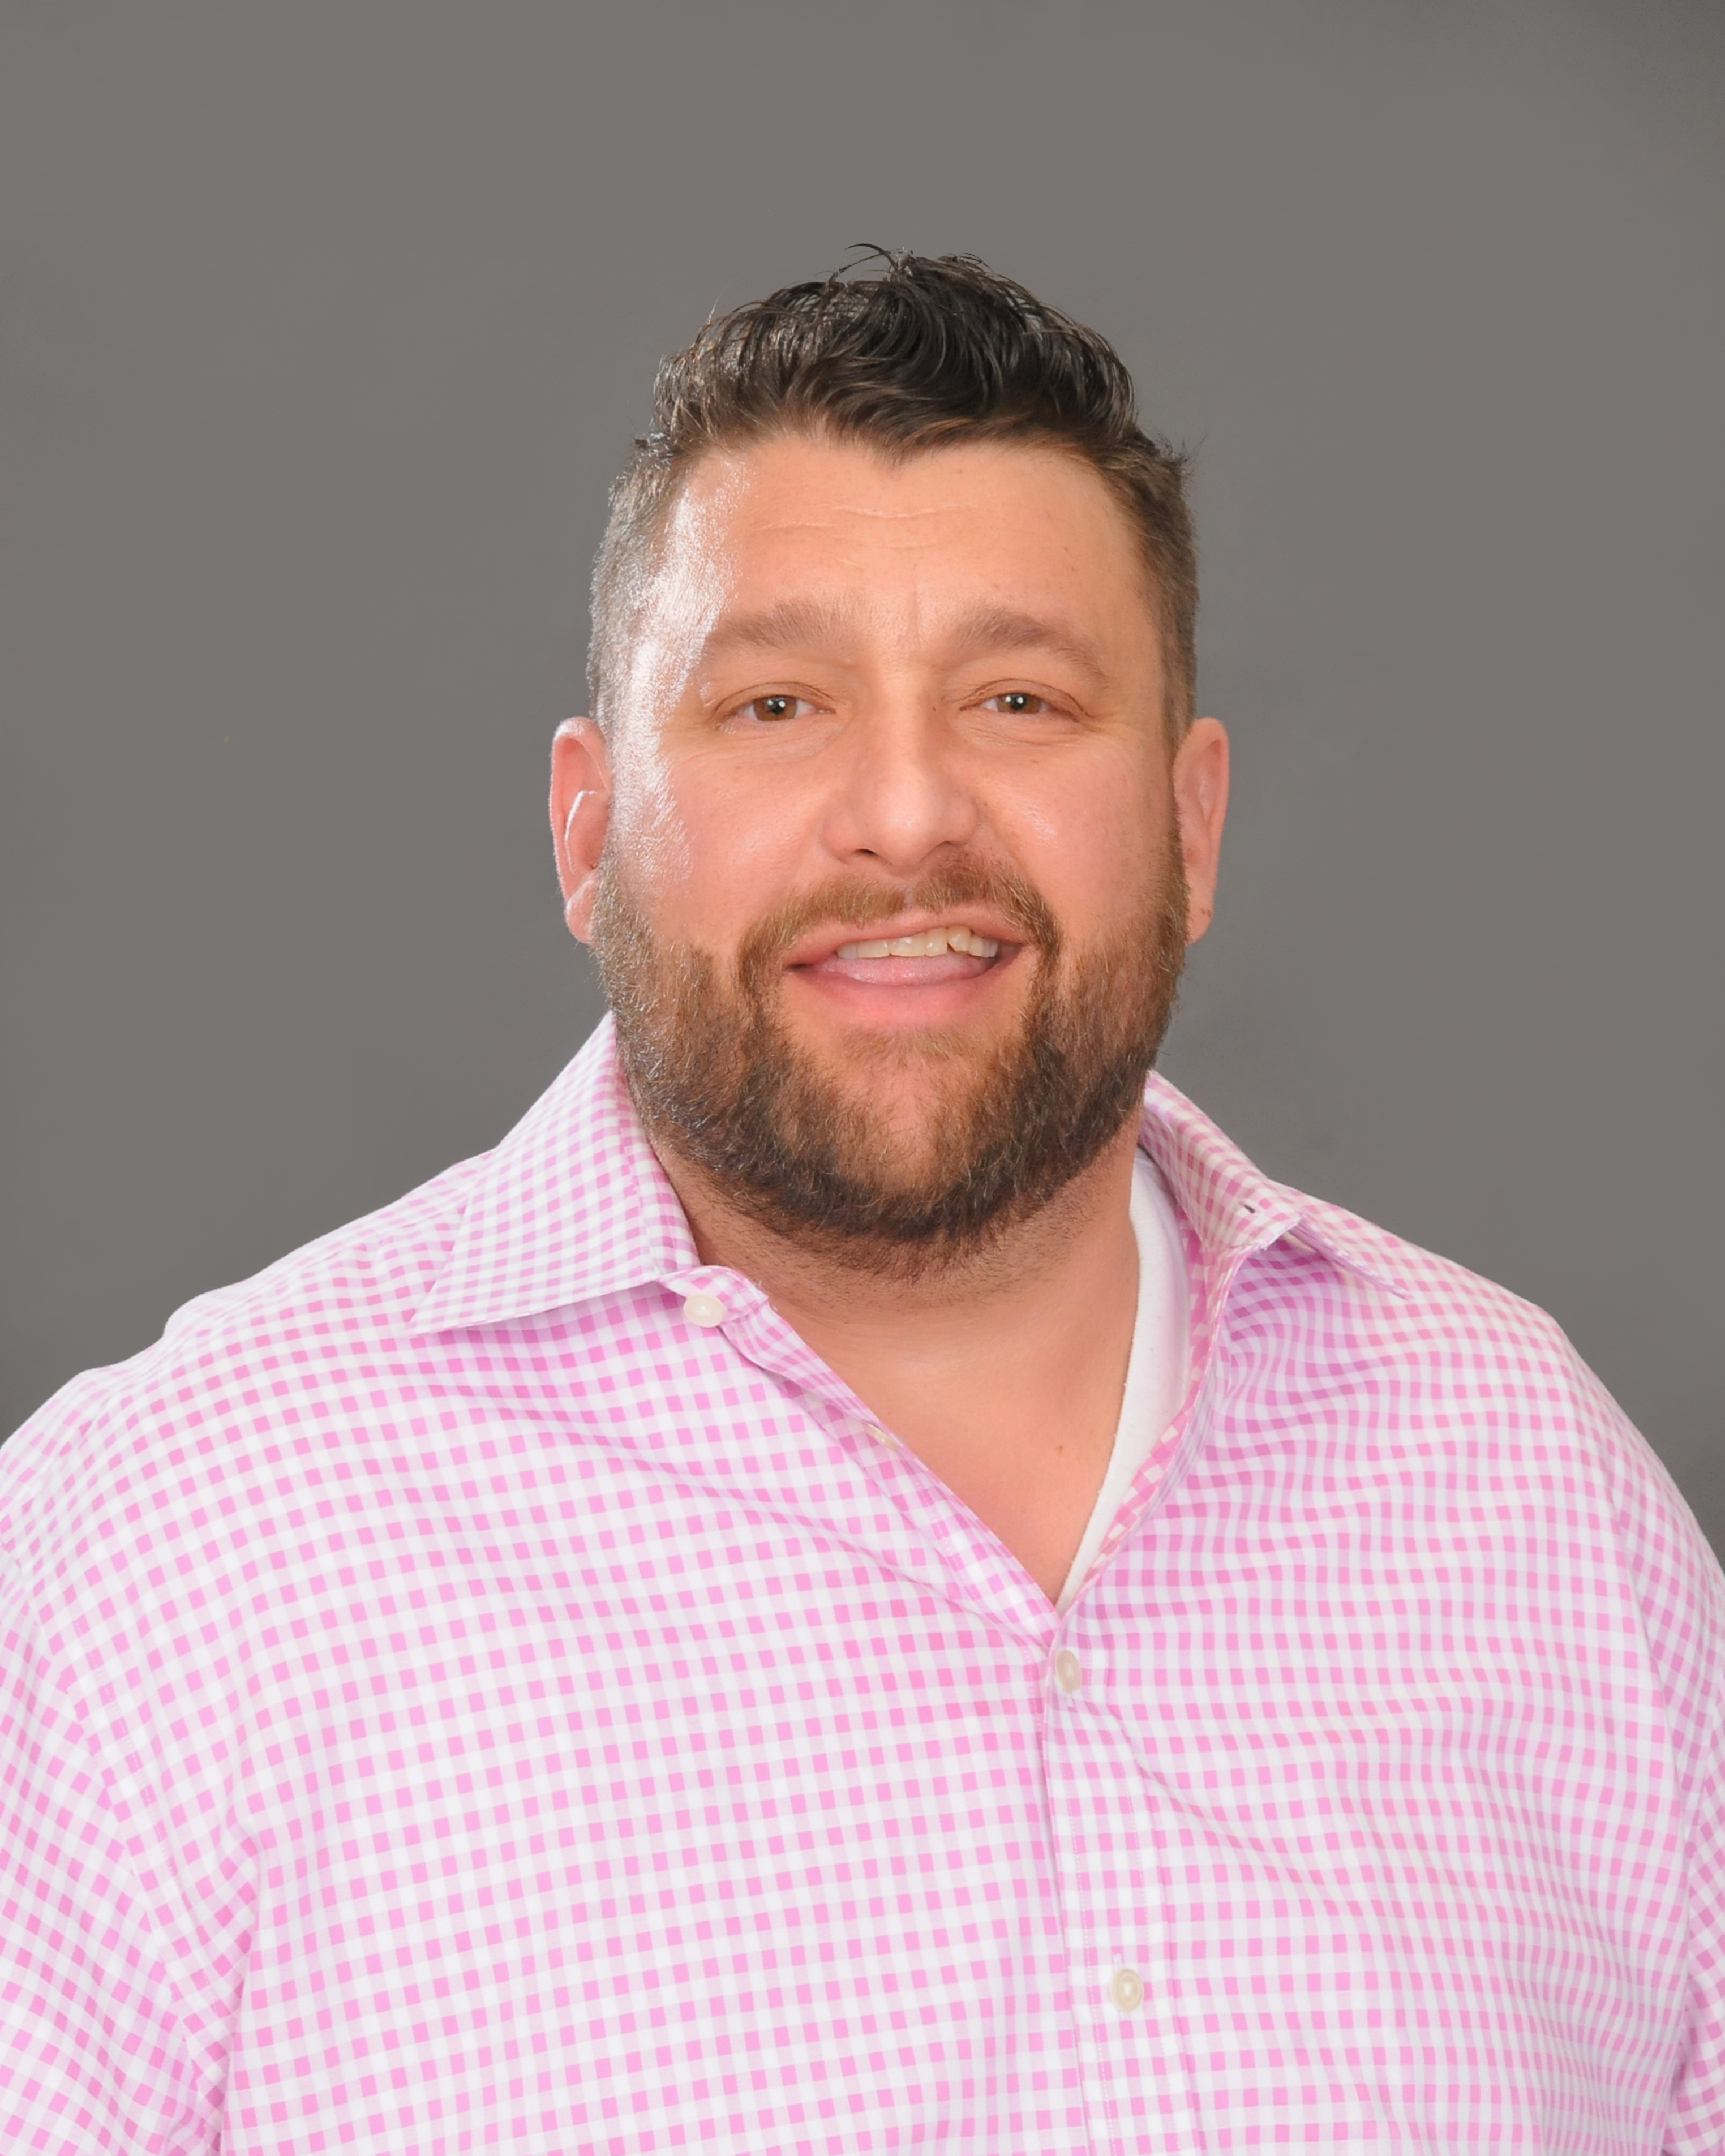
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


🏡 “Marry the House, Date the Rate”: Smart Mortgage Strategy or Expensive Mistake? 💸
🏡 “Marry the House, Date the Rate”: Smart Mortgage Strategy or Expensive Mistake? 💸
💰 Buy Now, Refinance Later? The Hidden Risks of “Marry the House, Date the Rate” 🏠
________________________________________________________________________________
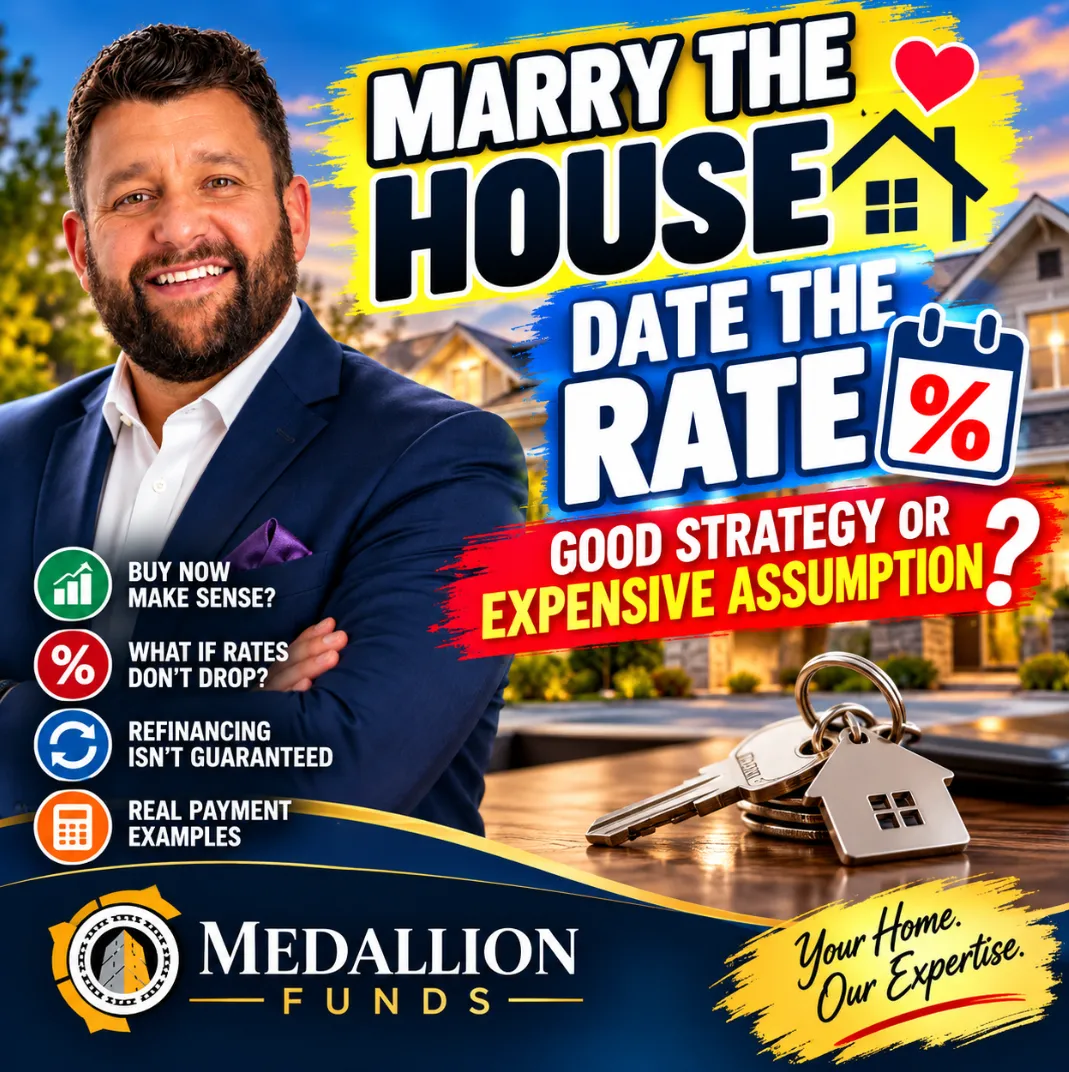
“Marry the House, Date the Rate”: Good Strategy or Expensive Assumption?
Buying the right home matters. But betting your financial future on lower mortgage rates could be a costly mistake.
If you've been shopping for a home recently, you've probably heard the popular real estate saying:
“Marry the house, date the rate.”
The concept sounds simple: Buy the home you love today, even if mortgage interest rates are higher than you'd prefer, and refinance when rates eventually decline.
It's an appealing argument, especially for buyers tired of waiting for better market conditions.
But there's one important problem.
What happens if mortgage rates don't come down?
Or what if rates decline, but your financial situation or property value prevents you from refinancing?
At Medallion Funds, I believe in helping homebuyers understand not just whether they can qualify for a mortgage, but whether their financing strategy makes sense over the long term.
Let's examine when this popular advice works, when it doesn't, and how to make a smarter homebuying decision.
What Does “Marry the House, Date the Rate” Actually Mean?
The phrase encourages homebuyers to prioritize finding the right property rather than waiting indefinitely for lower mortgage rates.
The theory is built around three assumptions:
1.You can purchase a home you love today.
2.Mortgage rates may decline in the future.
3.You can refinance your existing mortgage into a lower interest rate when conditions improve.
There is some logic behind this strategy.
You generally cannot change a home's location, neighborhood, lot size, or many of its fundamental characteristics.
However, your mortgage financing may be modified through refinancing.
The critical distinction is that refinancing is an opportunity, not a guarantee.
Why Buying a Home Now Can Make Sense
Waiting for the perfect mortgage rate isn't always the best financial decision.
Homebuyers who delay purchasing may encounter several challenges.
1. Home Prices May Continue Rising
Even when mortgage rates are elevated, home prices can increase in markets with strong demand and limited housing inventory.
A buyer waiting for lower rates could end up paying more for the same type of property.
For example, a $400,000 home appreciating by 5% would cost $420,000 one year later.
Of course, appreciation isn't guaranteed. Property values can also decline.
The key is evaluating the housing market alongside your personal financial circumstances.
2. Lower Rates Could Bring More Competition
If mortgage rates decline significantly, additional buyers may enter the market.
Increased competition can lead to multiple offers, reduced seller concessions, and potentially higher home prices.
In some situations, purchasing when competition is lighter could create negotiating opportunities.
3. You May Be Able to Negotiate Seller Concessions
Depending on the local market and loan program, sellers may be willing to contribute toward closing costs or mortgage rate buydowns.
These concessions can reduce upfront expenses or monthly payments.
However, the value of a concession should always be evaluated against the purchase price and total financing costs.
The Biggest Risk: Assuming You Can Refinance Later
This is where the “marry the house, date the rate” strategy can become expensive.
Refinancing requires more than simply calling your lender when interest rates decline.
You generally must qualify for a new mortgage under the lender's guidelines at that time.
Several factors can affect your ability to refinance.
Your Home's Value Could Decline
If property values fall, you may have less equity than anticipated.
That could affect your loan-to-value ratio and refinancing options.
Your Income or Employment Could Change
A job loss, career transition, reduced business income, or additional debt could affect your ability to qualify.
This is particularly important for self-employed borrowers and those with variable income.
Your Credit Profile Could Change
Your credit score, payment history, and debt obligations can influence the mortgage products and pricing available to you.
Refinancing Costs Money
A refinance may involve lender fees, title charges, appraisal expenses, and other settlement costs.
Even when certain costs are rolled into the new loan, they still affect the economics of the transaction.
The bottom line: Never purchase a home that only becomes affordable if you refinance later.
The Numbers: What Could Refinancing Actually Save?
Consider a hypothetical home purchase with the following assumptions:
Illustrative mortgage scenario
Purchase price
$400,000
Down payment (10%)
$40,000
Loan amount
$360,000
Loan term
30 years
Explore a potential refinance rate
Hypothetical new interest rate
6.75%
Original P&I payment
$2,335
New P&I payment
$2,335
Monthly P&I change versus original
$0
Illustration assumes refinancing the original $360,000 balance into a new 30-year fixed loan. Excludes closing costs, taxes, insurance, mortgage insurance, and the effects of principal already repaid. Not a rate quote or financing offer.
A lower interest rate could produce meaningful monthly savings.
But the comparison is incomplete without considering refinance costs, the remaining mortgage balance, and whether a new 30-year term extends your repayment period.
Don't Forget the Refinance Break-Even Point
Before refinancing, borrowers should calculate how long it will take for monthly savings to recover their refinancing costs.
For example:
·Refinance closing costs: $5,000
·Monthly payment savings: $250
·Break-even period: 20 months
The calculation is:
\[ \$5,000 \div \$250 = 20\text{ months} \]
If you plan to sell the property in 12 months, refinancing under these assumptions might not make financial sense.
This simplified calculation also excludes changes in loan amortization, mortgage insurance, taxes, and the time value of money.
A comprehensive mortgage analysis should evaluate the total cost of borrowing, not just the monthly payment.
What If Mortgage Rates Stay Elevated for Five Years?
This is the question every buyer should consider.
Imagine purchasing a home with the expectation of refinancing within 12 to 24 months.
But instead, mortgage rates remain relatively high for the next five years.
Could you comfortably make the original mortgage payment throughout that period?
Would you still have adequate savings for emergencies, repairs, and other financial priorities?
Would the home continue to meet your family's needs?
If the answer is yes, purchasing today may still make sense.
If the answer is no, you're potentially relying on an uncertain future event to support a financial obligation you are making today.
A good mortgage strategy should work even if rates never decline.
Alternative Strategies to Consider Before Buying
Rather than relying entirely on future refinancing, buyers can explore financing alternatives from the beginning.
Strategy | Potential benefit | Important consideration |
Fixed-rate mortgage | Predictable principal and interest payments | Higher initial rate may mean higher payments |
Permanent rate buydown | Lower rate for the loan term | Upfront points and break-even period |
Temporary rate buydown | Lower payments during the initial period | Payment rises to the full note payment after buydown expires |
Adjustable-rate mortgage | May offer a lower initial rate | Future rate and payment adjustments |
Larger down payment | Lower loan amount and potentially better terms | Reduces available cash reserves |
Seller concessions | May offset eligible closing costs | Subject to loan-program limits |
At Medallion Funds, we can evaluate options across applicable conventional, FHA, VA, jumbo, and other mortgage programs.
The objective isn't simply finding the lowest advertised rate.
It's identifying the financing structure that best supports your overall financial strategy.
Should First-Time Homebuyers Follow This Advice?
First-time buyers should approach the “marry the house, date the rate” concept with particular caution.
Purchasing a home introduces financial obligations beyond the mortgage payment, including property taxes, homeowners insurance, maintenance, repairs, and potentially HOA dues.
For buyers in Texas, property taxes and insurance can represent a substantial portion of the total housing payment.
A mortgage that appears affordable based only on principal and interest may become uncomfortable when all ownership expenses are included.
Before buying, establish a realistic housing budget based on your complete financial picture.
When “Marry the House, Date the Rate” Can Be a Smart Strategy
The strategy may be reasonable when you:
·Can comfortably afford the current payment without refinancing.
·Have stable income and adequate emergency reserves.
·Plan to own the home for several years.
·Are purchasing a property that meets your long-term needs.
·Understand that refinancing may never become financially advantageous.
Under these circumstances, a future refinance becomes a potential financial benefit rather than a necessity.
That's a very different proposition.
When It Could Become an Expensive Mistake
The strategy deserves reconsideration when you are stretching your budget to purchase, counting on lower payments within a specific period, or using a temporary rate buydown without preparing for the higher payment that follows.
It can also be risky if you have limited cash reserves, expect significant changes to your income, or anticipate selling the property in the near future.
The purchase should stand on its own financial merits.
Frequently Asked Questions
Will mortgage rates definitely go down?
No. Mortgage rates respond to economic conditions, inflation expectations, bond markets, and other factors. No one can guarantee when rates will decline or by how much.
Can I refinance immediately if rates drop?
Possibly, depending on the loan program, lender requirements, seasoning rules, equity, credit, and financial qualifications. Some loans and refinance transactions have additional restrictions.
Is it better to buy now or wait for lower rates?
There is no universal answer. Compare your current housing expenses, expected ownership costs, local home prices, available inventory, financial stability, and long-term plans.
How much lower should my interest rate be before refinancing?
There is no fixed rule. Evaluate closing costs, monthly savings, the new loan term, the remaining loan balance, and your expected time in the home.
Can I refinance if my home loses value?
It depends on the loan type, available equity, and applicable refinance programs. Lower property values may limit your options.
Final Thoughts: Marry the House, but Respect the Mortgage
The idea behind “marry the house, date the rate” isn't inherently wrong.
Buying the right property and refinancing when financially advantageous can be an effective long-term strategy.
But treating lower future mortgage rates as a certainty is a dangerous assumption.
My recommendation is simple:
Buy the house when the property, payment, and financial strategy make sense today. Consider refinancing later as a bonus, not the foundation of your decision.
At Medallion Funds, we help homebuyers evaluate mortgage programs, understand their options, and make informed financing decisions.
Whether you're buying your first home, moving up, or exploring refinancing opportunities, let's build a mortgage strategy around your goals.
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Subscribe to Our Newsletter
New Released

Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!

"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.