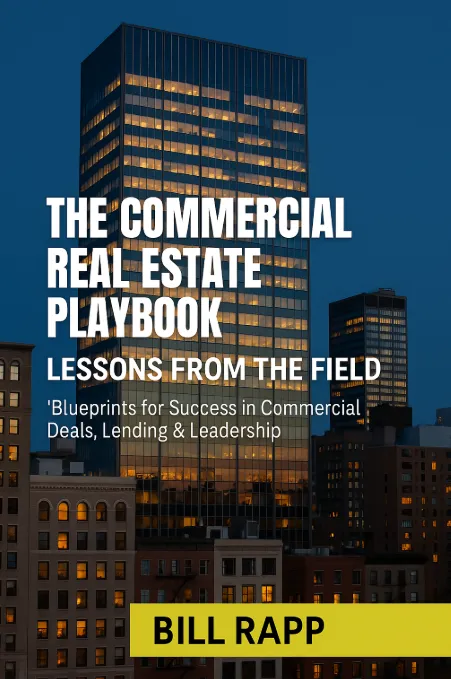
📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
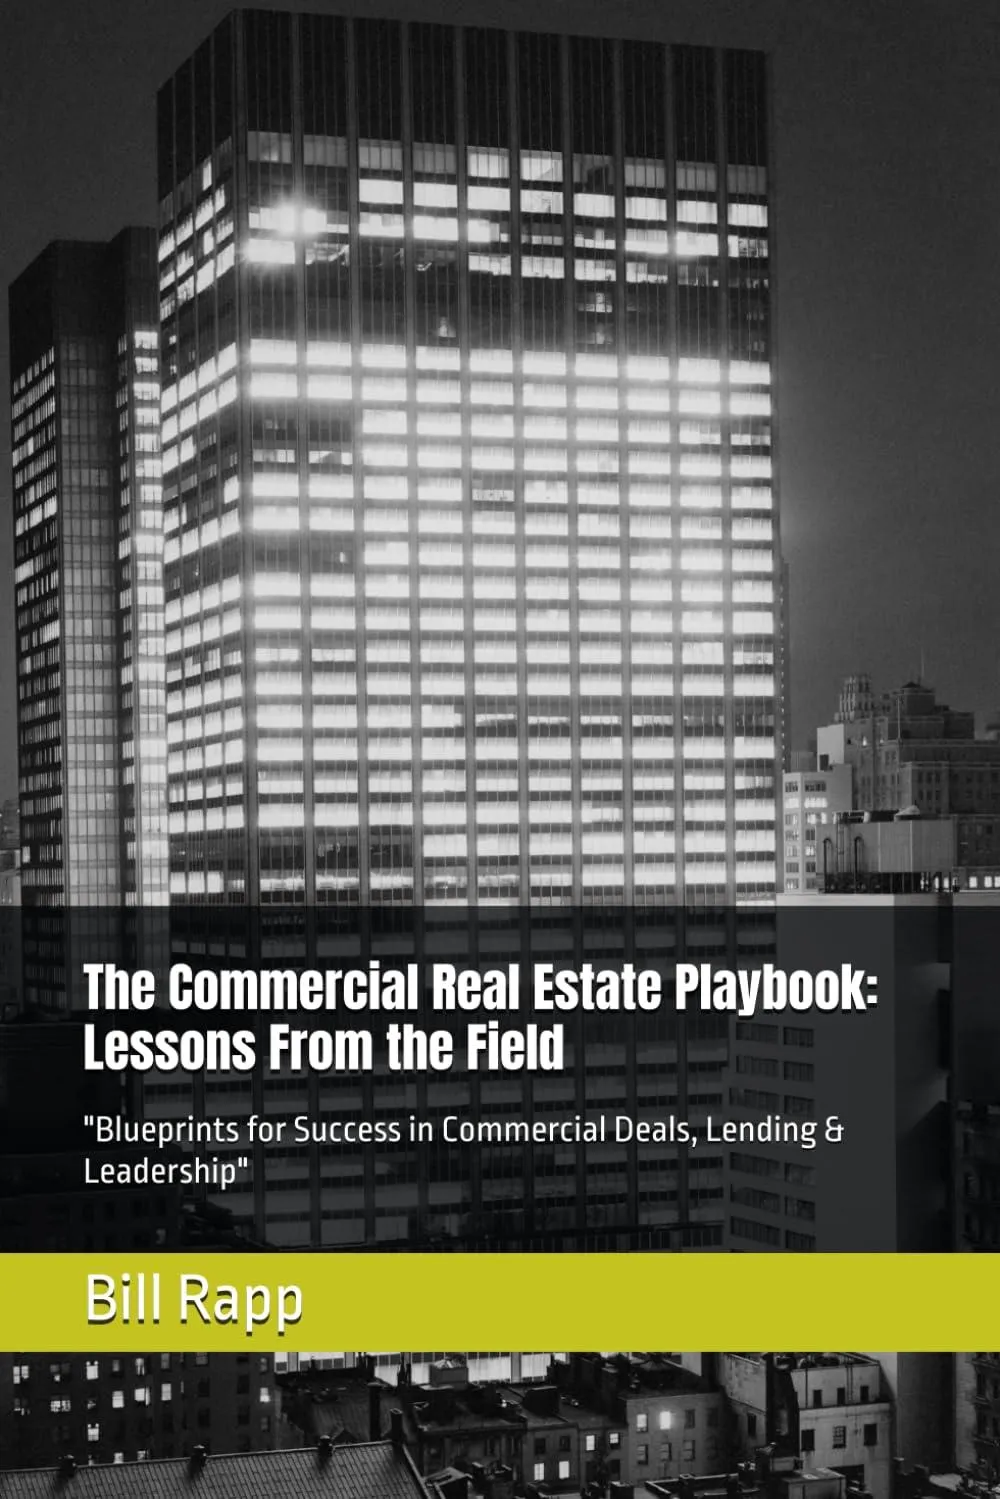
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


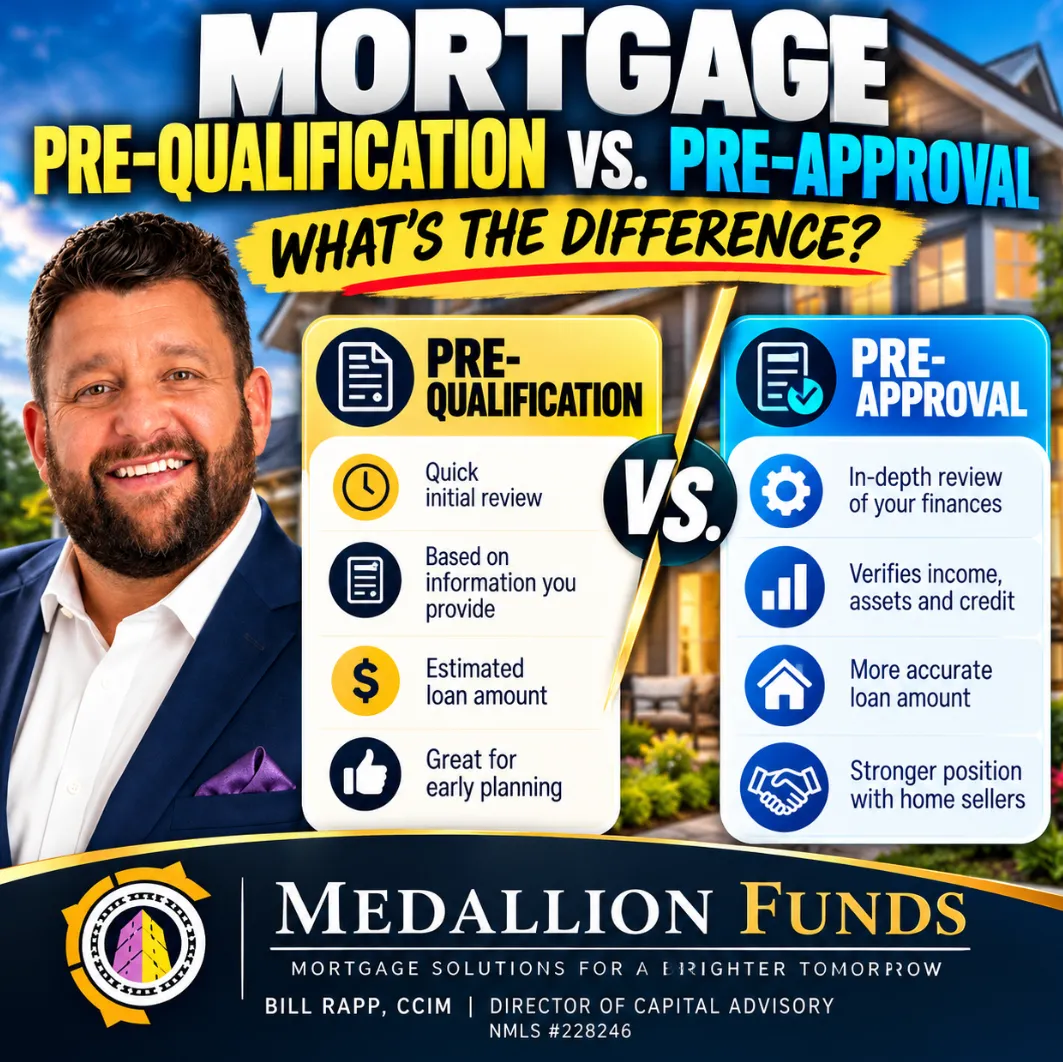
🏡 Mortgage Pre-Qualification vs. Pre-Approval: 7 Key Differences Every Homebuyer Should Know! 🔑
🏡 Mortgage Pre-Qualification vs. Pre-Approval: 7 Key Differences Every Homebuyer Should Know! 🔑
🚨 Pre-Qualified or Pre-Approved? Don't Make an Offer on a Home Until You Know the Difference! 🏠
________________________________________________________________________________
Mortgage Pre-Qualification vs. Pre-Approval: What's the Difference?
Meta Description: Learn the difference between mortgage pre-qualification and pre-approval, what lenders verify, and how to prepare to buy a home with confidence.
By Bill Rapp, CCIM | Director of Capital Advisory | Medallion Funds
Buying a home is one of the largest financial decisions most people will ever make. Before you start touring properties, however, there's an important question you need to answer:
Are you mortgage pre-qualified, or are you actually pre-approved?
These two terms are frequently used interchangeably, but they can represent very different levels of financial review.
Understanding the difference between mortgage pre-qualification and pre-approval can help you establish a realistic budget, avoid unnecessary delays, and potentially strengthen your offer when you find the right property.
At Medallion Funds, we help homebuyers evaluate mortgage options and prepare for the financing process so they can make informed decisions.
What Is Mortgage Pre-Qualification?
Mortgage pre-qualification is typically an initial assessment of how much money you may be able to borrow based on information you provide to a lender or mortgage broker.
The process often involves discussing:
·Your estimated annual income
·Your monthly debt obligations
·Your approximate credit profile
·Available savings and other assets
·Your anticipated down payment
·Your target home purchase price
Depending on the lender, pre-qualification may involve a soft credit inquiry, a more detailed credit review, or no credit check at all.
Advantages of Mortgage Pre-Qualification
1. Quick initial assessment
Pre-qualification can provide an early estimate of your borrowing capacity.
2. Helps establish a preliminary budget
Understanding your estimated purchasing power can help narrow your property search.
3. Identifies potential financing obstacles
A mortgage professional may identify issues involving income, credit, debt, or available funds before you begin making offers.
4. Useful for early financial planning
If you're considering purchasing a home several months from now, pre-qualification can help you develop a financing strategy.
Limitations of Pre-Qualification
Because pre-qualification may rely primarily on self-reported information, it does not necessarily confirm that you satisfy a lender's underwriting requirements.
Your actual mortgage eligibility could change once your financial documentation and credit history are reviewed.
Bottom line: Pre-qualification is a useful starting point, but it should not automatically be treated as a verified lending decision.
What Is Mortgage Pre-Approval?
Mortgage pre-approval generally involves a more detailed assessment of your financial qualifications.
During this process, a mortgage lender or broker typically reviews supporting information such as:
·Credit history and credit scores
·Employment and income documentation
·Bank statements and available assets
·Existing debts and financial obligations
·Down payment and closing cost funds
·Applicable mortgage program requirements
Some lenders also provide pre-approvals involving automated underwriting or an initial underwriter review.
However, the depth of verification varies by lender.
A pre-approval letter usually indicates that, based on the information reviewed, you appear eligible for financing up to a specified amount, subject to applicable conditions.
Why Mortgage Pre-Approval Matters
1. Greater confidence in your purchasing budget
A more comprehensive financial review can help identify the mortgage amount and loan structure that may fit your circumstances.
2. Stronger positioning with home sellers
A seller may view an offer accompanied by a credible pre-approval letter more favorably than an offer without evidence of financing preparation.
3. Earlier identification of underwriting issues
Income documentation, credit concerns, and asset requirements can sometimes be addressed before you're under contract.
4. Potentially smoother mortgage processing
Completing important verification steps early may reduce delays later, although it does not guarantee a faster closing.
5. Better loan program evaluation
Pre-approval provides an opportunity to assess conventional, FHA, VA, jumbo, and other applicable mortgage options.
Mortgage Pre-Qualification vs. Pre-Approval: Side-by-Side Comparison
Feature | Pre-Qualification | Pre-Approval |
Purpose | Preliminary borrowing estimate | More detailed financing assessment |
Income review | Often self-reported | Typically documented or verified |
Credit review | Varies by lender | Usually includes credit review |
Asset verification | Often limited | Typically more extensive |
Processing time | Often relatively quick | Depends on lender and documentation |
Seller confidence | Generally lower | Generally stronger |
Loan commitment | No | No |
Best use | Early planning | Preparing to make an offer |
Important: Neither pre-qualification nor pre-approval guarantees final mortgage approval.
7 Key Differences Every Homebuyer Should Understand
1. The Level of Financial Verification
Pre-qualification commonly begins with estimates. Pre-approval typically involves a more detailed review of your actual financial documentation.
2. Credit Review Requirements
Some pre-qualification processes use soft credit inquiries, while pre-approval commonly requires a hard credit inquiry.
A hard inquiry may have a temporary effect on your credit score. Ask your mortgage professional what type of inquiry will be performed.
3. Accuracy of Your Estimated Loan Amount
A pre-qualification estimate may change significantly when a lender verifies your income, debts, assets, and credit history.
Pre-approval generally provides a better-supported estimate, although it remains conditional.
4. Strength of Your Purchase Offer
In a competitive housing market, sellers may prefer buyers who have already completed a more substantial financing review.
A pre-approval letter can help demonstrate that you're taking the purchase seriously.
5. Mortgage Program Selection
Pre-qualification may identify potential financing options.
Pre-approval can provide a more detailed assessment of whether you appear to meet specific loan program requirements.
6. Potential Closing Delays
A more thorough review before making an offer may identify issues that otherwise would not surface until after the purchase contract is signed.
7. Readiness to Purchase
Pre-qualification is often appropriate when you're exploring the market.
Pre-approval is generally the better choice when you're preparing to make an offer.
How Much House Can You Afford?
One of the biggest mistakes homebuyers make is confusing the maximum mortgage amount they might qualify for with the amount they should comfortably spend.
Consider this hypothetical example:
A borrower receives a pre-approval indicating potential eligibility for a $450,000 home purchase.
However, after reviewing projected property taxes, homeowners insurance, mortgage insurance, and other expenses, the borrower determines that a $375,000 home better supports their financial goals.
The right purchase price isn't necessarily the highest amount a lender will approve.
At Medallion Funds, our objective is to help borrowers evaluate financing options within the context of their broader financial circumstances.
What Documents Do You Need for Mortgage Pre-Approval?
Although requirements vary by lender and loan program, many borrowers should be prepared to provide:
·Recent pay stubs
·W-2 forms from the previous two years
·Federal tax returns, when required
·Recent bank statements
·Documentation of additional income
·Information about existing mortgage obligations
·Identification and employment details
·Documentation of gift funds, when applicable
What About Self-Employed Borrowers?
Self-employed borrowers may need additional documentation, including business tax returns, profit-and-loss statements, or business bank statements.
Certain alternative-documentation mortgage programs may be available for qualified borrowers who do not fit traditional income-verification requirements.
A mortgage broker can help assess which options may be appropriate.
Does Mortgage Pre-Approval Guarantee Final Approval?
No.
Even after receiving a mortgage pre-approval letter, several items may still need to be completed.
These can include:
·Property appraisal
·Title review
·Property insurance verification
·Final income and employment verification
·Updated asset documentation
·Final underwriting approval
·Satisfaction of lender conditions
Significant financial changes between pre-approval and closing can affect eligibility.
For example, opening new credit accounts, financing a vehicle, changing employment, or taking on additional debt could create complications.
Avoid major financial changes during the mortgage process without first consulting your mortgage professional.
How Long Does Mortgage Pre-Approval Last?
Many mortgage pre-approval letters are issued with validity periods of approximately 30 to 90 days.
However, the exact period depends on the lender, loan program, credit report requirements, and supporting documentation.
If your home search extends beyond the expiration date, updated documentation or a new credit review may be required.
Should You Get Pre-Qualified or Pre-Approved First?
The best approach depends on your timeline.
If you're six months away from buying:
A preliminary pre-qualification may help you evaluate affordability, identify potential issues, and create a financial preparation plan.
If you're planning to purchase within the next 30 to 90 days:
A more comprehensive pre-approval is generally preferable.
If you're actively making offers:
You should strongly consider obtaining a current pre-approval letter before submitting an offer.
Why Work With a Mortgage Broker Instead of Going Directly to One Bank?
A traditional bank generally evaluates mortgage applications using the loan products and lending guidelines available through that institution.
A mortgage broker can help borrowers explore financing options from multiple wholesale lending sources.
This may be especially useful for borrowers with:
·Nontraditional income
·Self-employment earnings
·Significant student loan debt
·Jumbo mortgage requirements
·Investment property financing needs
·Unique credit or asset circumstances
At Medallion Funds, we focus on understanding the borrower's complete financial picture before evaluating available mortgage structures.
The objective isn't simply to obtain a pre-approval letter. It's to identify financing that aligns with your purchase and financial goals.
Frequently Asked Questions
Can I get pre-approved without finding a house?
Yes. Many borrowers obtain mortgage pre-approval before identifying a specific property. Final approval will still depend on the property and other outstanding conditions.
Does mortgage pre-qualification hurt my credit score?
Not necessarily. Some lenders use a soft inquiry or do not check credit during preliminary pre-qualification. Ask about the inquiry type before proceeding.
Can I get pre-approved with a low credit score?
Possibly. Eligibility depends on the loan program, credit history, income, debts, available assets, and other underwriting factors.
Can I obtain pre-approval from more than one lender?
Yes. Comparing mortgage options can help borrowers evaluate rates, fees, programs, and service levels. Credit scoring models may treat multiple mortgage-shopping inquiries within an applicable window as a single inquiry, although the rules vary by model.
Is a pre-approval letter a guarantee that my loan will close?
No. Final mortgage approval remains subject to underwriting, property review, and satisfaction of lender conditions.
How early should I get mortgage pre-approved?
For borrowers actively preparing to purchase, beginning the pre-approval process before touring homes or making offers is often beneficial.
Final Thoughts: Preparation Creates Better Homebuying Decisions
Understanding the difference between mortgage pre-qualification and pre-approval can help you avoid confusion and prepare for the homebuying process.
Pre-qualification is a valuable initial planning tool.
Pre-approval typically provides a more substantial assessment of your financing eligibility and can help position you as a better-prepared buyer.
Before you fall in love with a home, make sure you understand your financing options.
Ready to Discuss Your Mortgage Options?
I'm Bill Rapp, CCIM, Director of Capital Advisory with Medallion Funds.
Whether you're purchasing your first home, upgrading to a larger property, or evaluating alternative mortgage programs, we can help you explore available financing solutions.
Website: https://billrapponline.com/
YouTube: https://www.youtube.com/@billrapp-medallion-funds
NMLS #228246
Bill Rapp
Partner & Director of Capital Advisory | Medallion Funds
Commercial Lending Nationwide
Residential Lending in AL, CA, CO, NV & TXBottom of Form
https://www.billrapponline.com/
https://findamortgagebroker.com/Profile/WilliamRappJr28883
https://billrapp.commloan.com/
https://billrapponline.com/financingfuturescre-houston-katy
https://houstoncommercialmortgage.com/
https://author.billrapponline.com
https://doctorvideo.billrapponline.com/
https://veteransvideo.billrapponline.com/
https://mortgageviking.billrapponline.com/
https://fha203h.billrapponline.com/
https://renovationvideo.billrapponline.com
https://medallionfunds.com/bill-rapp/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Medallion Funds LLC, Director of Capital Advisory
Subscribe to Our Newsletter
New Released

Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!

"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.