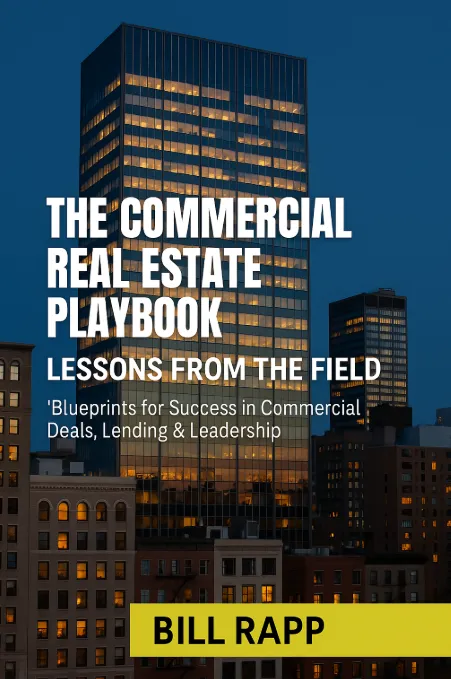
📘 Autographed Collector's Edition – Direct from the Author - CRE Book
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
The Commercial Real Estate Playbook: Lessons From the Fieldis your behind-the-scenes guide to the strategies, mistakes, and mindset shifts that truly matter in today’s CRE world. Written by veteran broker and financing expert Bill Rapp, this book shares the real-world lessons he learned over a decade in the trenches—now available as an exclusive signed copy straight from the author.
Inside this special edition, you’ll discover:
✅ What separates winning deals from disasters
✅ How to confidently transition from residential to commercial real estate
✅ The psychology of reading people and closing with confidence
✅ Financing tips and creative capital strategies across all asset classes
✅ How to build a team, scale your business, and lead through uncertain times
Whether you're an investor, broker, small business owner, or just breaking into the commercial space, this no-fluff guide delivers the real talk—and real tools—you won’t find in a classroom.
Start building your CRE legacy with insights that actually work—and get your hands on a personally autographed copy today.
🏡 Autographed Collector's Edition – Direct from the Author - Residential Book
Buying your first home doesn’t have to be overwhelming—especially when you have a proven, step-by-step roadmap signed by the expert himself.
The Smart Guide to Buying Your First Home
is your friendly, no-nonsense companion through every stage of the homebuying process. Written by trusted
mortgage broker and real estate advisor Bill J. Rapp Jr.
, this autographed copy
offers not just practical advice, but peace of mind—straight from someone who’s helped hundreds of families navigate their first purchase.
Inside this signed special edition, you’ll
learn:
· 🧠 How credit scores
impact your loan—and how to fix yours fast
· 🏦What lenders really want to see and how to get pre-approved like a pro
· 💸Budgeting truths, hidden fees, and the myth of “$0 down”
· 🛠️The importance of building a dream team—agent, lender, and inspector
· 📝What to expect during inspections, appraisals, and closing, pl🇺🇸 Bonus content for VA borrowers, including how to get your COE and maximize your benefits
Every chapter includes clear action steps, checklists, and insider tips to help you stay organized, informed, and
empowered.
Whether you're buying solo, with a partner, or
for your growing family, this personally signed copy
is more than just a how-to guide—it’s your coach, mentor, and trusted friend for the journey ahead.
Order now to get a signed edition shipped directly from the author—and take the first confident step toward homeownership.
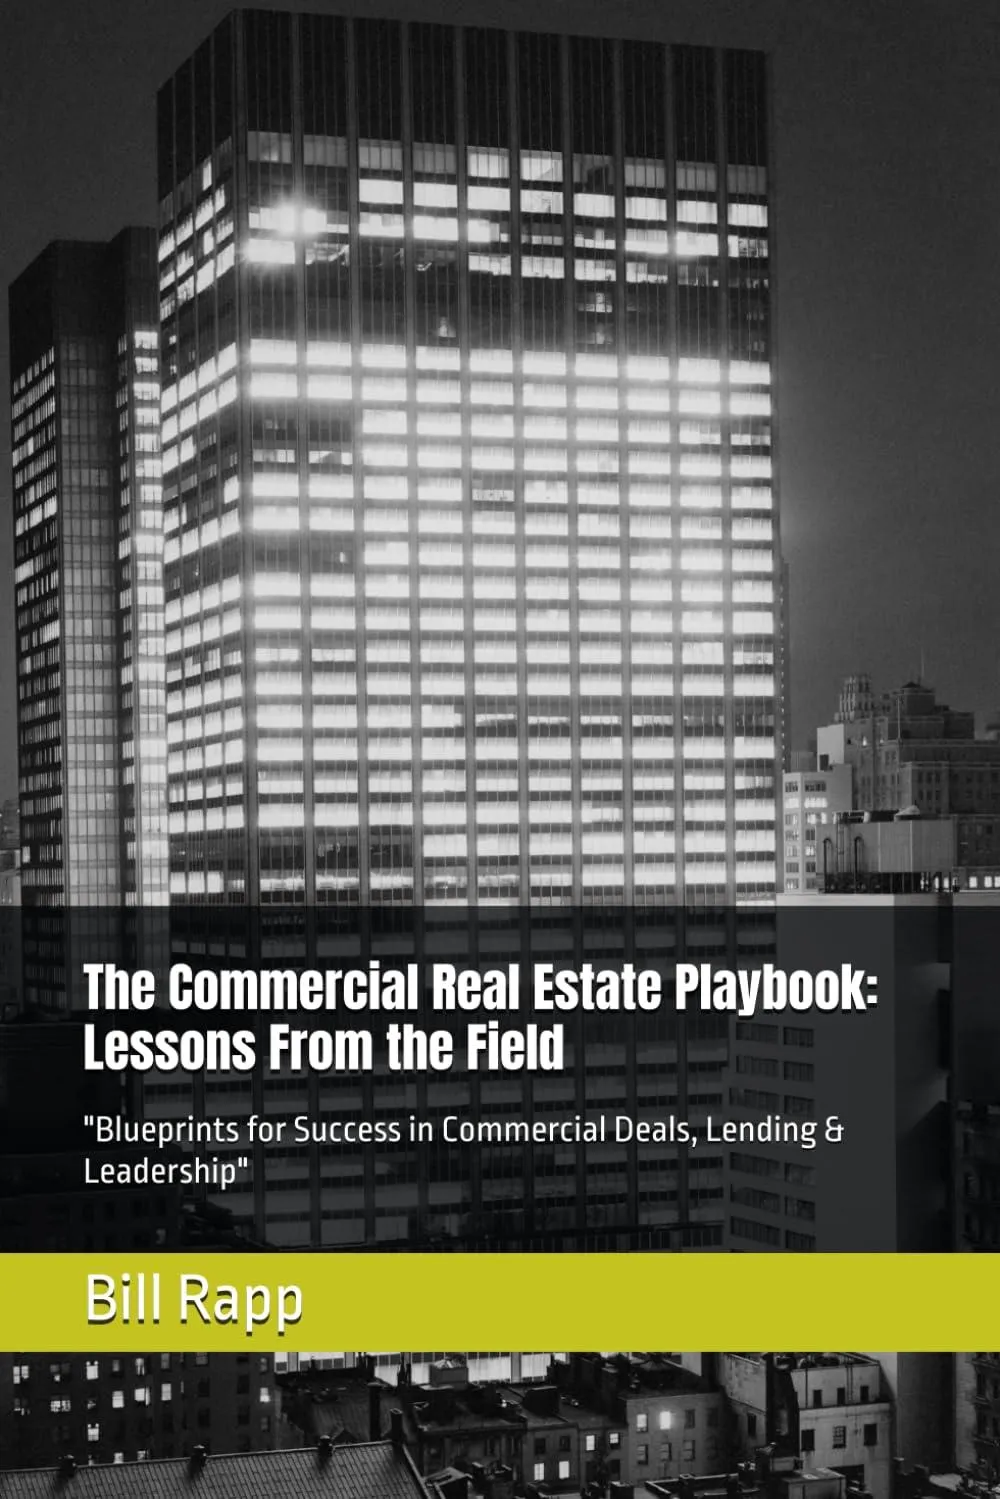
The Commercial Real Estate Playbook: Lessons From the Field:
"Blueprints for Success in Commercial Deals, Lending & Leadership"
What if your next commercial real estate deal could change your life—but no one ever taught you how to make it happen?
In
The Commercial Real Estate Playbook: Lessons From the Field, seasoned broker and finance expert
Bill Rapp
pulls back the curtain on the real-world strategies, pitfalls, and breakthrough moments that shaped his career—and the careers of countless clients and professionals he’s served.
From structuring your first deal and building your personal brand, to overcoming financing roadblocks and surviving market downturns, this no-fluff guide is packed with firsthand stories, actionable insights, and field-tested tools to help you thrive in today’s complex CRE landscape.
Whether you're an aspiring broker, active investor, small business owner, or someone looking to understand the lending side of real estate, this book offers a front-row seat to lessons that aren’t taught in classrooms—but can make or break your success.
Inside you’ll discover:
What separates successful deals from failed onesHow to transition from residential to commercial with confidenceThe art of reading people and closing like a proSmart financing tactics for every asset class—from retail to multifamilyHow to scale your business, lead a team, and future-proof your career
If you're ready to stop guessing and start building a legacy in commercial real estate, this playbook will be your trusted guide.
The Smart Guide to Buying Your First Home!
"From Credit Scores to Closing Day"
Buying your first home doesn’t have to be overwhelming — not when you have a proven roadmap in your hands.The Smart Guide to Buying Your First Home
is a friendly, practical, and down-to-earth companion for anyone ready to turn the dream of homeownership into a reality. Whether you're just starting to think about buying, already browsing listings, or preparing to make an offer, this guide breaks it all down — step-by-step — in language that makes sense.Written by seasoned mortgage broker and real estate advisor
Bill J Rapp Jr, this guide covers everything you need to know, including:
How your credit score affects your mortgage (and how to fix it fast)What lenders arereallylooking for — and how to get pre-approved like a proBudgeting tips, hidden costs, and why “$0 down” doesn’t mean “free”How to build your dream team and search with strategyThe real-deal guide to inspections, appraisals, and closing dayBonus insights forveterans using VA loans— including how to get your COE, debunking common VA myths, and planning for future moves or refinancing
Plus, you’ll find action steps, checklists, and practical tips in every chapter — making it easy to stay organized, empowered, and confident throughout the process.Whether you’re buying solo, with a partner, or as a growing family, this book will help you make smart decisions and avoid costly mistakes.
It’s more than a how-to manual — it’s a trusted guide, mentor, and coach all in one.Homeownership is a journey — not a race. Let’s take that first step together. 🏡
ABOUT AUTHOR
Bill Rapp
Bill Rapp is a seasoned commercial real estate broker and finance expert with over a decade of experience helping clients navigate complex property transactions and capital solutions. Based in Houston, Texas, Bill specializes in investment sales, acquisitions, and commercial financing strategies tailored to meet the needs of investors, developers, and business owners. He brings a
unique blend of market insight, negotiation skills, and financial acumen to every deal, consistently delivering value and growth opportunities for his clients. With a deep knowledge of the Houston and Greater Texas markets, Bill
is committed to building long-term relationships and helping clients make smart, strategic decisions in today’s ever-evolving real estate landscape. When
he’s not closing deals or analyzing the next big opportunity, Bill enjoys time with family, outdoor adventures, and giving back to the local community through mentorship and service.If you’d like, I can help write or edit these based on
the book content we’ve built so far.
- FOLLOW ON SOCIAL -


🏢 Residential Loan Officer to Commercial Mortgage Broker: Your Step-by-Step Career Transition Guide 🚀
🏢 Residential Loan Officer to Commercial Mortgage Broker: Your Step-by-Step Career Transition Guide 🚀
💰 Ready to Expand Beyond Residential Mortgages? How to Become a Successful Commercial Mortgage Broker 🏦
________________________________________________________________________________
Residential Loan Officer to Commercial Mortgage Broker: How to Make the Transition
If you're a residential mortgage loan officer looking for ways to diversify your business, expand your referral network, and serve a broader range of borrowers, commercial mortgage brokerage may be a natural next step.
You've already developed valuable skills: understanding credit, managing loan applications, working with borrowers, evaluating financing options, and guiding transactions from application to closing.
But here's something important to understand:
Commercial mortgage lending is not simply residential lending with larger loan amounts.
Commercial real estate financing operates under a different underwriting framework. Lenders evaluate property cash flow, business performance, market fundamentals, borrower experience, and exit strategies.
The good news? Residential loan officers already possess many transferable skills that can provide a foundation for success.
Let's explore how to make the transition strategically.
Why Residential Loan Officers Should Consider Commercial Mortgage Brokerage
Residential mortgage origination can be highly sensitive to interest rates, housing inventory, consumer confidence, and refinancing activity.
Commercial mortgage brokerage offers access to additional financing needs, including:
Commercial real estate acquisitions
Investment property refinancing
Multifamily apartment financing
Owner-occupied business properties
Industrial and warehouse financing
Retail and office buildings
Self-storage properties
SBA 7(a) and SBA 504 financing
Commercial construction and bridge loans
Commercial borrowers also have financing needs that extend beyond a single purchase.
Investors may acquire additional properties, refinance existing debt, fund renovations, or restructure their portfolios.
Business owners may purchase the buildings they occupy, expand operations, or refinance commercial properties.
The opportunity isn't just to originate a larger loan. It's to build long-term commercial financing relationships.
However, commercial transactions can involve longer closing cycles, greater documentation requirements, and more complex negotiations. Larger loan amounts do not automatically translate into greater profitability.
1. Understand the Fundamental Differences Between Residential and Commercial Lending
The first step in becoming a commercial mortgage broker is understanding how commercial loans are evaluated.
Residential Mortgage Underwriting
Residential lenders generally focus on:
Borrower credit history
Personal income and employment
Debt-to-income ratio (DTI)
Down payment and reserves
Property appraisal
Loan-to-value ratio (LTV)
For many residential transactions, the borrower's ability to repay the mortgage from qualifying personal income is central.
Commercial Mortgage Underwriting
Commercial lenders may evaluate:
Net operating income (NOI)
Debt service coverage ratio (DSCR)
Loan-to-value ratio (LTV)
Debt yield
Property occupancy and tenant quality
Lease terms and expiration schedules
Borrower liquidity and net worth
Sponsor experience
Business operating cash flow
Market conditions and property type
For income-producing commercial properties, the property's financial performance often becomes a primary consideration.
For owner-occupied commercial real estate, the operating business's financial performance may be equally important.
Understanding these distinctions is essential before attempting to originate commercial financing.
2. Learn the Three Commercial Lending Metrics Every Broker Must Know
Three financial metrics appear repeatedly in commercial mortgage underwriting.
Debt Service Coverage Ratio (DSCR)
DSCR measures the relationship between a property's net operating income and its annual debt service.
DSCR = Net Operating Income ÷ Annual Debt Service
Suppose an apartment building generates $180,000 in annual NOI and has $135,000 in annual mortgage payments.
DSCR = $180,000 ÷ $135,000 = 1.33x
This means the property generates approximately $1.33 in NOI for every $1.00 of annual debt service.
A lender might require a minimum DSCR of 1.20x, 1.25x, or higher, depending on the loan program and risk profile.
Loan-to-Value Ratio (LTV)
LTV measures the requested loan amount relative to the property's value.
LTV = Loan Amount ÷ Property Value
For a $2 million property with a $1.4 million loan:
LTV = $1,400,000 ÷ $2,000,000 = 70%
Commercial LTV limits vary by lender, property type, borrower strength, and financing structure.
Debt Yield
Debt yield measures property NOI relative to the loan amount.
Debt Yield = Net Operating Income ÷ Loan Amount
For a property producing $150,000 in NOI with a $1.5 million loan:
Debt Yield = $150,000 ÷ $1,500,000 = 10%
Unlike DSCR, debt yield is not directly affected by the interest rate or amortization schedule.
A successful commercial mortgage broker understands how DSCR, LTV, and debt yield interact—not just how to calculate them individually.
3. Understand the Different Types of Commercial Mortgage Loans
Residential loan officers entering commercial financing should become familiar with several major financing categories.
Conventional Commercial Real Estate Loans
Banks, credit unions, and other commercial lenders finance qualifying income-producing and owner-occupied properties.
These programs may offer competitive structures for established borrowers and stabilized assets.
SBA 7(a) Loans
SBA 7(a) financing can help eligible businesses purchase qualifying commercial real estate and finance certain additional business needs.
Loan proceeds may support eligible equipment, working capital, business acquisitions, and other authorized purposes.
SBA eligibility, occupancy, use-of-proceeds, and lender requirements apply.
SBA 504 Loans
SBA 504 financing is generally designed for qualifying long-term fixed assets, including owner-occupied commercial buildings and major equipment.
A common structure combines a third-party lender, a Certified Development Company, and a borrower contribution.
Some qualifying projects may require a borrower contribution as low as 10%, although higher contributions can apply.
Multifamily Financing
Apartment financing may involve conventional banks, agency lenders, HUD programs, debt funds, or bridge lenders.
Each option has different underwriting, occupancy, property condition, and borrower requirements.
Bridge and Private Credit Financing
Bridge loans may help investors acquire, renovate, reposition, or stabilize properties that do not yet qualify for permanent financing.
These loans typically require a credible exit strategy and may carry higher financing costs.
The objective isn't to memorize every commercial loan program.
It's to understand which financing structures match particular properties, borrowers, and business plans.
4. Build a Commercial Real Estate Referral Network
Residential loan officers already understand the importance of referral relationships.
The difference is identifying the professionals who regularly encounter commercial financing needs.
Potential referral partners include:
Commercial real estate brokers
Business brokers
CPAs and tax advisors
Commercial bankers
Real estate attorneys
Commercial property managers
Commercial developers
Business owners and investors
Residential real estate agents with investor clients
A particularly useful strategy is developing relationships with commercial bankers.
Banks may decline transactions because of property-type restrictions, concentration limits, loan size, geographic limitations, or internal lending policies.
A declined bank loan does not necessarily mean the underlying transaction is unfinanceable.
It may mean the borrower needs a different lender or capital structure.
Commercial mortgage brokers can create value by evaluating whether another financing source fits the transaction.
5. Learn How to Package a Commercial Loan
Commercial lenders expect borrowers and intermediaries to provide enough information to evaluate the property, financial performance, and proposed financing.
For investment real estate, a preliminary package may include:
Purchase contract or financing request
Current rent roll
Trailing 12-month operating statement (T-12)
Historical property financial statements
Property description and photos
Existing loan information, if refinancing
Borrower financial statement
Schedule of real estate owned
Proposed capital improvements and business plan
For owner-occupied commercial real estate, lenders may also request business financial statements, tax returns, ownership information, and operating projections.
A well-organized submission allows lenders to identify financing strengths and potential obstacles more efficiently.
Commercial mortgage brokers create value before a loan ever reaches underwriting.
They help identify missing information, assess potential financing constraints, and present the transaction clearly.
6. Use Commercial Lending Technology to Expand Your Reach
One of the challenges facing new commercial mortgage brokers is developing relationships with lenders across different asset classes and financing structures.
A local bank might finance owner-occupied industrial buildings but avoid hospitality properties.
Another lender may specialize in multifamily acquisitions.
A private credit fund may consider transitional properties that conventional banks cannot finance.
This is where commercial lending marketplaces can help.
Through the CommLoan Empower Program, capital advisors can work with the CommLoan platform and its CUPID™ technology to help identify potential financing options across a marketplace of more than 700 lenders.
Instead of relying exclusively on a small number of lender relationships, advisors can explore a broader range of financing sources.
Technology does not eliminate the need for commercial underwriting expertise.
It can, however, improve lender discovery and support a more structured financing process.
Actual lender participation, available programs, financing terms, and approvals depend on the transaction and platform requirements.
7. Start With the Commercial Transactions You Already Understand
Residential loan officers do not need to begin their commercial careers with complicated $20 million development transactions.
Start with financing scenarios that have familiar elements.
Examples include:
Small Multifamily Properties: Financing apartment buildings where rental income and operating expenses drive underwriting.
Owner-Occupied Commercial Buildings: Helping an established business purchase the office, retail, or industrial property it occupies.
Investor Refinancing: Assisting an investor with a maturing commercial mortgage.
SBA-Eligible Real Estate Purchases: Working with eligible small businesses seeking to purchase facilities for their operations.
Begin with straightforward transactions and build your knowledge of more specialized financing structures over time.
8. Real-World Example: From Residential Borrower to Commercial Client
Imagine a residential loan officer who has helped a successful business owner purchase a home.
Several years later, that same client decides to purchase a $1.5 million commercial building for their growing business.
The client asks whether the loan officer can help arrange financing.
A residential-only originator might refer the client elsewhere.
A properly authorized and trained commercial mortgage broker could evaluate the transaction.
The broker would first determine whether the business intends to occupy the property and whether SBA financing may be appropriate.
Next, the broker would review the business's operating history, financial statements, proposed occupancy, borrower contribution, and repayment capacity.
Potential financing options could include a conventional commercial mortgage, SBA 7(a), or SBA 504 financing.
For illustration, a 10% borrower contribution on a $1.5 million project would equal $150,000. However, the actual contribution depends on the eligible project cost, program structure, and lender requirements.
The borrower may also need funds for closing costs and other expenses.
The lesson is straightforward.
The residential loan officer already had the relationship. Commercial lending expertise creates an opportunity to serve that client's next business financing need.
9. Avoid These Common Mistakes When Entering Commercial Lending
New commercial mortgage brokers should avoid several costly assumptions.
Mistake 1: Assuming Commercial Loans Underwrite Like Residential Mortgages
Property cash flow, business performance, and commercial risk factors require a different analytical approach.
Mistake 2: Quoting Terms Before Reviewing Financials
An attractive advertised rate or LTV does not establish that a transaction qualifies.
Mistake 3: Ignoring the Exit Strategy
Bridge and construction lenders need to understand how their loans will be repaid.
Mistake 4: Relying on One Lender
A limited lender network may restrict the financing solutions available to clients.
Mistake 5: Overlooking Licensing and Compliance
Commercial mortgage broker requirements vary by state, transaction, collateral type, and borrower circumstances.
Loans secured by one-to-four-family residential property can trigger mortgage licensing and consumer protection requirements even when described as investor or business-purpose financing.
Commercial brokers must also consider applicable compensation, disclosure, advertising, privacy, and state commercial financing rules.
Confirm the legal and compliance requirements before originating transactions.
10. A Practical 90-Day Transition Plan
A structured approach can help residential loan officers enter commercial financing more effectively.
Days 1–30: Education and Preparation
Study commercial loan products, DSCR, LTV, debt yield, property cash flow, and basic underwriting.
Evaluate commercial lending platforms, training resources, and applicable licensing requirements.
Days 31–60: Referral Development
Reconnect with business-owner clients, investors, CPAs, bankers, and commercial real estate professionals.
Explain the commercial financing scenarios you are prepared to evaluate.
Focus on education and relationship development rather than promising approvals.
Days 61–90: Origination and Execution
Begin reviewing suitable commercial financing opportunities.
Develop standardized intake procedures, organize documentation, and work with experienced commercial financing professionals when needed.
Track your pipeline, referral activity, lender feedback, and transaction milestones.
Your first 90 days should be about establishing a repeatable process—not chasing every possible commercial loan.
Final Thoughts: Expand Your Mortgage Career With Commercial Financing
Transitioning from residential mortgage origination to commercial mortgage brokerage requires education, patience, relationship development, and a different underwriting mindset.
But residential loan officers already have a valuable foundation.
They understand borrowers, financing processes, documentation, and the importance of professional relationships.
By adding commercial underwriting knowledge and broader lender access, they can expand the range of financing solutions they offer.
Ready to Explore Commercial Mortgage Brokerage?
I'm Bill Rapp, CCIM, with the CommLoan Empower Program.
I work with commercial real estate financing and understand the value of matching borrowers, properties, and financing structures with appropriate lenders.
If you're a residential loan officer exploring commercial lending—or a business owner or investor seeking commercial real estate financing—let's discuss your options.
Top of Form
Bottom of Form
Bill Rapp, CCIM
Director | CommLoan
📞 281-222-0433
📧 [email protected]
🌐 https://billrapp.commloan.com/
🌐 https://HoustonCommercialMortgage.com/
Commercial Real Estate Financing Nationwide
https://billrapp.commloan.com/
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
©Bill Rapp, CCIM - Director - CommLoan
Subscribe to Our Newsletter
New Released
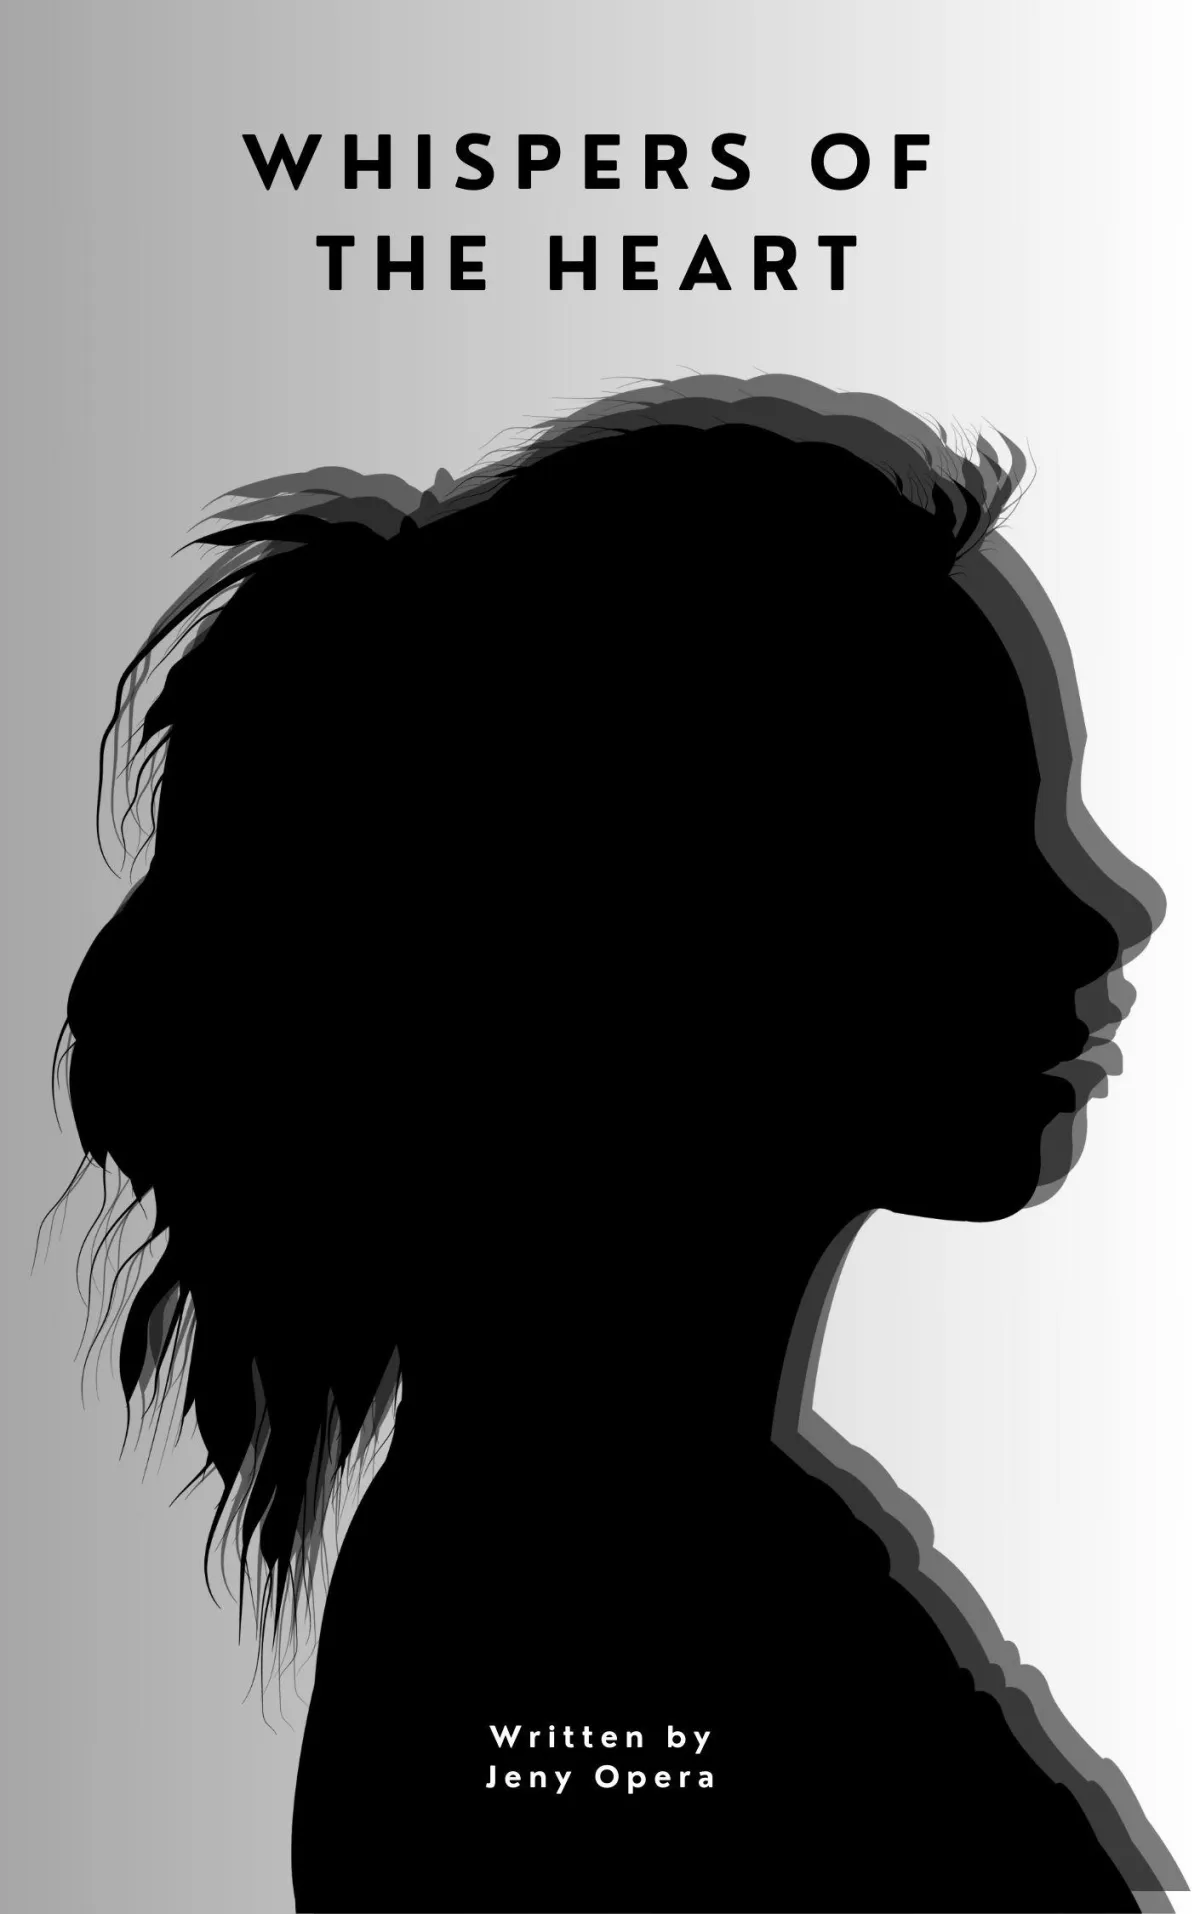
Historical Romance
Whispers of the Heart
A young woman stumbles upon a hidden love letter from the past, leading her on a journey to uncover a long-forgotten romance that changed her family forever.
Over A Million Copies Sold!
Stats
Your Perfect Read, Our Promise
Discover the difference our books make through key statistics. From captivating plots to satisfied readers, our numbers showcase the quality, creativity, and trust that define our literary works.
1M+
Satisfied Readers

100+
Books Published
50+
Genres Explored
- LATEST BOOKS -
All Latest Books
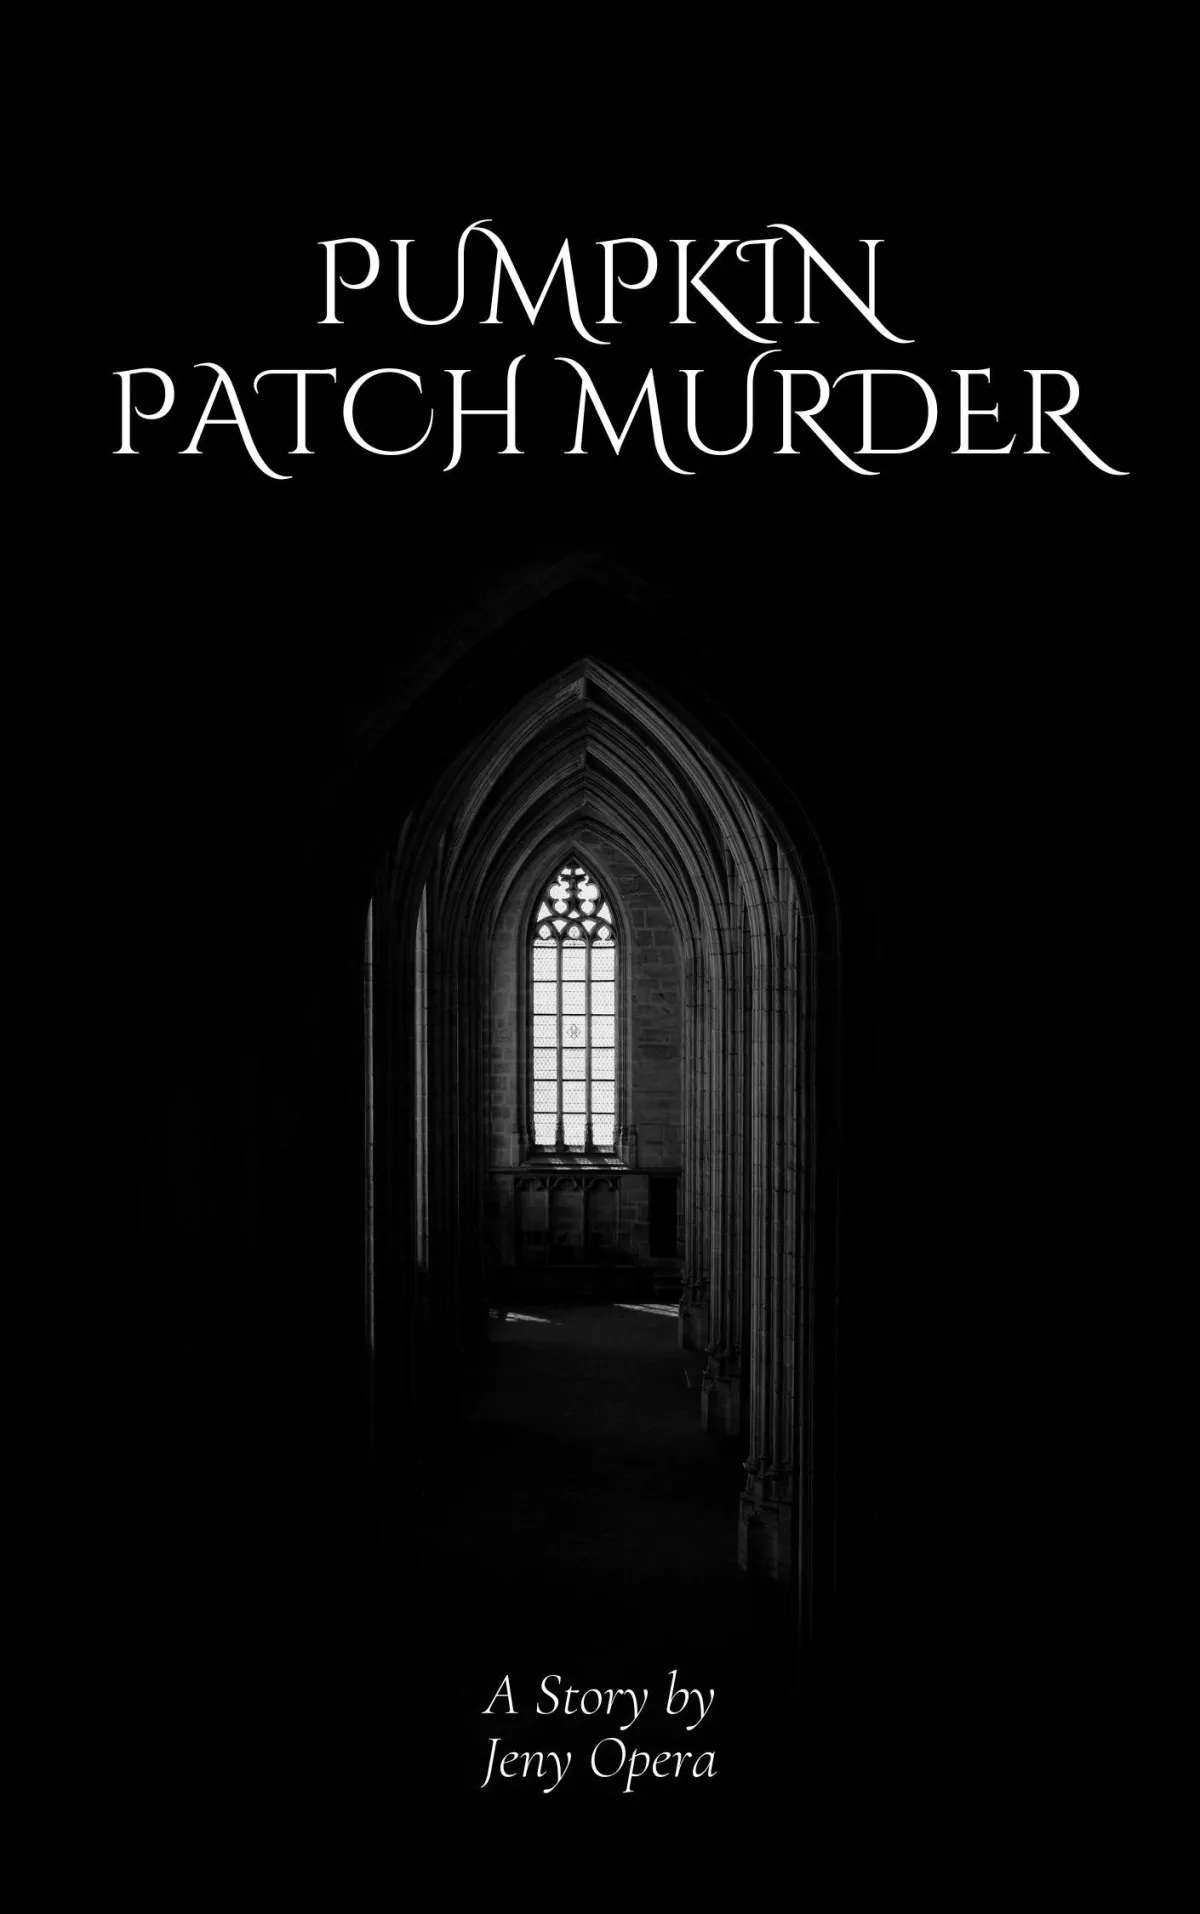
Pumpkin Patch Murder
A farm owner investigates a murder at the pumpkin patch just before Halloween, racing to solve the crime before the season is ruined.
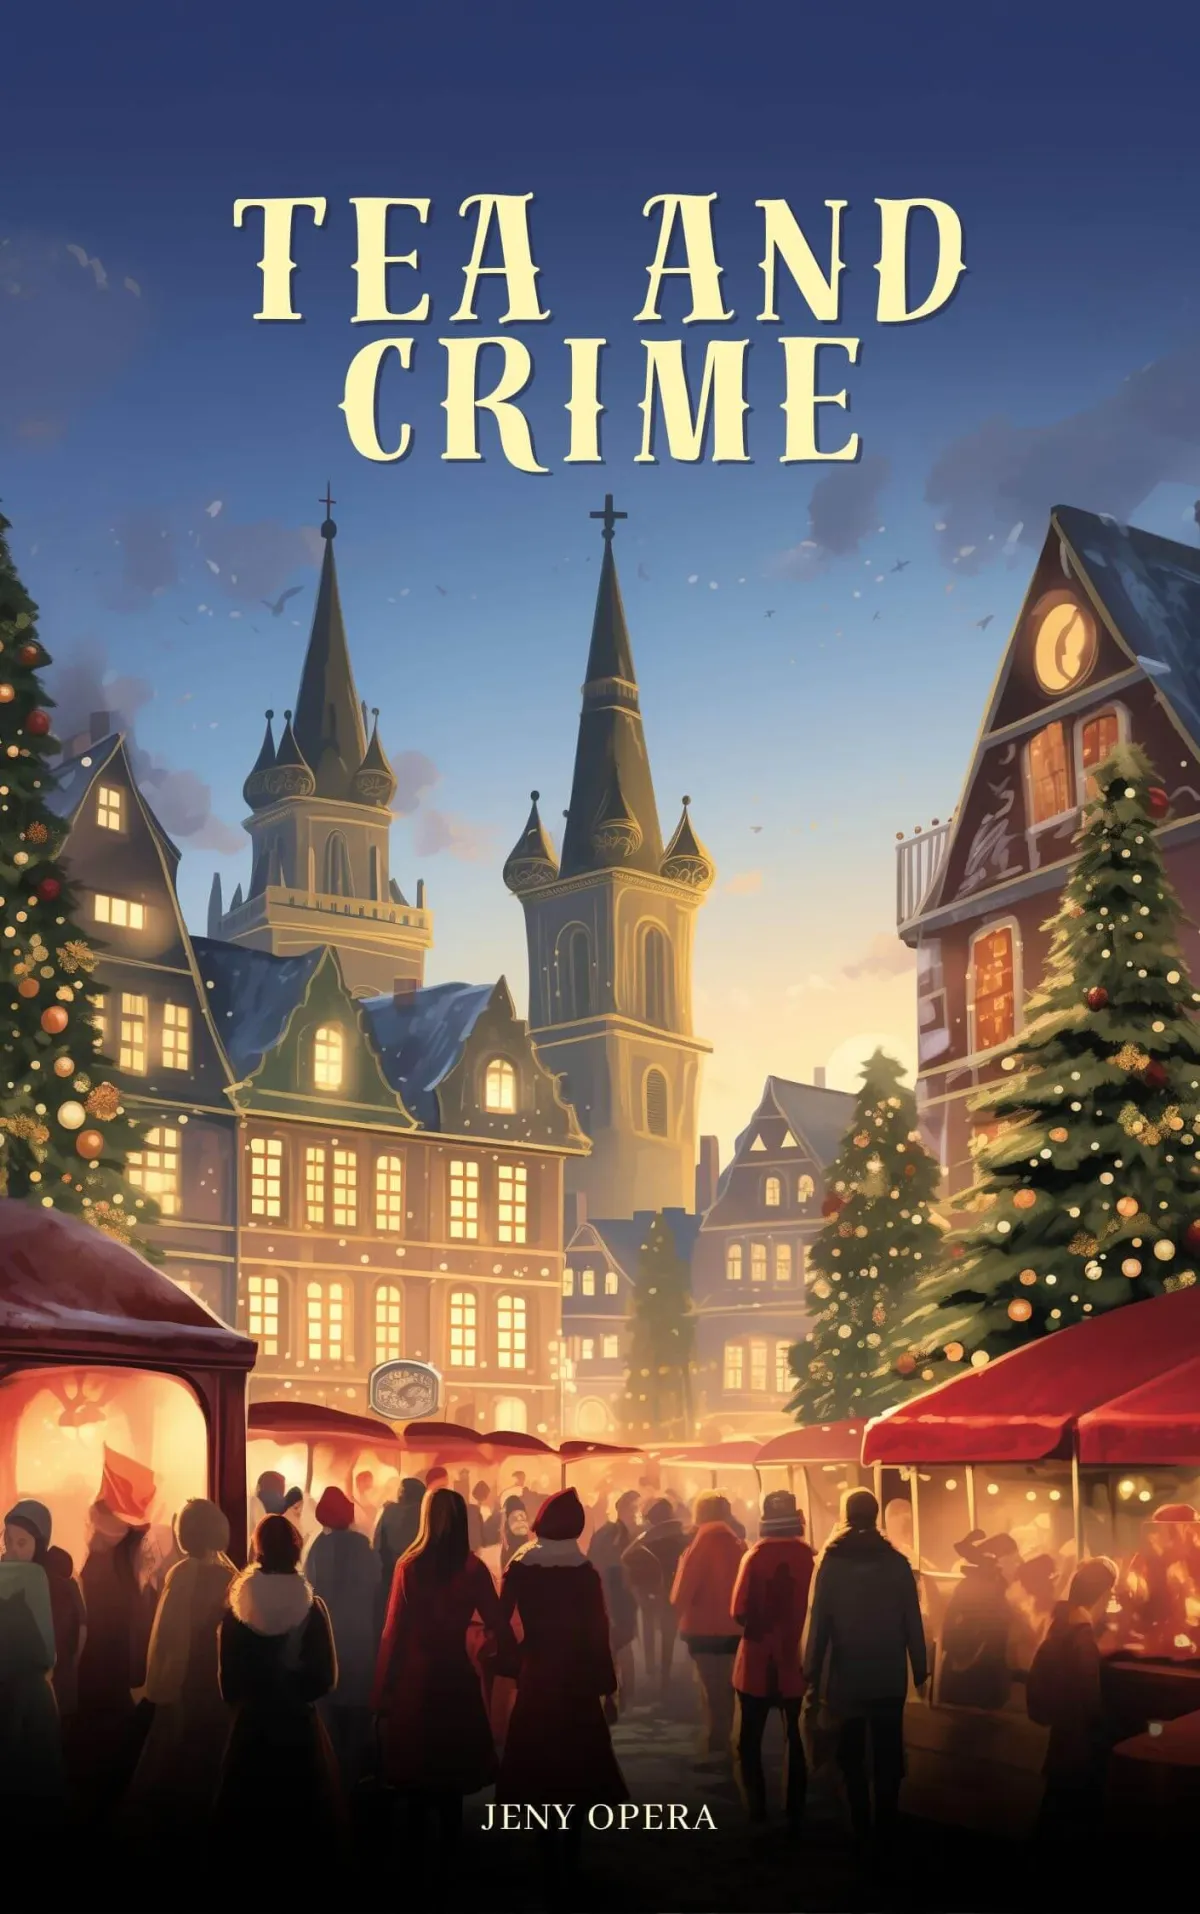
Tea and Crime
A café owner investigates a murder after one of her loyal customers is found dead in her shop.
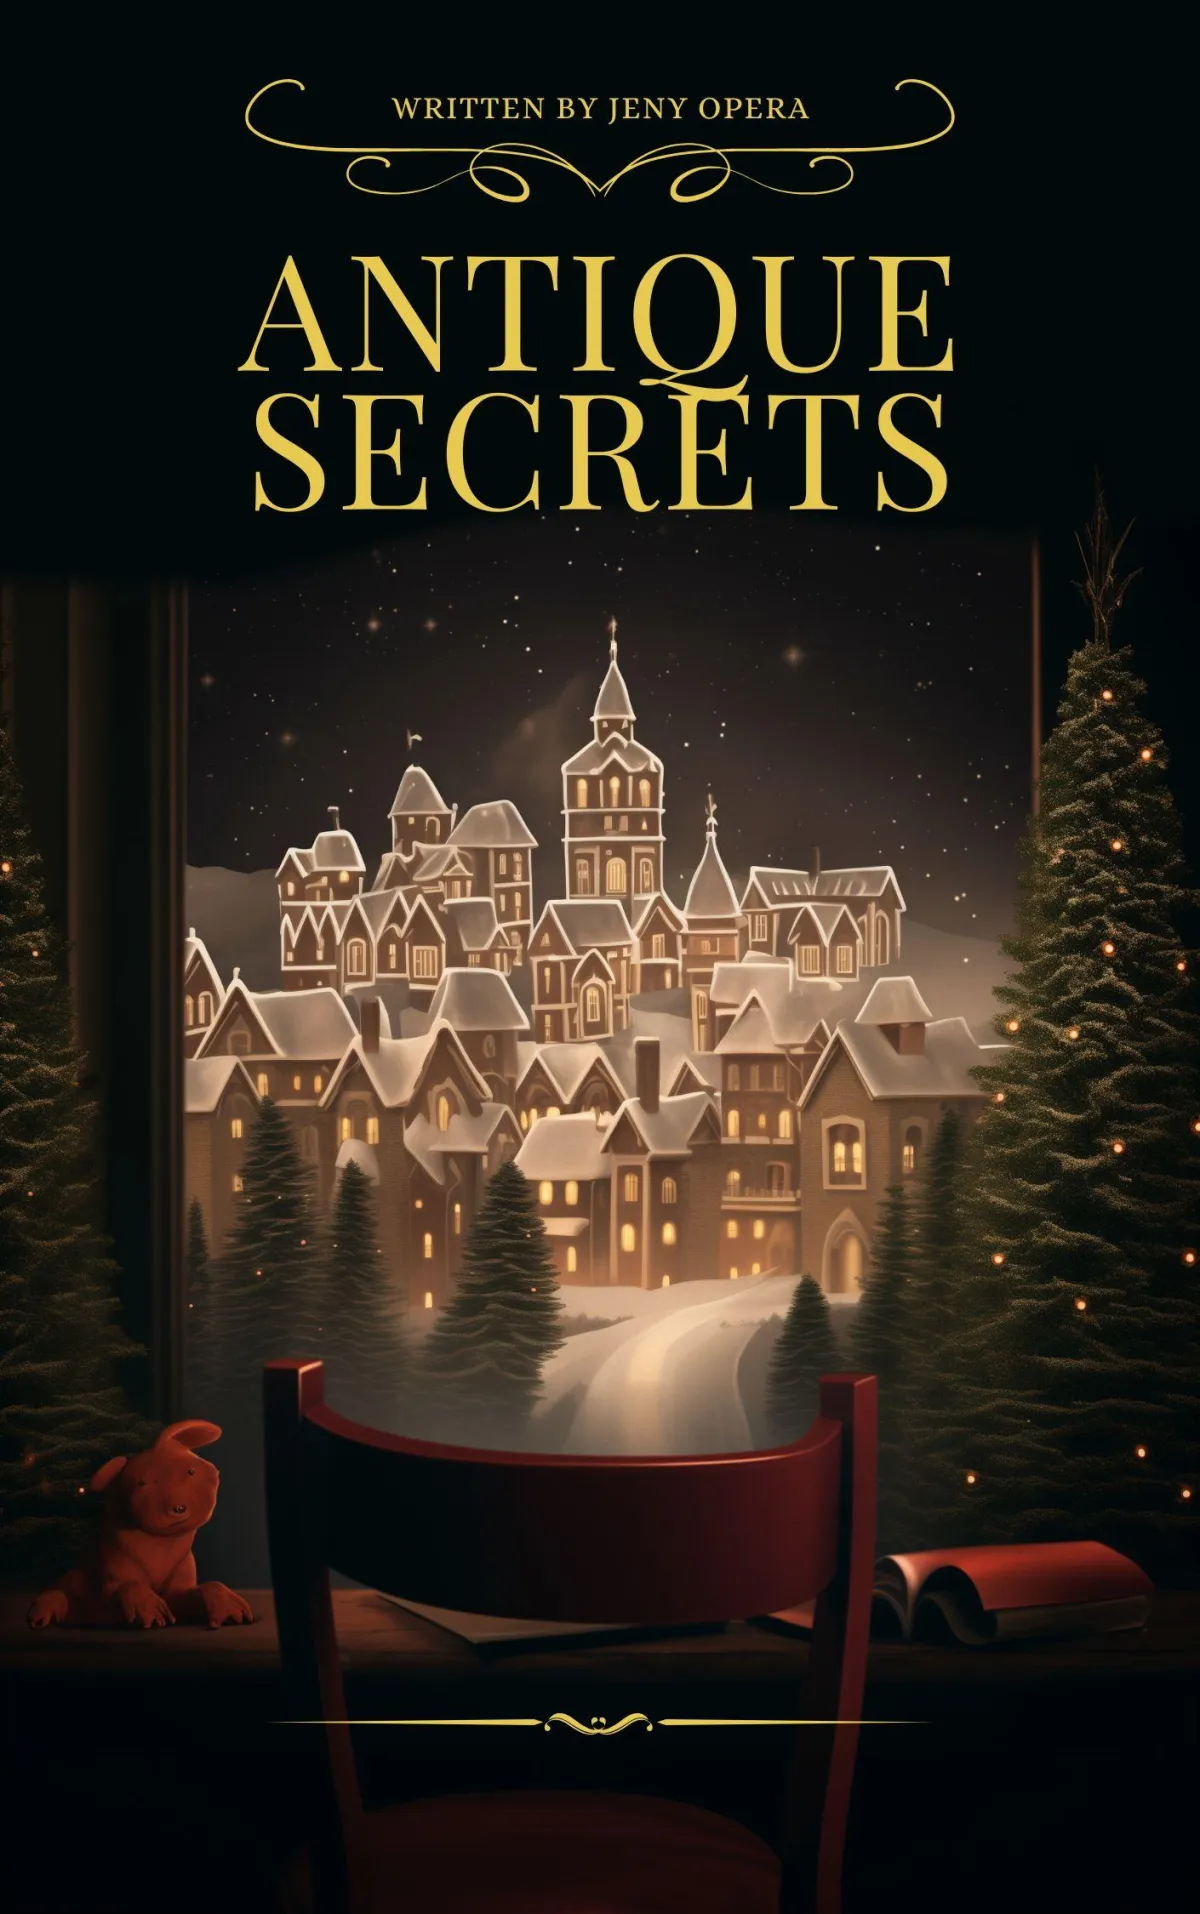
Antique Secrets
An antique store owner uncovers a hidden diary and is drawn into a decades-old mystery.
OUR WORK
What People Are Saying!
"I was hooked from the first page! This author’s storytelling is captivating, and the plot twists kept me on the edge of my seat. Can't wait for the next book!"
Sarah Thompson
"An incredible read! The characters felt so real, and the pacing was perfect. I couldn't put it down. Highly recommend to any mystery lover!"
Lia Johnson
"This author never disappoints! The writing is gripping, the plot unpredictable, and the suspense builds perfectly. Another fantastic book!"
Ethan Clark
- OUR BLOG POST -
Latest News & Article
Januuary 12, 2024
Mastering the Art of Character Development: Tips for Writing Compelling Protagonists
April 11, 2023
Cover Design 101: Tips for Creating an Eye-Catching...
June 25, 2023
Plotting 101: How to Create a Gripping Story Arc from Start to Finish
Dec 16, 2023
The Power of Dialogue: How to Write Conversations that Drive Your Story Forward
Frequently Asked Questions
What types of books do you write?
We specialize in a wide range of genres including historical fiction, romance, mystery, fantasy, and more. Our goal is to create stories that captivate and engage readers from all walks of life.
Where can I purchase your books?
Our books are available on major platforms like Amazon, Barnes & Noble, and local bookstores. You can also find them in e-book and audiobook formats for easy access.
Do you offer signed copies of your books?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
How can I stay updated on your new releases?
Subscribe to our newsletter for the latest updates, book releases, and exclusive offers. Follow us on social media to stay connected and receive real-time news.
Do you accept book reviews from readers?
Absolutely! We encourage our readers to leave reviews on platforms like Goodreads, Amazon, or personal blogs. Your feedback helps us grow and reach new audiences.
Can I request a book to be personalized?
Yes, we offer personalized book services. Please contact us directly for more information on how we can make your book special.
Drain Repair And Maintenance
You can contact us through our website’s contact page, or by emailing us directly. We love hearing from readers and potential collaborators!
Do you have a fan club or book club?
We have an active community of fans! Join our book club or fan group online to discuss books, share recommendations, and enjoy exclusive content from our latest releases.
COMPANY
LEGAL
FOLLOW US

©Copyright 2026.. All Rights Reserved.